The guide explains what instant means after release and which checks, limits and bonus conditions can affect a PayID payout.
“Instant” describes one part of a PayID withdrawal, not necessarily the time from submitting a request to seeing money in your account. The distinction is between the casino’s handling of the request and the subsequent bank transfer. PayID can support a real-time transfer once funds have been released, but it does not make the earlier handling disappear.
PayID is Australia’s bank-to-bank payment system, operating through the New Payments Platform (NPP). It allows a payment to be directed using a PayID identifier rather than relying only on standard account details. Transfers through PayID are processed in real time through the Osko network. These features concern the movement of funds between accounts; they do not determine when a casino authorises a withdrawal.
A withdrawal therefore has two different timing questions. First, how long does it take for the operator to approve and release the funds? Second, how long does the bank transfer take after release? The word “instant” most directly describes the second stage. If a withdrawal is waiting in an operator’s system, the NPP cannot transfer money that has not yet been sent.
When choosing an instant PayID withdrawal option in Australia for 2026, check what each operator actually states about withdrawals and other practical details. This shortlist gives you a concise reference for the information available on each.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 via POLi. Its stated licence is Curacao.
DragonSlots Casino
DragonSlots Casino is listed under the Curacao Gaming Authority, with Jumpman Gaming Ltd as the named operator.
Wild Tokyo
Wild Tokyo lists crypto payouts in 30–60 minutes and fiat payouts in 1–5 days. Its minimum deposit is A$10.
MrPacho
MrPacho lists crypto payouts in 30–120 minutes and fiat payouts in 24–72 hours. The minimum deposit is A$30.
LevelUp Casino
LevelUp Casino lists a Curacao eGaming licence, OGL/2023/174/0082, under Dama N.V. Its minimum deposit is A$15.
Playfina Casino
Playfina Casino is listed under Curacao eGaming, with Hollycorn N.V. and a stated licensing history since 2017. Its minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino is listed under Curacao eGaming, with Roby Games Ltd as the named operator.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board licence, OGL/2023/176/0095, under Hollycorn N.V.
7Bit Casino
7Bit Casino is listed as a Curacao casino operated by Dama N.V.
Kingmaker
Kingmaker lists crypto payouts at about 90 minutes and fiat payouts in 1–5 days. Its minimum deposit is A$30.
A specialist review has described PayID funds as moving instantly after a casino releases them. Read that as a description of the payment stage, not as a promise about the entire withdrawal. The release point matters: before it, the operator still controls the request; after it, the payment network and the receiving bank handle the transfer. Each stage has a different cause of delay.
This is why two accounts of an “instant PayID withdrawal” can sound contradictory while describing different events. One person may be counting from the moment the operator sends the payment. Another may be counting from the moment they click the withdrawal button. The first clock begins after approval; the second includes any time the request spends awaiting the operator’s decision. Without knowing where the clock starts and stops, “instant” is too imprecise to describe the full experience.
A specialist review has also reported cases in which sites promoted instant withdrawals but took as long as 24 hours because of internal review. That illustrates the boundary of the claim: a real-time transfer capability does not prevent a site from holding a request before release. The report should not be treated as a universal timetable for every operator, but it shows why the advertised label alone cannot establish when a withdrawal will reach a bank account.
For a practical reading of any instant claim, separate the wording into its implied events. Does it refer to the payment network’s transfer after release, or to the whole period beginning with your request? Does the operator specify that the request must first be approved? If the starting point and release condition are not clear, the claim does not tell you the total elapsed time. This is not a technical flaw in PayID: it is a difference between the payment system’s role and the operator’s role.
The phrase “instant PayID withdrawal” can therefore refer to a fast transfer after authorisation, while leaving the authorisation period outside the claim. A casino may need to process a request before it can send the funds; the NPP and Osko do not replace that step. The relevant measure for the recipient is the complete interval from request to receipt, whereas the network’s transfer time accounts only for the portion after funds are released.
There is also a legal context for Australian readers. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games, including slots and table games, to people physically located in Australia. The payment mechanics described here explain what the terms “PayID” and “instant” mean; they are not an endorsement or invitation to use an online casino service.
In short, “instant” is best understood as a statement about the transfer after release, not a guarantee that every withdrawal request will be approved and received immediately. To interpret the term accurately, identify which event starts the stated clock and whether operator approval is included. PayID can make the bank-to-bank payment real time; it cannot make the full request-to-receipt process equivalent to that transfer stage.
Attention: The term "instant" typically refers to the bank transfer speed after funds are released, not the total time from your initial request to receipt.
A payout-speed claim is a description of reported performance, not a promise that every withdrawal will arrive within the stated time. When you see a figure, check what event the clock measures: the withdrawal request, the operator’s release of funds, or the receipt of money in the linked bank account. These are different points in a transaction, so a short figure can be accurate for one stage without describing the full elapsed time.
The wording also matters. “Under five minutes” sets a stated upper boundary for the cases being described; it does not tell you how many withdrawals met that boundary or whether the figure applies to all account types. An average is different again: it summarises a group of observed transactions, while allowing individual cases to take longer or less time. Neither wording, on its own, establishes what will happen to your withdrawal.
A specialist review reported that some leading Australian PayID casino options had withdrawals processed in under five minutes, while standard bank transfers were reported at one to three business days. The same type of review described some PayID results as averaging 30–90 seconds. Treat those as reported observations, not as a current market-wide benchmark or a guaranteed service level. The results may describe a particular set of operators and transactions, and the figures can become outdated as services change.
To assess a claim, look for its scope and measurement method. Does it say whether the reported cases were typical, or merely the fastest observed? Does it specify when timing began and ended? Does it distinguish a stated processing target from completed transactions? If those details are absent, the number gives limited grounds for predicting your own receipt time. A precise figure can sound definitive while leaving the key measurement boundaries unclear.
Also check whether the claim is conditional. A speed statement may apply only to withdrawals meeting the operator’s requirements, rather than to every request. Read it alongside the published withdrawal terms, including any stated processing times and limits. Do not infer that a short advertised time removes conditions or guarantees an outcome.
In Australia, real-money online casino services are prohibited for operators to provide to people physically located in the country under the Interactive Gambling Act 2001. A speed claim should not be read as confirmation that a service is lawful or available to Australian residents. Treat payout figures as claims to evaluate, not as a recommendation to use a platform or as assurance of instant receipt.
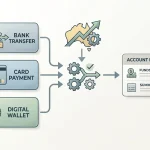
Once a withdrawal has been approved, the payment instruction must still be directed to the right bank account. PayID provides the identifier for that destination: depending on the account setup, it may be a mobile number, email address or another registered PayID. The casino sends the approved funds using the details supplied for the withdrawal; the receiving bank then matches the PayID to the account linked to it.
That hand-off depends on the destination being valid and accessible. A mistyped identifier, an identifier linked to an account you cannot use, or details that do not match the casino profile can interrupt the route. A transfer should therefore go only to an account linked to your casino profile. If the casino asks you to enter a PayID identifier, amount and confirmation in its withdrawal form, check the destination details before confirming. The form’s confirmation shows that a request was submitted; it does not, by itself, establish that the bank has credited the funds.
After the payment instruction is released, PayID transfers move through Australia’s New Payments Platform, with Osko processing the transfer in real time. In practical terms, that is the bank-to-bank leg of the route. It is separate from the casino’s handling of the withdrawal request: the payment network cannot send funds that the operator has not released. Once sent, the receiving bank’s account record is where you can verify whether the payment has arrived. A casino status label and a bank transaction record describe different points in the route.
The account details matter because PayID identifies a destination, not a person’s entitlement to withdraw. If you use an identifier that resolves to a different account from the one associated with your profile, the casino may need to check the request rather than complete the hand-off. Keep the casino account and receiving account details consistent, and do not treat a submitted request as proof of receipt.
A fee is another condition to check before the transfer. Filmink.com.au has reported that a charge may apply to a PayID withdrawal; this is not a reason to assume that every transfer has a fee or that the charge is the same across providers. Read the operator’s stated terms and any fee shown in the withdrawal flow, then compare the amount displayed with the amount you expect to receive. If a fee is deducted, the net credit can differ from the requested withdrawal.
There is also a legal boundary in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. This description is about how a bank transfer route works, not an endorsement or invitation to use an online casino.
A payment network can transmit an approved payment quickly, but it cannot approve a withdrawal on the operator’s behalf. The time shown for a PayID casino instant withdrawal therefore needs to be read as a claim about a particular stage, not as a promise that money will arrive as soon as you submit a request.
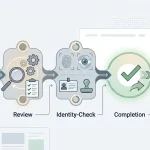
A withdrawal has a decision point before the bank transfer begins. The operator must process the request and verify your identity through KYC procedures before processing a withdrawal. Until the operator releases the funds, the payment has not entered the transfer stage. A real-time network cannot shorten work that is still taking place inside the operator’s system.
This distinction explains why a request and a receipt can be separated by different amounts of time, even when PayID itself supports rapid transfers. A request may be waiting for review; an approved payment may then be sent to the linked account. The first interval belongs to the operator’s processing, while the second is the payment stage. Treating them as one uninterrupted event obscures where a delay is occurring.
A specialist review of online casino payment speeds notes that timing can be affected by several factors. That observation is useful as a general warning, but it does not establish a fixed processing time for every operator or request. The practical question is whether a stated speed begins when you submit the withdrawal or only after the operator approves and releases it. If the wording does not identify that starting point, it does not tell you the full time from request to receipt.
The distinction also matters when a review is required. A payment may be technically ready to move through the network while the operator has not yet authorised it. In that state, repeating the request or interpreting the delay as a bank-transfer problem will not resolve the outstanding decision. The status shown in the account, and the operator’s stated process, are more informative than the network’s transfer capability.
Operators must verify a player’s identity before processing withdrawals. Any manual review process for withdrawals exceeding $2,000 must also be disclosed. These checks are part of the approval stage, not evidence that PayID has failed. If the operator has not released the funds, a description such as “instant” cannot accurately mean immediate payment from the moment of request.
A report by filmink.com.au describes PayID withdrawals as almost immediate compared with bank transfers that may take several working days. Read that as a comparison of payment timing, not a guarantee about an operator’s review queue. For any service you encounter, check the terms for when processing time starts, what approval involves and how the operator communicates a pending decision. Only after release does the speed of the payment network become relevant.
Payment methods differ in two separate ways: how quickly a withdrawal is reported to arrive, and whether the method can receive withdrawals at all. A fast deposit option is not necessarily a cash-out option. PayID is one route for bank-to-bank transfers; e-wallets, cards, bank transfers, cryptocurrency and prepaid vouchers follow different arrangements.
| Method | Stated timing or withdrawal availability |
|---|---|
| PayID | A specialist review reported near-immediate transfers, but the payment timing does not describe the entire withdrawal process. |
| E-wallets | A specialist review described transactions as taking hours rather than days. Another specialist account put e-wallet withdrawals within a day, so advertised timing can differ between services and accounts. |
| Traditional bank transfer | A specialist review said completion could take as long as five business days. |
| Cards | A specialist review grouped card payments with bank transfers that may take several days. |
| Cryptocurrency | A specialist review described cryptocurrency transactions as potentially near-instant. |
| Prepaid vouchers | A specialist review said vouchers such as Neosurf were generally offered for deposits, not withdrawals. |
PayID’s reported speed is relevant only to the transfer after funds have been released. It should not be read as a promise that a withdrawal request will reach your bank immediately. E-wallets can also move funds without a conventional bank transfer, but their reported timeframes are not uniform. Check the specific method’s withdrawal terms rather than assuming that a quick deposit indicates a quick payout.
Bank transfers and card payments are often described with longer windows than PayID, although the exact timing depends on the stated service and the payment route. A bank transfer may take several business days; one specialist review gave a maximum of five. That figure is a report about a particular account of the method, not a guarantee for every transfer. Card withdrawals may also take several days, and the card being accepted for deposits does not by itself establish that withdrawals are sent back to it.
While cryptocurrency and PayID are reported as near-instant, the platform's internal release of funds remains a separate and necessary part of the process.
Cryptocurrency may appear faster in descriptions of the payment stage, but “near-instant” is still a qualified claim, not a complete measure of the time from request to receipt. The platform’s own release of funds remains a separate part of the process.
Prepaid vouchers work differently. They may be available to add funds, while the withdrawal must go through another eligible route. If you deposit with a voucher, confirm how any resulting balance can be paid out before relying on that method.
These comparisons concern payment mechanics, not permission to provide or use online casino services in Australia. Real-money online casino games are prohibited for operators under Australian law. Do not treat a payment method’s stated speed or availability as evidence that a service is lawful.
A PayID transfer can move quickly once it is released, but that does not mean every withdrawal request reaches a bank account without delay. A specialist review identifies first-time identity checks, withdrawals above $2,000 and bank processing windows as possible sources of variation. These affect different parts of the process: the operator’s checks can hold a request before release, while a bank’s processing window can affect when a released payment is reflected in the account.
A first withdrawal may involve a request for identity documents or a check of account details. Until the operator completes any required review, the payment has not reached the stage where PayID’s transfer speed matters. If documents are missing, unclear or awaiting assessment, the request can remain pending. Completing verification in advance may reduce friction on later withdrawals, but it does not remove other checks or guarantee a particular completion time.
The amount requested can also affect handling. The specialist review flags withdrawals above $2,000 as a possible reason for delay; that figure should not be treated as a universal threshold applying to every operator. A larger request may be subject to additional scrutiny or manual review under the operator’s terms. Check those terms for any stated review conditions, and do not assume that a request will be released automatically simply because PayID is available.
Bank processing windows are a separate consideration. A payment may be released by the operator while the receiving bank’s own processing affects when it appears in your account. The payment-network stage and the bank’s account display are not the same event, so a delay at this point does not necessarily mean the casino has reopened or continued its review. If the payment remains absent, check its status with the operator and confirm with your bank whether it has received the transfer.
To identify where time is being added, distinguish a pending withdrawal from a payment marked as sent. A pending status points to an outstanding operator step; a sent status means you should check the receiving account and bank processing. Keep any confirmation details, and compare the status with the operator’s stated processing conditions rather than relying on the word “instant” alone.
In Australia, providing real-money online casino games to people in the country is prohibited under the Interactive Gambling Act 2001. The timing distinctions above describe payment mechanics, not an endorsement of those services.
A first withdrawal can be the point at which an operator asks you to verify your identity. A specialist review has reported this as a common first-withdrawal experience, but the request is not automatic in every case. The underlying requirement is clearer: casinos must verify a player’s identity through KYC procedures before processing a withdrawal.
KYC means “know your customer”. Its purpose is to establish that the person requesting the funds is the person associated with the casino account. Until that check is complete, the operator may be unable to approve the withdrawal, regardless of whether PayID can transfer funds in real time after release. The payment method does not replace the identity check.
This is why a claim about an instant withdrawal should not be read as a promise that funds arrive immediately after you submit a request. If verification is still outstanding, the request cannot move through the operator’s approval stage until the check is resolved. Once identity verification has been completed, later withdrawals may involve less friction because the operator has already checked the account holder’s identity. Completing that step early can significantly speed up future withdrawals.
The check may involve information or evidence requested through the operator’s account process. Follow the instructions shown in your account and provide only the material requested through the appropriate channel. If details are missing, unclear or inconsistent, the operator may need to ask for clarification before it can complete the check. Do not assume that submitting a withdrawal request also submits identity evidence.
If a verification request appears, read it carefully and check your account for its status. If the status does not change after you have supplied the requested information, contact the operator through its stated support channel rather than submitting repeated withdrawal requests. Repeated requests do not resolve an identity check that is still pending.
Keep in mind that real-money online casino games, including slots, are prohibited interactive gambling services when provided to customers in Australia under the Interactive Gambling Act 2001. This explanation describes the role of KYC in a withdrawal process; it is not an endorsement of using such services.
A PayID cashout is subject to the operator’s transaction rules as well as the payment method. Check the terms for the minimum and maximum amount allowed per withdrawal before submitting a request. A minimum can make a small balance ineligible for cashout, while a per-transaction maximum can require a larger balance to be withdrawn in separate requests. The applicable limits are set by casino policy; a report on PayID withdrawals by Filmink also notes that withdrawal amounts may be restricted by those rules.
Legal Warning
Under the Interactive Gambling Act 2001, it is prohibited for operators to provide real-money online casino games to people physically located in Australia.
A per-withdrawal maximum is not necessarily the full amount you can take out over a period. Weekly or monthly cashout caps may apply separately, so dividing a large balance into smaller requests might not increase the total you can withdraw within that period. Check whether the terms specify both kinds of limit, how the period is calculated and what happens to an amount that exceeds a cap. Limits may also differ by account or payment conditions, so do not assume that a figure shown for one transaction applies to every withdrawal.
Auto-approval is another distinct condition. A specialist review has reported that some top-tier Australian PayID casinos auto-approve withdrawals below AUD 5,000. Treat that as a description of reported operator policies, not a promise that a particular request will be approved automatically. The operator’s published terms determine whether a transaction qualifies, and approval rules do not remove any required checks. In particular, casinos must disclose a manual review process for withdrawals exceeding AUD 2,000. Read the stated thresholds together: a payment may fall below one auto-approval limit yet still be subject to a review condition.
Approval status and payment speed are not the same thing. An auto-approved request may still be subject to a transaction limit, a periodic cap or a fee. Conversely, a request that exceeds an auto-approval threshold is not necessarily refused; it may require manual handling under the operator’s rules. Check the amount you intend to withdraw against each condition before confirming the request.
Fees need separate attention because a displayed cashout amount may not tell you what will reach the receiving account. Filmink has reported that a fee may apply to PayID withdrawals. Look for the fee amount, when it is charged and whether it is deducted from the withdrawal or added separately. If the terms do not make those points clear, the net amount cannot be worked out reliably from the requested figure alone.
Real-money online casino games are prohibited for operators to provide to people in Australia under the Interactive Gambling Act 2001. The conditions described here do not change that legal position.
A withdrawal can be unavailable even when a balance is visible, because bonus terms may restrict when funds become eligible to cash out. Before attempting to withdraw, check whether any wagering requirement attached to a bonus has been completed. Until it is met, the operator may treat some or all of the balance as restricted rather than withdrawable.
The key distinction is what the wagering requirement applies to. Under a bonus-funds-only condition, wagering is counted against the bonus amount. Under a combined condition, it is counted against the deposit and bonus together. A specialist review identifies both structures and favours bonus-only wagering, because the requirement is calculated on a narrower base. The actual condition depends on the bonus terms, so the label alone is not enough: read the wording that defines the amount subject to wagering.
For instance, a bonus may appear as a separate credit, but its terms can still affect the status of the deposit or the combined balance. Do not assume that withdrawing the deposit first will leave the bonus conditions untouched. Check whether making a withdrawal cancels the bonus, removes related winnings, or changes the amount available. Those effects are determined by the stated terms, not by the payment method selected for the cashout.
Checking Bonus Eligibility
Identify subject funds
Determine which funds are subject to wagering (bonus-only or combined deposit and bonus).
Verify activity
Check what specific activity counts toward completing the wagering requirements.
Review withdrawal consequences
Confirm what happens to the bonus or winnings if you request a withdrawal before completion.
A useful check is to identify three things in the terms: which funds are subject to wagering, what activity counts toward completing it, and what happens if you request a withdrawal before completion. Then compare that wording with the balance shown in your account. If the account displays bonus funds or winnings linked to an active offer, treat the displayed total as distinct from the amount currently eligible for withdrawal until the conditions are satisfied.
This matters for a PayID withdrawal from pokies because the payment method does not determine whether the balance is ready to leave the account. A rapid payment stage cannot make restricted funds eligible; the wagering condition must first be met, and the withdrawal request must comply with the applicable terms. Keep a record of the offer conditions and the account status if they appear inconsistent, and seek clarification through the operator’s stated support channel before submitting a request.
In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically located in the country. This explanation describes how bonus conditions affect withdrawal eligibility; it is not an invitation to use an offshore casino service.
For a PayID payout, the casino needs to be able to connect the withdrawal destination to the account that made the deposit. If you use different PayID details, or request payment to an account that is not linked to your casino profile, the operator may pause the transaction and review the mismatch. That security step can interrupt an otherwise straightforward withdrawal.
Operators generally return funds through the same method used for a deposit where possible. This helps keep the payment trail consistent: the deposit and withdrawal are associated with the same player and payment details. Treating PayID as a separate route for cashing out, even when the identifier belongs to you, may not satisfy the operator’s account checks.
Before requesting a withdrawal, compare the PayID details saved on your casino profile with those used for your deposit. Check that the identifier is accurate and that the receiving account is linked to your profile. If your PayID details have changed since depositing, do not assume the casino can automatically substitute the new details. Check the operator’s instructions and resolve the account information before submitting the request.
A mismatch does not by itself establish that a withdrawal will be refused. It can, however, prompt a security review while the operator checks ownership and account consistency. During that review, the withdrawal may remain pending rather than proceeding to payment. Supplying details that match the deposit and are already linked to the profile reduces the chance of creating this particular issue; it does not remove other operator checks.
Keep the distinction clear between the payment identifier and the casino account. A PayID identifier tells the payment system where to direct funds, while the casino profile identifies the player entitled to request them. Both need to align for the operator to process a withdrawal without having to investigate a discrepancy.
If you are setting up PayID before playing pokies, enter the details carefully and use that same PayID when depositing and withdrawing. When a request form asks for a PayID identifier, check it against the details associated with the deposit rather than relying on memory. If the form does not accept the matching details, contact the operator through its stated support channel instead of entering another person’s identifier or an unlinked account.
This consistency is relevant whether you are seeking an instant withdrawal or simply submitting a standard cashout request. “Instant” does not override account checks: the operator still needs to release the funds to an eligible destination. The practical rule is simple: deposit and withdraw using the same PayID details where possible, and keep the receiving account linked to your casino profile.
Options include credit and debit cards, PayPal and Skrill, bank transfers, and, at some casinos, cryptocurrency. PayID and POLi may also be available for banking payments; prepaid vouchers such as Neosurf are generally for deposits, not withdrawals.
They are casinos that make cashouts relatively quick, for example by supporting PayID and approving withdrawals promptly. PayID can transfer funds in real time once the operator releases them, but the operator’s review may add time. Australian law prohibits online casino operators from offering real-money casino games to people physically located in Australia.
Check which withdrawal methods are available, what timing the payout claim measures, and whether the site clearly publishes withdrawal limits and any fees. Completing identity verification early can help avoid delays, especially on a first withdrawal; also check for per-transaction and weekly or monthly cashout limits.
PayID transfers can arrive in real time after the operator releases the funds, but approval can take longer; some reported cases took up to 24 hours because of internal review. E-wallet withdrawals are typically processed within 24 hours, while bank transfers and card payments may take several days.