PayID can settle between banks in real time, while casino matching, account updates and later withdrawals follow separate processes.
“Instant” describes how a payment moves between participating banks, not how quickly a casino updates an account or approves a later transaction. PayID uses Australia’s New Payments Platform (NPP), which lets people send and receive money through a bank account using an identifier such as a mobile number or email address. The identifier points to the account; it is not itself a separate payment network.
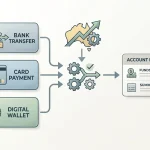
When you make a PayID payment, your banking app sends the instruction through your bank to the NPP. The platform routes it to the receiving bank, which processes the transfer. PayID transactions settle in real time through the NPP. That means the bank-to-bank movement can happen without the batch processing associated with some older payment systems.
The distinction is between settlement and the recipient’s own records. A payment may settle between banks while a separate service still needs to identify it, match it to an account, or update a balance. Those steps are handled outside the payment rail. So “real time” describes the transfer between financial institutions; it is not a general promise that every system connected to a payment will respond at the same moment.
Choosing a casino for instant bank transfers means checking the payment details that are actually available, rather than assuming every option supports the same methods or speeds. Use these brief operator notes as a starting point for your comparison.
Lucky Dreams
Lucky Dreams lists a A$20 minimum deposit via POLi. Its stated licence is Curacao.
DragonSlots Casino
DragonSlots Casino is listed under the Curacao Gaming Authority, with Jumpman Gaming Ltd named as the operator.
Wild Tokyo
Wild Tokyo lists a A$10 minimum deposit and states payout estimates of 30–60 minutes for crypto and 1–5 days for fiat. It also lists a Curacao licence.
MrPacho
MrPacho states payout estimates of 30–120 minutes for crypto and 24–72 hours for fiat, with a A$30 minimum deposit.
LevelUp Casino
LevelUp Casino lists a A$15 minimum deposit. Its Curacao eGaming licence is identified as OGL/2023/174/0082 and names Dama N.V.
Playfina Casino
Playfina Casino lists a Curacao eGaming licence held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino is listed under Curacao eGaming, with Roby Games Ltd named as the operator.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
7Bit Casino
7Bit Casino is listed as operating under a Curacao licence, with Dama N.V. identified as the operator.
Kingmaker
Kingmaker states crypto payout estimates of around 90 minutes and fiat payouts of 1–5 days. Its listed minimum deposit is A$30.
PayID also differs from a conventional bank transfer in the way the recipient is addressed. Instead of entering account details, the sender can use a registered identifier. The banks use that identifier to route the payment to the associated account. You still initiate and authorise the transaction through your banking app, and the transfer remains a bank payment rather than a card transaction or an e-wallet transfer.
The phrase “bank transfer” can refer more broadly to money sent from one bank account to another. It does not, by itself, specify the payment rail or how quickly the transfer will settle. PayID is one way to address and send a bank payment through the NPP; other bank-transfer arrangements may use different processes. Treating the phrases as interchangeable can therefore obscure what matters: which service handles the transfer, how it is addressed, and what happens after the receiving bank gets the funds.
For a real-money casino transaction, the payment rail and the operator’s account system are separate parts of the chain. The rail carries the payment between banks. The operator’s systems, if involved, must then recognise and record it. A fast rail cannot make an operator’s separate processing instantaneous, and it does not establish that the operator is lawful or suitable.
That legal distinction is important in Australia. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies and table games, to people physically located in the country. Payment technology does not change that rule. This explanation describes how PayID and bank transfers work as payment mechanisms; it is not an endorsement or instruction to fund an online casino.
 Paysafecard Casino Sites in Australia: What to CheckLearn how to check whether a casino cashier actually offers Paysafecard, and why common Australian payment habits do not prove acceptance.
 EcoPayz Casino Sites in Australia: What to CheckLearn how to assess EcoPayz payment claims, check withdrawal conditions, and understand why Australian-facing access does not establish legal authorisation.
When you see “instant bank transfer” used to describe PayID, read it as a claim about the underlying payment movement, not as a complete description of every step at the receiving end. The NPP can settle the transfer in real time, while any separate service connected to it operates on its own systems and timing.
For a payment to be credited automatically, three records need to line up: the payment sent from the bank, the deposit details held by the casino, and the player account that should receive the funds. PayID can move money between bank accounts quickly, but the transfer itself does not necessarily identify which casino account should receive the credit. That link is commonly made through a payment reference.
Real-money online casino services, including pokies, are prohibited for operators to provide to people physically located in Australia under the Interactive Gambling Act 2001. The process below describes how payment references and account crediting work; it is not a recommendation to deposit with an offshore casino.
A payment reference is text attached to a transfer. It lets the recipient match incoming money with a particular deposit record or player account. A casino may specify that the reference must contain your player ID or username. If that identifier is absent or entered incorrectly, the bank transfer can still reach the recipient, but the recipient’s system may not be able to assign it automatically.
Attention: If the required payment reference is absent or entered incorrectly, the recipient's system may be unable to assign the transfer to your account automatically.
This distinction matters: payment settlement and account crediting are separate events. The bank confirms that money has been sent and received through the payment rail. The casino must then associate that incoming payment with the correct account. A successful bank transfer therefore does not, by itself, prove that the corresponding casino balance has been updated.
Some systems may match payments using other information, but you should not assume that a name, email address, or payment amount will substitute for the reference the recipient requests. Automated matching depends on the recipient’s own rules. If the reference is required, use of a different identifier can leave the payment unmatched even when the amount is correct.
A deposit request normally creates a record on the receiving service before the money arrives. That record may contain an amount and an account identifier; the incoming transfer is then checked against it. If the amount differs from what was entered, or the reference does not point to the right account, an automated match may fail. The payment can remain pending while the recipient investigates and processes it manually.
PayID deposit minimums vary by service. Reported starting amounts commonly fall between AUD 10 and AUD 20, while some bank-transfer options accept AUD 5. These figures are not universal rules: the amount a service displays is specific to that service and can change. More importantly, meeting a displayed minimum does not resolve a missing or incorrect reference.
 Trustly casino sites in Australia: what is verifiedNo Australian online pokies site is confirmed as accepting Trustly; learn why brand claims and payment logos do not prove cashier availability.
 Apple Pay Casinos in Australia: What Acceptance MeansLearn why Apple Pay working in shops does not confirm casino acceptance, and why an instant deposit does not establish an instant…
A pending deposit does not necessarily mean the bank has rejected the transfer. It can mean the recipient has received money but cannot confidently link it to the deposit record. A missing player ID or username is one reason this can happen. A mistyped identifier can create the same problem, because the payment may point to no account or to an account other than the intended one.
Manual processing requires the recipient to investigate the unmatched payment. That is why a transfer that has settled can still take longer to appear as a balance. Sending another payment before the first one is resolved may create a second transaction to reconcile rather than fixing the original mismatch.
In a lawful payment context, the useful distinction is between a transfer’s status at the bank and its status in the recipient’s account system. A bank confirmation concerns the movement of funds; a credited balance depends on successful matching by the recipient. In Australia, do not use this process to fund real-money online casino games: operators are prohibited from providing those services to people in the country.
A bank transfer is a way to move money from your bank account to a payment recipient; it is not a feature of the pokies themselves. In a gambling service, the operator would need to match the incoming payment to a player account before showing the funds as available. That distinction matters: a transfer can leave your bank account without becoming usable funds in a gaming account, and the payment method does not determine whether the service may legally be offered.
Legal Restriction
Under the Interactive Gambling Act 2001, it is prohibited for operators to provide real-money online casino games, including pokies, to people physically located in Australia.
In Australia, real-money online casino-style games, including pokies, are prohibited services when offered to people physically in the country. The Interactive Gambling Act 2001 places the restriction on operators providing those games, rather than making the payment rail a way around it. A bank transfer does not change the legal status of the underlying activity.
In a payment flow, the bank handles the instruction to send money, while the recipient or its payment processor handles identifying and allocating it. The bank’s confirmation shows that the payment was authorised or processed on the banking side; it does not by itself establish that a gaming account has been credited. The recipient must be able to associate the payment with the relevant account and make it available in its own records.
That separation also explains why “bank transfer” can refer to different experiences. A PayID payment is initiated through a banking app using an identifier, with the New Payments Platform carrying the payment. A conventional bank wire uses bank-account details and follows a different process. They are not interchangeable labels for one identical service. For a person comparing payment options, the relevant distinction is how the payment is sent and what the receiving service can process—not the type of game that might later appear on screen.
A bank payment also does not make a service safer or lawful by itself. The fact that a recipient can accept money is not proof of its status, or that a player will be able to use or retrieve funds as expected. Payment acceptance and permission to offer real-money pokies are separate questions.
 Amex Casino Deposits in Australia: What to CheckAmex is available at some Australian-facing casinos, not universally. Learn how deposits, fees, limits and withdrawal rules can differ.
 Casinos That Accept Visa in Australia: Payment GuideSee what the available evidence says about Visa acceptance, card deposits, withdrawals and bonuses, and why broad comparisons cannot confirm an operator's…
POLi is primarily a deposit route. Its presence among payment options should not be taken as evidence that it can also be used to withdraw money. That limitation is important when comparing methods: a route that can move money into an account may not provide a matching route out. The name of a deposit option alone does not tell you what happens to later transactions.
Cards have a different set of constraints. Visa and Mastercard are widely accepted for deposits, but a card deposit does not guarantee that a withdrawal can return to the same card. A specialist review describes card cash-outs as potentially slower or unavailable, depending on the payment processor. The processor’s support therefore matters; the card brand on the deposit screen is not enough to predict how funds can be returned.
These differences are practical rather than cosmetic. Bank payments, card payments and POLi do not necessarily share the same processing path or support the same transaction directions. If you are assessing a payment arrangement in a lawful context, distinguish three things: whether a method can send money, whether the recipient can identify and allocate it, and whether that method supports money being returned. Treating a deposit logo as proof of all three can lead to a mistaken assumption.
Searches for bank-transfer pokies often combine two separate issues: whether a payment route can move money and whether a real-money pokies service can be offered to someone in Australia. The payment question can be answered by examining the method and the recipient’s process. It cannot answer the legal question. In Australia, operators must not provide real-money online casino games to people located here, so a bank transfer does not turn a prohibited offering into a permitted one.
Acceptance of a payment method describes a technical capability and is not an endorsement, a guarantee of credit, or evidence that a service is lawfully available in Australia.
The same separation applies to terms such as “online casino that accepts bank transfer.” Acceptance describes a payment capability, not an endorsement or a guarantee. It does not establish that a service is available lawfully in Australia, that a deposit will be credited, or that an alternative method will be available later. When comparing payment methods in a lawful setting, read each method as a limited function, rather than assuming it covers the whole path from payment to use and back again.
A payment logo or “bank transfer” label does not establish that a casino can lawfully offer its games to you in Australia. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games, including pokies, to people physically located in Australia. A foreign licence does not change that restriction. The practical distinction is important: a site may display bank transfer as an available payment method, but that does not make its casino service lawful to provide in Australia. Do not treat payment access as evidence that an operator is authorised.
If you encounter a claim that a casino accepts bank transfers, first separate the claim into two parts: whether the payment method is technically listed, and whether the operator is legally permitted to provide the service to Australian residents. The first can be checked on the site’s payment page or in its account cashier; it cannot answer the second. A casino that accepts bank transfer may describe PayID, a bank payment, or a conventional wire under similar labels, although these are not necessarily the same process. Read the method’s own description rather than assuming that “bank transfer” means an immediate payment or that every transfer option supports both deposits and withdrawals.
The legal check comes before comparing payment features. Look for the operator’s stated licence issuer and verify that the licence details match the named business through the relevant regulator’s records. A foreign licence is not an Australian authorisation to provide online casino games to people in Australia. If the site does not identify an issuer or its details cannot be matched, its claim is not independently substantiated. Even a verifiable foreign licence does not remove the Australian restriction. Do not use a site’s licence badge, payment page or customer-service statement as a substitute for this distinction.
Payout claims need similarly careful reading. A published payout record can tell you what the operator says it has paid, but a payment-method logo or a successful deposit does not establish that withdrawals will be honoured. Check whether the information explains what counts as a completed payout, whether it distinguishes the operator’s approval from the bank’s processing, and whether the records are attributable to the operator rather than presented as general claims. Treat unsupported guarantees or unclear explanations as reasons not to rely on the claim. This is a way to assess the reliability of information, not a recommendation to use an offshore casino.
Payment availability still matters when assessing what a site is claiming. A cashier may list Bank Transfer for deposits but provide a different set of methods for withdrawals. It may also distinguish PayID from a bank wire, or state that a method is unavailable for some accounts. Read the terms attached to the specific method and check the cashier’s current options rather than relying on an old page or a general banner. POLi, for instance, should not be assumed to support withdrawals simply because it appears among deposit options. Visa and Mastercard may be offered for deposits, while card withdrawals can be slower or unavailable depending on the processor. These distinctions explain why a payment list alone is not a complete account of how money can move.
For a lawful service that offers bank payments, the relevant checks would include whether the method is available in your account, what transaction limits apply, and whether the terms identify any conditions attached to it. Limits for a bank transfer may be set differently from those for PayID, and a specialist review has reported that some transfer limits can reach tens of thousands of dollars; that figure is not a general guarantee or a reliable expectation for any particular operator. The cashier and the operator’s terms would need to state the applicable limit. Do not infer a limit from a review, a payment logo or another customer’s experience.
The same caution applies to mobile access. A payment page that works on a phone only confirms that the page is accessible there; it does not establish that an operator is authorised to provide online casino games in Australia or that the payment method will work for every account. Do not enter banking credentials or send funds merely to test whether a payment option functions. A successful transaction would confirm only that a payment was processed, not that the underlying service is lawful or that future payments will be returned.
There is no meaningful “best” or “top” bank-transfer casino for Australians to select on the basis of a payment method. A comparison of operators would risk presenting prohibited online casino services as options. For evaluating a claim, keep the checks separate: identify exactly which transfer method is named, confirm what the operator says it supports, scrutinise any payout record, and distinguish a foreign licence from permission to serve customers in Australia. If the operator is offering real-money online casino games to people in Australia, payment convenience does not make that offer permissible.
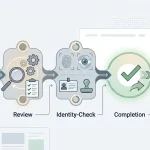
A bank-transfer withdrawal depends on two things being in place: the casino must be able to match your request to your account, and it must have enough information to send the funds to your bank. Before requesting a payout, complete KYC verification and check that the bank account details on file are accurate. This is particularly useful before a first withdrawal, when the operator may need to review documents before accepting the request.
The casino may ask for your bank details, along with documents that confirm your identity. The information must be consistent: a mismatch between the name on your casino account and the bank account can prompt questions or further checks. Submit clear, current documents through the operator’s stated verification process, and check that every requested field is complete before sending the withdrawal request.
Identity checks are commonly part of the first-payout process, according to specialist casino reviews. Completing them ahead of time can reduce the chance that the request is held while the operator asks for paperwork. If a document is rejected or the casino requests additional information, resolve that request before submitting another payout instruction; otherwise, the account may still be unverified when the new request is assessed.
Some operators apply a same-method rule: where possible, they may require you to withdraw through the method used to deposit. This condition can affect whether a bank-transfer withdrawal is available, even when the casino accepts bank transfers for payouts. A specialist review describes this as an operator policy rather than a universal rule, so read the payment terms for the specific account and check what happens if your deposit method cannot receive withdrawals.
Do not assume that a method shown on the cashier page is automatically available for every transaction. Deposit and withdrawal options can differ. Confirm that bank transfer is selectable for payouts, whether the operator expects you to use the original deposit route, and whether it asks you to nominate or verify a particular bank account. If the rule is unclear, ask support to explain how it applies to your account before you submit a request.
A casino may set a minimum or maximum for each withdrawal, and the limits may differ by payment method. One specialist review gives a reported PayID withdrawal range of AUD 20–50 for minimums and AUD 5,000–10,000 per transaction for maximums. Treat those figures as that review’s reported terms, not as a fixed market standard: the amount available to you depends on the operator’s current cashier rules and account conditions.
Check the limit shown for your chosen method before entering an amount. If your requested sum exceeds a per-transaction cap, the cashier may not accept it as entered; if it falls below a minimum, you may need to change the amount or select another eligible method. Confirm the receiving account details and method selection before submitting, then keep the request confirmation so you can refer to the exact transaction if the operator asks for clarification.
A payout has two separate stages: the casino’s review and the payment network’s delivery. The time shown for the whole process can include both, so a fast transfer rail does not mean the money is sent as soon as you submit a withdrawal request.
The first stage is controlled by the operator. It checks the request and decides whether to approve it. A specialist review of PayID casinos reports that, for verified accounts at top-rated operators, this review and approval may take between two and six hours. Treat that as a reported range, not a guaranteed service level: the operator’s procedures and the status of your account affect when a request is cleared.
For PayID payouts, the main bottleneck is often this internal processing rather than the network. PayID uses the New Payments Platform, where transfers can settle in real time once released. In other words, a request can wait in the casino’s queue even though the payment rail itself can move the approved funds quickly. If a payout remains pending, the relevant status is whether it has been approved and sent—not simply whether PayID is available.
Settles in real time via the NPP once approved, often arriving within minutes to hours.
Conventional transfers are reported to take between one and five business days.
Reported timing is generally one to five business days, depending on the processor.
The second stage begins after approval. A specialist review reports that PayID withdrawals and some e-wallet or cryptocurrency withdrawals may arrive within minutes to hours after approval. By comparison, bank-transfer and card withdrawals are reported as taking one to five business days. These are reported timing ranges, not a promise for every transaction; the method used and the receiving bank can affect when funds become available.
This distinction also explains why two withdrawals submitted at the same time may arrive at different times. One may be approved sooner, or the approved payments may use different delivery methods. Compare the operator’s stated processing time with the estimated delivery time after approval, rather than treating them as a single measure of speed.
KYC verification can affect the first stage. If the casino still needs documents or clarification before it can clear a request, the review cannot be treated as complete. Having verification finished before submitting a withdrawal removes that particular source of paperwork delay; it does not control the operator’s queue or guarantee a faster payment.
When checking a stated payout time, look for the event that starts the clock: request submission, approval, or dispatch. A figure measured from approval says nothing about how long the casino may take to review the request. Keep records of the request and its status so you can distinguish a pending review from a transfer that has already been released.
Australian law prohibits operators from providing real-money online casino games to people physically in Australia. The timing information above describes payment stages; it is not a recommendation to use such a service.
Australian law prohibits operators from providing real-money online casino games to people physically in Australia. The bonus wording does not change that. If you encounter an offer described as a bank-transfer deposit bonus or a no-deposit bonus, treat its terms as conditions attached to the offer, not as evidence that the service is lawful or available to you.
A bank transfer is only a way to move funds. It does not determine how a bonus is calculated, which games count towards its conditions, or whether a balance can be withdrawn. Read the complete terms before making any payment; a headline offer may leave out restrictions that affect the bonus or funds associated with it.
A no-deposit label does not mean there are no conditions. The terms may still specify wagering, eligible games, time limits, maximum bets, or a cash-out cap. Read those conditions as carefully as you would for an offer tied to a deposit by bank transfer.
Also check how the terms define eligibility and whether accepting an offer changes the status of other funds in the account. If a condition is unclear, do not infer the operator’s interpretation from the promotional wording. The operative terms determine how the offer is handled, and a payment method cannot override them.
A conventional bank wire is a bank-to-bank payment, not a PayID transfer. It uses the recipient’s account details and may pass through additional banking steps, so it does not have the same real-time settlement path as a PayID payment.
For a wire, the sender needs the recipient’s business name, bank name and account number. Depending on the transfer route, the bank may also ask for a SWIFT, BIC or IBAN code. The payment can be arranged at a bank branch, by phone, or online from a computer or mobile device. Before authorising any transfer, check the recipient details against a trusted record; a mistyped account number or code can direct the money elsewhere.
Timing is a separate issue from entering the payment correctly. A wire deposit may take as long as seven business days to appear in a casino account. The bank’s handling and the recipient’s processing both affect when the balance is updated, so a submitted transfer should not be treated as immediately available funds. Keep the bank’s confirmation and the payment details in case the recipient cannot match the transfer.
Charges may also apply. A bank wire can cost more than other non-banking payment methods, and the exact fee depends on the banks and transfer route involved. Check the charges shown by your bank before confirming; do not assume the recipient will cover them.
There is an important legal limit in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in the country. A direct bank transfer does not change that status. The mechanics above describe how bank wires work generally, not an endorsement or recommendation to fund an online casino account from Australia.
PayID and other bank transfers do not share one universal transaction ceiling. Your bank sets your PayID limits, so the amount permitted can differ between customers and institutions. Most major Australian banks allow PayID payments of AUD 1,000–5,000 per transaction, with daily limits of AUD 10,000–20,000. Your own banking app or bank can confirm the limit that applies to your account.
A conventional bank transfer may have a higher available ceiling, but the operator can also set its own transaction limits. Specialist reviews have reported limits reaching tens of thousands of dollars for some bank transfers; treat that as an operator-specific possibility, not a standard available everywhere. Check the applicable terms before relying on a particular limit.
Currency affects the amount ultimately credited. If your bank account and the receiving account use different currencies, a conversion may be applied, potentially adding foreign-exchange costs. Keeping both accounts in the same currency may reduce those costs, but the conversion method and any charges depend on the banks and service involved. Compare the currency shown for the transaction with the currency debited from your account rather than assuming they match.
These distinctions describe payment mechanics, not permission to use an online casino. Under Australia’s Interactive Gambling Act 2001, providing real-money online casino games to people physically in Australia is illegal.
Yes, some casinos offer PayID withdrawals. Availability and withdrawal limits vary by operator.
PayID withdrawals may arrive within minutes to hours after approval. At top-rated PayID casinos, verified withdrawal requests are typically reviewed and approved within 2–6 hours.
PayID casino deposits commonly start at AUD 10–20. The minimum depends on the service.
PayID deposits typically reach the recipient within 3–15 seconds. The casino may take additional time to match the payment to your account.