Withdrawal timing depends on both the casino’s handling of a request and the payment route after funds are released.
A claim that a withdrawal takes under an hour can describe only part of the journey. The time from submitting a request to seeing money in your account includes at least two separate stages: the operator’s handling of the request and the payment’s movement after release. A fast payment network can shorten the second stage. It cannot, by itself, make the first stage instant.
That distinction matters when you assess a statement about an under-an-hour withdrawal. The clock might start when you confirm the request, when the operator approves it, or when the operator sends the funds. Those start points produce different elapsed times. A statement that does not identify its start and end points is incomplete: it may refer to a quick transfer after approval while leaving the approval period outside the advertised time.
For a withdrawal to reach you, the request must first be accepted and authorised for payment. The operator then releases the funds through the selected payment route. After that, the receiving bank or payment system records the incoming transfer and makes it available to you. These events are connected, but they are not the same event. In particular, a transfer system cannot deliver funds that the operator has not yet released.
If you need a casino withdrawal to arrive in under an hour, check the stated payout times and payment-method details carefully before choosing. This list gives you a concise reference to the withdrawal information available for each operator.
Lucky Dreams
Lucky Dreams accepts POLi deposits from A$20. Its listed license is Curacao.
DragonSlots Casino
DragonSlots Casino is listed under the Curacao Gaming Authority, with Jumpman Gaming Ltd as the named operator.
Wild Tokyo
Wild Tokyo lists crypto payouts at 30–60 minutes, while fiat payouts take 1–5 days. The minimum deposit is A$10.
MrPacho
MrPacho lists crypto payouts at 30–120 minutes and fiat payouts at 24–72 hours. Its minimum deposit is A$30.
LevelUp Casino
LevelUp Casino lists a Curacao eGaming license, OGL/2023/174/0082, held by Dama N.V. Its minimum deposit is A$15.
Playfina Casino
Playfina Casino is listed as licensed by Curacao eGaming, with Hollycorn N.V. named as the licensee since 2017. The minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino is listed under Curacao eGaming, with Roby Games Ltd as the named licensee.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board license, OGL/2023/176/0095, held by Hollycorn N.V.
7Bit Casino
7Bit Casino is listed as operating under a Curacao license, with Dama N.V. named as the operator.
Kingmaker
Kingmaker lists crypto payouts at approximately 90 minutes and fiat payouts at 1–5 days. Its minimum deposit is A$30.
Think of the process as a sequence, rather than a single transaction with one universal timer.
The first interval begins when you submit a withdrawal request. It ends when the operator has completed its review and decided whether to approve the payment. During this interval, the request is waiting on the operator’s side. A payment network does not control that queue and cannot decide whether the request satisfies the operator’s requirements.
The next interval begins when the operator releases the approved funds. It ends when the payment reaches the receiving account or is otherwise shown as received. This is the part where the payment method and the banks or systems involved affect delivery. PayID is designed to move funds between bank accounts in real time through Australia’s New Payments Platform (NPP), with transfers processed through the Osko network. That capability applies to the transfer stage; it does not determine how quickly an operator approves a withdrawal.
The distinction is similar to the difference between authorising a parcel for dispatch and delivering it. A delivery network may move a parcel quickly once it has been handed over, but it cannot reduce the time spent waiting for the sender to prepare and release it. With a withdrawal, the operator’s approval is the handover point. Before that point, the payment is still under the operator’s control.
A third interval can matter in practice: the time between the operator marking a payment as released and your bank displaying it as available. The exact way a transaction appears can depend on how the operator sends it and how the receiving account records it. A status such as “approved” therefore does not necessarily mean the money has arrived. Nor does a status such as “sent” prove that you can already use the funds. The wording of the status matters because each label can refer to a different step.
When you compare a stated time with what happened to your own request, identify the event that started the clock and the event that stopped it. If the clock started at approval, the operator’s review time has been excluded. If it stopped when the operator sent the funds, the receiving-side delivery time has been excluded. Only a measure that covers the period from your request to receipt represents the full request-to-receipt journey.
PayID is Australia’s bank-to-bank instant payment system, operating on the NPP. Its real-time transfer capability is relevant once a payment has been released into that system. At that stage, the payment can move between bank accounts without the same kind of delay associated with a slower transfer route. The practical point is not that every withdrawal request is immediate; it is that the transfer stage can be rapid after the operator sends the money.
PayID's real-time transfer capability applies only to the transfer stage; it does not determine how quickly an operator approves a withdrawal request.
The order of events is decisive. Suppose you submit a request and the operator holds it for review. Even if PayID can carry the funds in real time, there are no funds in transit through PayID while the request remains unapproved. Once the operator approves and releases the withdrawal, the payment network can perform its part. The elapsed time before release still belongs to the overall withdrawal, even though the payment network did not cause it.
This is why “instant withdrawal” can be an imprecise label. It might describe the transfer after release, rather than the whole process from clicking the withdrawal control to receiving usable funds. A specialist review has reported cases in which sites used “instant” wording while internal review meant that a payment could still take as long as 24 hours. That report illustrates the difference between a fast payment rail and an operator’s internal handling. It should not be read as a timetable for every site or every request.
A separate specialist review describes PayID funds as moving instantly after the operator releases them. Read that statement with its condition intact: “after release” is not a minor qualification. It marks the boundary between the operator’s work and the payment network’s work. Remove it, and a statement about the transfer stage can be mistaken for a guarantee about the entire withdrawal.
For the same reason, a displayed estimate should specify what it measures. “Processed” may mean the operator has reviewed the request, approved it, or sent it onward; the word alone does not tell you which. “Paid” may also refer to an operator status rather than confirmation that the receiving account has credited the money. If an estimate does not define its endpoints, you cannot safely compare it with another estimate that uses different endpoints.
A claim of completion within an hour is meaningful only when it describes a defined interval. The useful distinction is between:
These intervals can overlap in how a platform reports them, so do not assume that a label corresponds to a particular stage. Look for the event that changes the request’s status and ask what that status means. If the operator says “approved,” that establishes a decision; it does not, by itself, establish that payment has been sent. If it says “released” or “sent,” that indicates the operator has handed the payment off, but it may still not confirm receipt.
The full request-to-receipt measure is the clearest interpretation for a player who wants to know when funds will be available. A sub-hour figure that measures only release-to-receipt can still describe a fast transfer, but it does not answer how long the entire withdrawal will take. Both measures can be accurate at the same time because they describe different parts of the process.
This also explains why an individual withdrawal may not match a broad claim. The payment network may be capable of real-time transfers, while the operator’s handling time varies. A request that is approved and released promptly can make good use of the network’s speed. A request that remains under review for longer cannot. The payment method has not become slower in the latter case; the request simply has not reached the stage at which the payment method can act.
The same logic applies when an operator uses the word “instant.” Treat it as a description of a particular operation, not as a complete timetable, unless the terms clearly define it as request-to-receipt. In the PayID context, the technically relevant operation is the transfer after release. The operator still controls when the request is reviewed and when the funds are sent.
“Real time” describes the payment system’s transfer capability. It does not mean that every instruction is sent as soon as you submit a request, or that every institution presents the result in precisely the same way. The operator must first create and release the payment instruction. Only then can the transfer system handle it.
There is therefore a difference between a system being able to transfer funds in real time and a withdrawal being completed in real time. The first is a property of the payment route. The second is a claim about the whole workflow, which includes decisions and actions outside that route. Conflating them makes the advertised speed sound broader than the mechanism supports.
The word “instant” can also hide a question of timing convention. One platform might count from the moment a payment is sent; another might count from the time you first request it. A report of an almost immediate transfer after approval may be accurate for the post-release stage while still saying nothing about the time spent waiting for approval. Before treating a speed statement as a practical estimate, check whether it refers to the payment instruction or the original request.
PayID’s role is narrower and more precise: it provides a way to identify the receiving bank account and move a payment through Australia’s real-time payment infrastructure. It does not approve the withdrawal, inspect the account, or determine the operator’s release schedule. Those tasks sit elsewhere in the process. Understanding this division lets you diagnose where elapsed time occurred rather than assuming that any delay must have come from the bank.
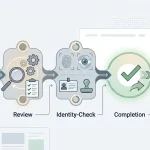
A useful status sequence, when an operator provides one, separates “requested,” “under review,” “approved,” “sent,” and “received.” Not every service uses those exact labels, and a status display may combine stages. The important point is to interpret each label by the action it represents. A request that has not moved beyond review is not yet a payment travelling through PayID. A request marked as sent has passed the operator’s release point, but the account record is the evidence that funds have arrived.
If an estimate is stated as under an hour, first determine whether the period starts when you submit the request or when the operator approves it. Then determine whether the endpoint is the operator’s release confirmation or the funds appearing in your account. These questions establish whether the figure describes the whole journey or only a segment.
Assessing an Estimate
Determine the start point
Check if the period begins when you submit the request or when the operator approves it.
Determine the end point
Check if the endpoint is the operator's release confirmation or the funds appearing in your account.
Identify the journey segment
Establish if the figure describes the whole request-to-receipt journey or only a specific segment, such as release-to-receipt.
For instance, an operator could describe its payment transfer as taking less than an hour after release. That statement would not tell you how long the earlier approval stage might take. Conversely, a stated request-to-receipt time would include both the operator’s handling and the payment stage, provided the estimate is genuinely measured from submission through to receipt. The same number of minutes can therefore represent very different service claims depending on where its clock begins and ends.
If the wording is unclear, do not infer that “fast,” “instant,” or “under an hour” necessarily means request-to-receipt. Those words describe speed but do not identify the measured interval. A careful interpretation keeps the steps separate: first the operator accepts and approves the request; then it releases the payment; then the payment route carries it to the receiving account. A claim about the last step cannot establish the duration of the first.
For PayID, the key technical point is that the transfer stage can operate in real time once funds are released into the system. That is why PayID can support a short delivery interval. The full withdrawal still depends on when the operator reaches that release point. A fast rail changes what happens after handover; it does not remove the handover process.
So, when you see a sub-hour figure, read it as a measured interval rather than a general promise. Find its starting event, its ending event, and the status that confirms each one. If the figure covers only the period after approval, it is a payment-speed statement. If it covers the request through receipt, it describes the entire withdrawal path. Keeping those meanings separate is the only way to understand what an under-an-hour claim actually says.
The payment method determines how quickly money can move after a withdrawal has been approved and released. It does not, by itself, determine how long the full request takes: each route has its own transfer stage, and the operator’s approval still comes first.
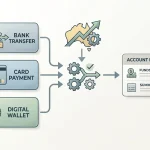
For Australians comparing payment routes, the main options described in specialist reviews include PayID, e-wallets such as PayPal and Skrill, bank transfers, cards and, at some operators, cryptocurrency. These descriptions concern payment mechanics, not an endorsement or an assurance that a real-money casino service is available or lawful to provide in Australia. The Interactive Gambling Act 2001 prohibits operators from providing online casino games to people physically located in the country.
PayID is a bank-to-bank payment method that operates through Australia’s New Payments Platform. Transfers can move in real time, so once an operator releases a withdrawal to the correct PayID, the payment leg need not wait for the same kind of bank processing window associated with a traditional transfer.
That distinction is important when comparing claims of an instant withdrawal. “Instant” can describe the movement of funds after release; it does not mean the whole sequence, from submitting a request to receiving money, is necessarily immediate. An operator may still need to approve the request before the transfer starts. PayID therefore has the clearest potential for a sub-hour payment phase, but the method alone cannot establish that the entire process will finish within an hour.
Attention While PayID has the potential for a sub-hour payment phase, the method alone cannot guarantee that the entire process will finish within an hour.
PayPal and Skrill receive funds into an e-wallet account rather than sending them directly to your bank account. E-wallet withdrawals are described as being processed within 24 hours, while a specialist review reports that e-wallet transactions can be completed within hours rather than days. These are reported timeframes, not a fixed delivery promise: the actual time depends on the operator’s release and the wallet transaction.
The extra account can also affect how you use the money. A payment reaching your wallet is not the same as the money reaching your bank; moving it onward may involve another transfer. When comparing options, check which destination the quoted withdrawal time refers to.
A traditional bank transfer can involve more waiting after the operator releases funds. A specialist review reports that such transfers may take as long as five business days. Another general comparison places bank transfers and card payments in the “several days” category, rather than alongside faster routes.
Cards are a familiar deposit method, but that does not make them equally quick for withdrawals. Credit and debit cards are among the payment methods described for Australian players, yet card payouts may take several days. The processing time depends on the route used to return funds and the institutions involved; a quick deposit does not establish a quick withdrawal.
 Online Pokies Instant Withdrawals in AustraliaLearn how approval differs from the payment transfer, how PayID and other methods compare, and why a fast transfer can still follow…
 Apple Pay Casinos in Australia: What Acceptance MeansLearn why Apple Pay working in shops does not confirm casino acceptance, and why an instant deposit does not establish an instant…
A specialist review describes cryptocurrency transactions as capable of near-instant movement. That refers to the payment network, not necessarily to the time from withdrawal request to receipt. The operator must still release the funds, and the recipient must be able to access them through the relevant wallet. A quoted fast transfer should therefore be read as a description of the payment leg, not a guarantee about the complete withdrawal.
Cryptocurrency is not offered by every operator, and its availability does not make it interchangeable with a bank deposit. Consider whether you can receive and use the asset, as well as how the operator defines its stated processing time.
| Method | What may make it faster or slower |
|---|---|
| PayID | Real-time bank-to-bank transfer after release; the operator’s approval remains separate. |
| E-wallet | Specialist reviews report completion within hours rather than days, but onward movement to a bank is a separate step. |
| Bank transfer | A specialist review reports completion can take up to five business days. |
| Card | Card payments may take several days. |
| Cryptocurrency | A specialist review describes near-instant transactions, but that does not cover the full request-to-receipt process. |
For a withdrawal intended to arrive within an hour, PayID has a real-time transfer mechanism that can support that pace after release. E-wallets may also move faster than traditional bank transfers, but the reported timeframes do not establish a guaranteed sub-hour result. Bank transfers and cards are less suited to a strict short deadline, while cryptocurrency timing depends on more than the network alone. Compare the stated payment phase, not just a label such as “instant.”
For people in Australia, the first check is not a payout speed: it is whether the service can legally be offered. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. That includes slots, poker and table games such as blackjack and roulette.
A claim of payment within an hour is useful only if the terms make clear what the clock measures. Look for separate timings for the operator’s approval of a withdrawal and the payment provider’s transfer after release. If a page says only “instant” or “fast”, it does not tell you whether the request is reviewed first, when the stated time begins, or when funds should arrive. A precise policy should distinguish those stages rather than imply that submitting a request guarantees receipt within an hour.
Legal Restriction
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia.
Read the minimum and maximum withdrawal amounts for the specific payment method, not just a general cashout limit. A specialist review has reported that some Australian PayID casinos publish these limits clearly; treat that as a reported feature to verify in the operator’s current terms, not an assurance that every service does so. Casino policy can restrict the amount you can withdraw, and the rules may differ by method.
Check whether the maximum applies to one transaction or to total withdrawals across a period. A weekly or monthly cashout cap can apply separately from a per-transaction maximum. That distinction matters: a request might fit the individual transaction limit yet still be affected by a broader cap. Also check whether the minimum means that a small balance cannot be withdrawn through the method you selected.
The amount can affect the claimed processing route as well. A specialist review has described automatic approval for PayID withdrawals below AUD 5,000 at some top-tier casinos. This is a report about certain operators, not a general rule. Confirm whether the operator’s own terms specify an automatic-approval threshold, what happens above it, and whether the threshold applies to a single request or a combined balance. Do not assume that a stated threshold removes other checks.
The operator controls when it releases the funds. A fast payment network cannot complete the transfer before that release, so the key question is whether the terms describe approval as automatic, subject to review, or dependent on conditions. Look for the stated processing window, the events that start it, and any exceptions. If the policy does not explain those points, the advertised time is difficult to assess.
A specialist review has reported PayID withdrawals below five minutes at some leading Australian casinos, while giving one to three business days as a comparison for standard bank transfers. Those figures describe that review’s findings, not a guaranteed or market-wide service level. Use them as a reason to inspect the current operator’s own policy, not as proof that an individual request will meet a sub-hour target.
Some leading Australian casinos have reported PayID withdrawals below five minutes, compared to one to three business days for standard bank transfers.
Check for a manual-review threshold and whether it changes the expected approval time. The terms should say whether a request above the threshold is reviewed manually and how that affects processing. If the policy says only that extra checks may occur, without explaining their effect on timing, it does not establish that every eligible request will be completed within an hour. Look for wording that separates an estimate from a guarantee.
A short processing estimate does not reveal the amount you will receive. Review the withdrawal-fee schedule and check whether a fee applies to PayID. A report by FilmInk (filmink.com.au) notes that a transaction fee may apply when withdrawing through PayID. That is a possibility to verify against the current terms; do not assume either that every PayID withdrawal incurs a charge or that the method is free.
Compare the fee information with the limits and timing rules. A stated maximum may be reduced by a fee, while a periodic cashout cap may affect how much can be sent in total. The terms should make these conditions understandable before a withdrawal is submitted. If fees, limits or processing times are absent or inconsistent across the payment page and the terms, the sub-hour claim lacks the published detail needed to assess it.
A useful check is to trace the claim through the operator’s written rules: eligible method, permitted amount, approval route, any manual-review threshold, fee, and the point at which the timing period begins. Then distinguish what the operator promises from what a third-party review reports. A review can describe a particular observed result; it cannot replace current terms or establish the outcome of a future transaction. If the terms do not define the relevant stages and conditions, “within an hour” is not a sufficiently specific measure of the complete withdrawal process.
A payment method can move money quickly once a casino releases it, but that does not mean every withdrawal request reaches that point without checks. The operator may need to confirm your identity, establish that the balance is eligible for withdrawal, and verify that the payment details match the account. If any of those steps is unresolved, the request can remain pending before the payment network receives it.
For people physically located in Australia, it is also important to understand the legal setting: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to customers in Australia. The process below describes how withdrawal checks can work; it is not an endorsement or recommendation to use an online casino.
A first withdrawal can prompt a request for identity documents. This is a know-your-customer (KYC) check: the operator needs to confirm who owns the account before authorising a payment. A specialist review identifies first-time KYC as a possible cause of delay, but the timing depends on whether verification is needed and whether the submitted material can be assessed.
Identity verification (KYC) is a common cause of delay for first-time withdrawals, as the payment network cannot act until the operator approves the request.
The request may pause while documents are submitted and reviewed. If an image is unclear, details do not match, or the operator asks for further information, the check may take longer. The payment method does not remove this step: a transfer system can only act after the operator has approved and released the withdrawal.
Completing verification before requesting a withdrawal can reduce this source of delay on a later transaction. Check that the account information is accurate and that any requested documents are readable and current. If a review is already underway, submitting duplicate or inconsistent information may make it harder to resolve; follow the operator’s instructions and use its stated support channel to clarify what remains outstanding.
A displayed balance is not necessarily all available for withdrawal. If you accepted a bonus, its terms may require wagering before some or all of the funds become withdrawable. Requirements can apply to bonus funds alone or to the combined deposit and bonus; the bonus-funds-only structure is preferable because it does not make the deposit part of the wagering calculation.
Before submitting a request, check whether the relevant wagering conditions have been completed and whether the balance includes funds still subject to them. If you request a cashout before meeting the requirements, the operator may hold or reject it under the promotion’s terms. That is a balance-eligibility issue, not a delay caused by the payment network.
The practical check is to review the promotion attached to your account and confirm the status shown for its conditions. Do not assume that a bonus has no effect simply because the deposited money appears in the same balance. If the terms are unclear, resolve that question before initiating a withdrawal.
Operators generally require funds to be returned to the same payment method used for a deposit where possible. This is why changing payment details at withdrawal can trigger an additional check or require the operator to establish which route is permitted. A fast payment rail cannot shorten that internal decision.
For PayID, enter the identifier associated with the casino profile and use the same PayID details used for deposits. A mismatch between the deposit record, account profile and withdrawal destination can lead to a security review. Do not substitute another person’s account or provide details that are not linked to your profile; the operator may be unable to release funds until ownership and routing are clarified.
If the original method cannot accept a return payment, the operator’s terms should explain what alternative process applies. Contact support before submitting a request if you know the deposit route is unavailable, rather than selecting an unrelated destination and creating a discrepancy.
The amount requested can also affect the checks applied. A specialist review lists withdrawals over $2,000 among possible causes of delay. That is not a universal threshold for every operator, but it indicates why a large request may be routed for additional scrutiny instead of automatic handling. Operators are required to disclose manual review processes for withdrawals exceeding $2,000; read the applicable terms and follow any stated procedure.
Some operators may also release a large withdrawal in instalments under their policy. In that case, the full balance may not arrive as a single payment even after approval. The relevant distinction is between the amount approved, the amount released in each payment, and the amount ultimately received.
Before requesting a withdrawal, check that identity verification is complete, bonus conditions are met, and the destination account matches the details linked to your profile. Use the same PayID details as for deposits where applicable. If a request is held, identify which step is pending—verification, balance eligibility, payment routing or manual review—rather than treating every delay as a payment-system failure.
These checks can prevent avoidable mismatches, but they cannot guarantee a sub-hour outcome. The operator must still approve and release the payment, and PayID withdrawal processing times may vary.
You can use credit or debit cards, PayPal, Skrill, bank transfers and, at some casinos, cryptocurrency. PayID is another option for bank-to-bank transfers; prepaid vouchers such as Neosurf are generally for deposits, not withdrawals.
PayID transfers can arrive in real time once the casino releases the funds, while the casino’s review can add time. E-wallet withdrawals are often processed within 24 hours, whereas bank transfers and card payments can take several days; traditional bank transfers may take up to five business days.
They are casinos that make cashing out straightforward, for example by supporting PayID and promptly approving withdrawals. Reported PayID averages include 47 seconds at Fastpay Casino, 68 seconds at PlayAmo and 3.2 minutes at National Casino, though reviews or verification can cause delays.
Choose one that supports a fast method such as PayID, clearly publishes withdrawal limits and explains any fees. Check its approval process and whether it offers auto-approval, and complete identity verification early to reduce delays.