The Interactive Gambling Act targets operators supplying real-money online casino games to people in Australia, while player liability is a separate question.
In Australia, the legal boundary for online casino play falls primarily on the business offering the games, not on the individual using a site. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. That covers casino-style play delivered over the internet, rather than only businesses based inside the country.
This distinction matters when you assess whether an online casino is safe to use. The fact that the law does not explicitly criminalise an individual player for using an offshore casino does not mean that the service is authorised to offer games to Australians. Player liability and operator legality are separate questions: the player’s position under the Act does not change the prohibition on providers.
The Act’s focus is the supply of the service. If an operator makes real-money casino games available to people physically located in Australia, the relevant legal issue is the operator’s conduct. A site’s overseas base or the fact that it accepts Australian customers does not, by itself, make its offer lawful under Australian rules. Nor does the word “safe” settle that question. It can refer to account security or how a site handles transactions, but those qualities are different from permission to provide online casino games in Australia.
When choosing an online casino in Australia, you should check the available licensing and payment details rather than relying on a safety label alone. This list highlights the specific information available for each operator.
Lucky Dreams
Lucky Dreams lists a Curacao license and a minimum deposit of A$20 via POLi. These details give you a starting point for checking its licensing and deposit options.
DragonSlots Casino
DragonSlots Casino is listed under the Curacao Gaming Authority, with Jumpman Gaming Ltd named as the operator. That licensing information is the main detail available for your review.
Wild Tokyo
Wild Tokyo lists a Curacao license and a minimum deposit of A$10. Its stated payout times are 30–60 minutes for crypto and 1–5 days for fiat.
MrPacho
MrPacho lists a minimum deposit of A$30. Its stated payout times are 30–120 minutes for crypto and 24–72 hours for fiat.
LevelUp Casino
LevelUp Casino lists Curacao eGaming license OGL/2023/174/0082, with Dama N.V. named in the license details. Its stated minimum deposit is A$15.
Playfina Casino
Playfina Casino lists a Curacao eGaming license held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino lists a Curacao eGaming license, with Roby Games Ltd named in the licensing details. This is the available factual detail for assessing its profile.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board license, OGL/2023/176/0095, associated with Hollycorn N.V. The license information is the main detail available here.
7Bit Casino
7Bit Casino is listed as operating under a Curacao license, with Dama N.V. named as the operator. Its licensing and operator details are the available points to check.
Kingmaker
Kingmaker lists a minimum deposit of A$30. Its stated payout times are around 90 minutes for crypto and 1–5 days for fiat.
The Australian Communications and Media Authority, known as ACMA, oversees online gambling regulation at the national level. Its role gives the law a practical point of reference: questions about the Australian rules belong in the context of ACMA’s regulatory remit, not solely in a casino’s own description of its status. The existence of a regulator does not, however, turn an offshore casino into an authorised Australian service.
For you, the key distinction is between being a player and being an operator. The Act does not explicitly make an individual’s use of an offshore casino a criminal offence. That is not a general endorsement of offshore play, a declaration that every site is safe, or a statement that Australian law treats the operator’s offer as lawful. It is a narrower point about who the Act prohibits from providing the games.
This also explains why a search for a safe online casino in Australia cannot be answered by looking only at the player’s exposure to prosecution. Legal status concerns whether the service may be offered to people here; safety involves separate questions about what happens when you use a particular site. Treating those as interchangeable can lead to a false conclusion: “the player is not explicitly criminalised” does not mean “the casino is licensed in Australia.”
The same distinction applies if a site presents itself as legitimate because it operates in another jurisdiction. An offshore licence, where one exists, relates to that jurisdiction’s oversight. It does not replace Australian authorisation or override the Interactive Gambling Act’s restriction on providing online casino games to people in Australia. A claim about the casino’s status abroad therefore cannot, on its own, establish that it may lawfully serve Australian customers.
 Australian Online Casinos for Real Money: What to KnowUnderstand real-money play, offshore casino rules, payments and bonus terms. The Interactive Gambling Act 2001 restricts operators, not individual players.
 New Online Casinos in Australia: What to CheckCompare how casino terms explain accounts, promotions and withdrawals, and what to check in payment details and bonus rules before registering.
When you read claims about safe casino access, identify what each claim actually addresses. A statement about the player’s legal position is not proof that the operator can offer the games here. A statement about an operator’s status overseas is not proof of Australian authorisation. And a site’s use of the word “safe” does not change the legal boundary set by the Act.
The practical starting point is therefore precise: Australian law prohibits operators from supplying real-money online casino games to people in Australia, while it does not explicitly criminalise individual players for using offshore casino sites. Keeping those two points separate helps you interpret claims about online casino safety without mistaking the player’s position for permission granted to the service.
PayID describes a way to send a bank payment; it is not a certification of the business receiving it. A transfer made with PayID therefore cannot, by itself, establish that an online casino is lawful in Australia, protects customer funds, or will honour a withdrawal. The payment method and the status of the service are separate questions.
PayID transfers generally travel through Australia’s New Payments Platform (NPP). A specialist review reports that a transfer may clear quickly, sometimes within minutes after it has been released. That timing concerns movement of the payment between participating accounts. It does not necessarily describe when a gambling account will show a deposit: the receiving service may still need to match the transfer to your account and update its own records. Nor does a fast transfer mean a payment can be reversed easily or that a recipient has been checked for you.
Attention: The speed of a PayID transfer concerns the movement of funds between accounts and does not prove that the receiving casino is lawful or authorised in Australia.
The distinction matters because payment confirmation is narrow evidence. It may indicate that a transfer was processed, but it does not tell you whether the recipient is authorised to offer online casino games to people in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to Australian residents. That legal boundary is not changed by a site offering PayID, displaying Australian-dollar amounts, or accepting a transfer from an Australian bank account.
It is also useful to separate payment speed from payment safety. In ordinary use, a quick transfer can reduce the time between authorising a payment and its arrival. It cannot verify the site’s claims, create consumer protections, or guarantee that a later request for funds will be paid. If a service presents PayID as proof that it is a “safe” casino, that claim goes beyond what the payment rail demonstrates. The same limitation applies to a site that advertises a no-deposit offer: a promotion does not validate the service or change the legal position.
Processing times vary by method and by the steps involved. A specialist review reports that PayID and some e-wallet payments may be quick after approval, whereas card and bank-transfer processing can take several business days. Treat that as a general comparison reported by that type of source, not a service-level promise for every transaction. The payment may need approval before it is released, and a delay at that stage is different from time spent clearing after release. A receiving service’s own account update can add another step.
This comparison does not make PayID the safer choice in every situation. It only describes a possible difference in processing. A card payment that takes longer is not automatically less secure, and a transfer that clears promptly does not make its recipient more trustworthy. The relevant question is what the transaction confirms: a payment method can move funds, but it cannot independently assess the operator behind the payment request.
Before authorising a transfer, check that the payment details shown to you match the intended recipient and that you understand what you are approving. If the details change unexpectedly, pause rather than relying on the fact that PayID is familiar or widely used. Keep a record of the payment confirmation for your own account records; it documents the transaction, not the legality or conduct of the service.
For Australians considering online casino payments, the central distinction is straightforward: PayID is a transfer mechanism, not an Australian gambling licence or a safety seal. The speed of a transfer tells you about a payment stage, not whether the service is permitted to offer casino games or whether it will resolve a dispute in your favour.
A real-money account involves more than a balance shown on screen. When you deposit, the service records funds against an account; when you request a withdrawal, it may first check that the account holder and payment method meet its verification requirements. These steps are account procedures. They do not establish that the service is safe, or that it is allowed to offer casino games to people in Australia.
An offshore service may require you to complete identity checks and deposits, but these account procedures do not change the legal prohibition on providing real-money online casino games to Australian residents.
Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to Australian residents. An offshore service may still ask you to create an account, accept a deposit and complete identity checks, but those actions do not change the law applying to the offer. Nor does the fact that a withdrawal process exists show that an Australian regulator has authorised the casino.
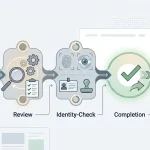
Casinos conduct know-your-customer checks, commonly called KYC, and require identity verification before withdrawals. The stated purpose is to confirm who controls the account and to check the details associated with it. In practice, the service may ask you to provide a photo ID, proof of your address and evidence that you own the payment method used.
Each document answers a different question. Photo ID links the account to a person. Address evidence supports the location details on the account. Payment-method evidence connects the funding instrument to that account holder. A request for these documents is therefore not, by itself, evidence of unusual treatment; it is part of the operator’s verification process.
The timing matters. A deposit may be accepted before the service has completed all checks, while a withdrawal request can prompt verification. If you have not supplied the requested material, or if the details do not match, the service may not complete the withdrawal until it has reviewed the account. You should understand what information is being requested and how it is meant to correspond with the account and payment method.
Take care with sensitive documents. Before sending them, check that you are using the account’s stated verification channel and that the request relates to the account you opened. Do not assume that a document upload is safe merely because it appears in a casino’s verification process. A request for identity documents is not a guarantee that the recipient will handle them properly.
Verification can confirm details within an account process; it cannot answer every question a player may have about a real-money casino. In particular, a KYC check is not an Australian licence, a legal approval or an independent assessment of how fairly a service handles deposits and withdrawals. A completed check should not be read as confirmation that the casino is safe for Australian players.
This distinction is important if you are comparing claims in a safe casino review or trying to decide whether an online casino is safe. The existence of a document checklist tells you what the service asks from customers, not what protection you can rely on if a dispute occurs. Likewise, being able to access an account on a mobile device does not change the legal status of the games offered.
Keep the legal question separate from the account question. The Interactive Gambling Act 2001 addresses what operators may provide to people in Australia. KYC addresses what an operator asks a customer to prove before releasing funds. One process does not substitute for the other: identity verification does not make a prohibited service lawful, and an account’s successful operation does not demonstrate that it is safe.
If a service asks for documents before a withdrawal, treat that as a condition of its account process rather than as a safety certificate. Consider what information you are being asked to disclose, whether the request is consistent with the account details you provided, and what the law says about the service’s offer to Australians.
A security badge or the word “safe” is a claim, not an explanation. To assess what a technical signal actually tells you, separate the protection it provides from risks it cannot address. SSL encryption is used by casinos to protect transactions and sensitive information as that data moves between your device and the website. It helps make intercepted traffic harder to read.
That protection matters when information is sent through a web connection. But encryption does not establish what happens before data is submitted or after it reaches the service. It cannot, by itself, show how an organisation stores information, who can access it, or how it responds to a security incident. Nor does an encrypted connection verify every claim made on a page.
When a browser establishes an encrypted connection, data exchanged through that connection is protected in transit. This is different from a page merely displaying a lock symbol or a security logo: the useful point is whether the browser indicates that its connection to the site is encrypted. If the browser warns that a connection is not secure, treat that as a reason not to enter sensitive details through it.
The distinction is about the connection, not the whole service. Encryption can reduce the chance that someone reading network traffic can make sense of the information being sent. It does not prevent every form of account compromise, misuse of information, or deceptive conduct. A secure connection is therefore one component of a safety assessment, not a certificate that all aspects of the service are safe.
This also explains why the words “safe bet” or “safe casino” are too broad to be technical conclusions. A site can use encryption and still leave important questions unanswered. Conversely, a security claim should be judged by the specific protection it describes rather than treated as proof of overall reliability.
When you review a security statement, identify its scope. Does it refer to protecting information during transmission, or does it imply that the entire service has been independently assessed? Those are not equivalent claims. SSL encryption supports the first; it does not establish the second.
Do not infer that an encrypted page makes every link, message, or request associated with it trustworthy. Check that you are on the intended web address before entering information, and pay attention to browser warnings rather than relying only on graphics or promotional wording. These checks help you assess the connection you are using; they do not validate the wider operation.
The same limit applies whether you are considering real-money play or browsing information about online slots. A secure connection can protect data sent to a site, but it cannot make a game, a payment decision, or the service behind the page safe in every sense. There is no sound technical shortcut that turns one signal into a complete verdict.
So treat SSL encryption as a narrow but relevant safeguard: it protects transactions and sensitive information in transit. Then keep that conclusion separate from broader claims about security. “Encrypted” describes a connection. It does not, on its own, answer whether the service is trustworthy overall.
A website loading in Australia does not establish that it is authorised to provide gambling services here. ACMA enforces online gambling rules and can ask internet service providers to block websites that offer prohibited interactive gambling services to Australian customers, as well as unlicensed services to adults in Australia. A block is an access measure; it is not a safety certification for sites that remain reachable.
ACMA can also issue blocking orders as a last resort when it considers customer safety to be at risk. This makes blocking part of enforcement, not a general rating system for websites. A site that has not been blocked has not thereby been assessed as safe, and a block does not tell you whether a particular site has secure account systems or handles payments responsibly.
ACMA directs Australians to its public information and register to check whether a wagering service holds a valid Australian licence. Use the register for that specific purpose: confirming the status of a wagering service that is within the Australian licensing framework. Read the service name carefully, since a similar name or a claim on a site is not the same as a register entry.
The register should not be treated as a directory of safe online casinos. An offshore licence is not an Australian licence, and it does not authorise an online casino to offer its games to people in Australia. Likewise, finding no relevant entry is not a reason to rely on the operator’s own description of its regulatory status. For information about ACMA’s enforcement approach, consult ACMA’s published material rather than relying on a site’s claims or an online review.
Safety can refer to different things: protection of personal information, fair account procedures, or a service’s legal status. A security feature may address one risk without answering the others. In particular, a foreign regulator’s licence may govern an operator in that regulator’s jurisdiction, but it does not turn the operator into a service licensed in Australia.
When assessing a claim, identify exactly what is being claimed and who can verify it. A statement that a site is “licensed” needs a jurisdiction and a matching entry on the relevant regulator’s register. For Australian wagering services, ACMA’s register is the public reference for checking an Australian licence. It does not convert an online casino into an authorised Australian service.
If a site presents an offshore licence as proof that it is an Australian casino, those are different claims. ACMA’s role is to enforce Australian rules, including by seeking blocks and, where customer safety is considered at risk, using blocking orders as a last resort. Its public information helps you understand that enforcement role; it should not be read as an endorsement of any casino website.
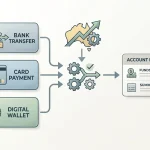
A payment method controls how money moves; it does not control how much you choose to gamble or reduce the risks of gambling. PayID and some e-wallets may process a payment quickly after approval. A specialist payment review contrasts that with cards and bank transfers, which can take several business days. These are processing differences, not measures of whether play is safe.
Describes how quickly a transaction is processed, such as fast PayID or e-wallet transfers versus slower card payments.
Account controls that restrict the amount you can deposit over daily, weekly, or monthly periods.
Resources providing information on gambling-related harm and routes to professional support services in Australia.
A fast deposit can make it easier to continue spending because the money becomes available sooner. A slower transfer does not create a reliable safeguard either: you can still make further deposits or use another method. Treat payment speed as a feature of the transaction, not as a reason to trust a service or as a substitute for setting boundaries.
Deposit limits work differently. They are account controls intended to restrict the amount you can put in over a chosen period. A specialist review of casino controls describes daily, weekly and monthly limits, but that description should not be taken as proof that such controls are available on a service accessible to Australians. Where a limit is offered, check what it actually applies to, when it takes effect, and whether you can change it immediately. A displayed limit is useful only if it meaningfully constrains deposits.
Support information is another separate safeguard. Reputable platforms provide information about gambling-related harm and direct people to professional support services across Australia. That information does not make a gambling service safe or authorised; it gives you a route to help if gambling is affecting your wellbeing, relationships or finances. If you are concerned about your gambling, contact a professional support service rather than relying on a payment restriction alone.
When assessing a payment option, separate three questions: how quickly a transaction may be processed, what controls are available to limit spending, and where to find help. An answer to one does not establish the others. For instance, an approved e-wallet payment may be quick, but that says nothing about deposit limits or access to support. Likewise, a limit does not change the time a bank transfer takes.
If you choose to use any gambling-related account, decide on a spending boundary before depositing and do not treat a convenient payment route as permission to exceed it. If the service provides clear harm information and routes to professional support, note where those resources are before you need them. Payment convenience, account controls and professional support serve different purposes; none should be mistaken for a guarantee of safe play.
A return-to-player figure, or RTP, describes a game’s theoretical payout as a share of wagers over a long run of play. It is a statistical description of the game’s design, not a forecast for your session. Results can vary from one play to the next, and an RTP figure cannot tell you whether you will win or lose on a particular occasion.
That distinction matters when assessing claims about safe casino games. An RTP figure says something about expected game returns under the version’s rules; it does not establish that a service is safe, authorised or available lawfully in Australia. Online slots and casino games, including blackjack, cannot lawfully be offered to people in Australia under the Interactive Gambling Act 2001. A game’s mechanics do not change that legal position.
If you are inspecting a pokie’s information, open its help or information panel. The relevant details are often behind an “i” symbol or a menu. Look for the RTP stated for that particular game version, rather than relying on a general description, promotional wording or a figure quoted elsewhere.
The display matters because a game title alone may not identify its return setting. Some providers make the same game available in multiple RTP versions. The operator selects which version to run, so two instances with the same title may not use the same return figure. Check the information shown within the game itself to see which version is presented.
RTP is not a measure of how often a game pays, how large an individual win may be, or how likely a particular outcome is. It also does not mean that a player receives the stated share back over a short session. The figure describes a theoretical average over extensive play; actual results can differ substantially.
For that reason, a higher displayed RTP should not be treated as proof that a game is safe or that it will produce a favourable result. It is one technical property of a particular version. It cannot verify the operator, override Australian law or guarantee an outcome. Free access, where offered, would not change the legal status of an online casino game provided to people in Australia.
A casino page that opens on your phone has not thereby been authorised to serve people in Australia. A mobile browser reports whether it can connect to a web address; it does not check whether the service may legally offer online casino games here. The same distinction applies when a login screen loads or an account accepts your details. Access is a technical result, not a safety or legal clearance.
ACMA can ask internet service providers to block websites that offer prohibited interactive gambling services to Australian customers, as well as unlicensed services offered to adults in Australia. If a block applies, the result may be that a page does not load through your usual connection. A site may still appear reachable at another time or through another route, but that does not establish that it is licensed in Australia or permitted to offer casino games. Nor does a broken page, by itself, tell you whether the cause is an ACMA-related block or a temporary technical problem.
This matters on mobile because changing networks can change what your phone can reach. A page might load over mobile data but not over Wi-Fi, or the reverse, depending on the connection and any blocking applied by the provider. Do not treat that difference as a test of whether a casino is safe. Repeatedly switching connections to reach a gambling site also does not change the service’s legal status.
A VPN changes the network route your device uses and may make a site appear accessible when it is not available through your ordinary connection. That is not a reliable safety measure or proof of authorisation. A casino’s terms may prohibit VPN access or access from a location it does not accept. If you use a VPN to access a casino, the operator may void winnings, close your account and keep your deposit. The possibility of those outcomes makes a VPN a poor way to resolve an access problem.
If a site is unavailable, do not assume that installing an app, changing networks or using a VPN makes it appropriate to proceed. Avoid entering payment or identity details simply because a mobile page looks polished or its login works. For information about gambling services and access restrictions, consult ACMA’s public information rather than relying on the fact that a page happens to open on your phone.
VPN Risks
Using a VPN to access a casino may lead the operator to void your winnings, close your account, and keep your deposit.
An account can pass identity checks and still sit outside Australian consumer protections. These are separate questions: verification is a procedure used by a gambling service, while authorisation concerns whether that service may legally offer its games to people in Australia. A request for documents, or an account marked as verified, does not make an unlicensed service licensed in Australia.
Casinos conduct know-your-customer checks and require identity verification before withdrawals. This may involve confirming that the account holder matches the identity and payment details on file. The check is about the account and its transactions; it is not an Australian regulator’s approval of the service. In practical terms, completing verification does not establish that you can rely on Australian protections if a dispute arises.
That distinction matters if an operator refuses a withdrawal, closes an account or disputes the balance shown on screen. An unlicensed gambling service does not provide the consumer protections attached to services authorised in Australia. If winnings are withheld, Australian laws may not assist you in recovering them. The fact that a site has collected your personal documents or processed deposits does not change that position.
So, is an online casino safe merely because it asks you to verify your identity? No. Verification may show that the operator applies an account procedure, but it cannot demonstrate that the operator is authorised in Australia or that you have an effective route to resolve a dispute. The same caution applies to claims about security features: they may address particular technical or account risks, not the absence of local consumer protection.
When assessing claims about safe online casinos in Australia, treat account checks as limited evidence. Do not infer legal status from a completed verification, a successful deposit or the ability to access a site. If an unlicensed service withholds winnings, you may have little practical recourse under Australian law. A polished account process does not remove that risk.
A deposit method and a withdrawal method are separate parts of a payment system. The route used to send Australian dollars to an account does not, by itself, determine how money can be returned. A payment service may support incoming transactions without providing a matching payout route.
A specialist payment review describes POLi primarily as a deposit method. Treat that as a reason not to assume that a POLi payment can also be reversed or used for a withdrawal. Before relying on any payment option, check the service’s stated withdrawal methods and conditions; the deposit screen alone does not establish them.
Card payouts also depend on how the payment is processed. Specialist payment reviews note that a card withdrawal may take longer or may not be available, depending on the processor. A card accepted for a deposit is therefore not proof that the same card can receive a payout. Processing arrangements can differ between incoming and outgoing transactions.
If a withdrawal is offered through another route, the destination may need to match the account holder or payment details on file. Confirm the exact method, currency and any conversion treatment shown in the payment terms before making assumptions about the amount that will arrive. Do not infer a fee, exchange rate or processing time from the fact that a service displays an Australian-dollar balance.
For a safe AUD payment experience, the useful question is not simply whether a payment logo appears. Check whether the stated withdrawal route is usable for your circumstances, whether the account details can be verified, and what the operator says happens when the deposit and payout methods differ. Keep the relevant terms and transaction records so you can compare what was displayed with what was processed.
A wallet can make a payment interface feel straightforward, but it does not settle these routing questions. The payment provider, processor and operator each have a role in whether a transaction can be sent or received. If the available information does not clearly explain the withdrawal route, the uncertainty remains; a successful deposit does not resolve it.
You may need to complete identity checks before a withdrawal is approved. PayID and some e-wallet withdrawals can be quick after approval, while bank transfers and card withdrawals can take several business days; card withdrawals may also be unavailable depending on the processor.
Australian law does not explicitly criminalise individual players for using offshore casino sites. However, operators are prohibited from offering real-money online casino games to people in Australia, and that does not make an offshore site authorised or safe.
Payment options mentioned include PayID, e-wallets, bank transfers and cards. POLi is mainly for deposits, so you should not assume it can be used for withdrawals.
Licensed operators provide deposit limits that you can set daily, weekly or monthly. Reputable platforms also share information about gambling-related harm and direct you to professional support services in Australia.