A practical look at identity checks, crypto deposits and withdrawals, banking options, and the conditions attached to casino bonuses.
“No KYC” is a marketing label, not a reliable statement that an operator will never ask who you are. KYC means “know your customer”: identity checks used to establish that an account belongs to the person using it. A service may let someone register or play before requesting documents, but that does not remove the checks that can arise later. For real-money withdrawals, casinos must verify a player’s identity before processing a payout.
This distinction matters if you are assessing claims about a no-KYC casino in Australia. A label might describe a sign-up process with fewer immediate questions, or simply attract people looking for less account friction. It cannot guarantee that the operator will release funds without verification. If a request for documents arrives when you try to withdraw, the earlier absence of checks does not override that requirement.
A specialist review reports that first withdrawals often prompt an identity-verification request. The reason is practical: the operator needs to confirm account ownership before releasing money. That request may involve documents or information used to establish identity, though the exact requirements depend on the operator. Do not assume that creating an account without submitting documents means the account has passed every check.
If you’re looking at no-KYC casino options in Australia for 2026, check the available details carefully before choosing. This list gives you a concise reference to the information provided for each operator.
Lucky Dreams
Lucky Dreams lists a Curacao license and a minimum deposit of A$20 via POLi. Those details give you a starting point for checking its fit.
DragonSlots Casino
DragonSlots Casino is listed under the Curacao Gaming Authority, with Jumpman Gaming Ltd named as the operator. The provided details focus on its licensing.
Wild Tokyo
Wild Tokyo lists a Curacao license and a minimum deposit of A$10. Its stated payout times are 30–60 minutes for crypto and 1–5 days for fiat.
MrPacho
MrPacho lists a minimum deposit of A$30. Its stated payout times are 30–120 minutes for crypto and 24–72 hours for fiat.
LevelUp Casino
LevelUp Casino lists Curacao eGaming license OGL/2023/174/0082, held by Dama N.V., and a minimum deposit of A$15. You can use these details when assessing the operator.
Playfina Casino
Playfina Casino lists a Curacao eGaming license held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino is listed under Curacao eGaming, with Roby Games Ltd named as the licensee. The provided information is limited to its licensing.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board license, OGL/2023/176/0095, held by Hollycorn N.V. The provided details focus on its licensing.
7Bit Casino
7Bit Casino is listed as operating under a Curacao license, with Dama N.V. named as the operator. No other operator details are provided here.
Kingmaker
Kingmaker lists a minimum deposit of A$30. Its stated payout times are about 90 minutes for crypto and 1–5 days for fiat.
The timing can therefore matter more than the phrase “no KYC.” If verification begins only at withdrawal, you may have to provide information and wait for it to be reviewed before the payment can be processed. Completing identity verification early can significantly speed up later withdrawals, because the identity-check stage has already been addressed. It does not guarantee a particular processing time or remove other conditions an operator may apply.
Treat any claim of a “no-KYC BTC casino,” “ETH casino” or similar crypto service with the same caution. Naming a payment type does not establish that identity checks are absent. A casino may accept an account or deposit before checking identity, yet still require verification before a withdrawal. The asset used to move funds does not change the requirement to verify the person receiving them.
There is a separate issue beyond an operator’s account procedures. Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games—including slots, poker and table games—to people physically located in Australia. The prohibition concerns the service provider; players do not incur a fine or criminal prosecution simply for playing at an offshore casino. Offshore services are also subject to active blocking and enforcement.
That context means “no KYC casino Australia” should not be read as a description of a locally authorised real-money casino product. Nor does a promise to skip identity checks make an offshore service lawful to provide in Australia. The label says nothing dependable about the operator’s legal status, whether funds will be paid, or what checks may be requested.
 Online Pokies PayID in Australia: How It WorksLearn how PayID routes bank transfers through Australia’s New Payments Platform, plus what to check on casino deposits, withdrawals and bonus terms.
 Real Cash Online Pokies in Australia: Play ExplainedLearn how free-play outcomes differ from cash stakes, what Bitcoin game credits represent, and why a displayed result is not a cash…
A useful way to interpret “no KYC” is narrowly: it may refer to what an operator asks for at an early account stage. It does not mean identity is never checked, that a first withdrawal will be automatic, or that the operator can process a withdrawal without verification. Before relying on such a claim, look for the withdrawal and identity terms rather than treating a headline as a promise. If the terms are unclear about when checks occur, assume that verification may be requested before funds are released.
A cryptocurrency payment changes how value moves between wallets; it does not determine whether a service may legally offer real-money casino games in Australia. The Interactive Gambling Act 2001 prohibits operators from providing online casino games to people physically located in Australia. The payment method does not alter that position. The mechanics below describe how a crypto transfer works in general, not a recommendation to use an offshore casino.
A crypto transfer has several distinct stages. First, the sender selects an asset and a compatible network. Then the sender enters the recipient’s wallet address and the amount, checks the details, and authorises the transfer in their wallet. The wallet broadcasts a transaction to the network. Network participants then validate it, and the transaction is recorded on the relevant blockchain.
Crypto Transfer Process
Selection
Select an asset and a compatible network.
Authorization
Enter the recipient’s wallet address and amount, check details, and authorise the transfer in your wallet.
Broadcast
The wallet broadcasts the transaction to the network.
Validation
Network participants validate the transaction, and it is recorded on the blockchain.
That sequence matters because “sent” and “received” can describe different points in the process. A wallet may show that a transaction has been broadcast before it is recorded on the blockchain. A recipient may wait for network confirmation before treating the funds as available. So a transfer can appear to move quickly without every stage being complete at the same moment.
A specialist review has described cryptocurrency transactions as potentially near-instant. That is a general description of the payment movement, not a guaranteed time for any particular transaction. Network conditions, the asset and network selected, and the recipient’s own handling of incoming payments can affect what the sender sees and when the recipient recognises the transfer. A quick blockchain transaction does not by itself mean that a casino account has been credited or that a withdrawal request has been approved.
The address and network must match. A wallet address is a destination identifier, and different assets or networks may use different address formats and transfer rules. If the sender selects an incompatible network or enters an incorrect address, the transfer may not reach the intended destination. Crypto transfers should therefore be treated as difficult or impossible to reverse once confirmed: there is generally no bank-style process for cancelling a completed blockchain payment. The important check occurs before authorisation, when the asset, network and destination are reviewed.
 New PayID Pokies in Australia: Payment GuideLearn how PayID deposits move through banks and the New Payments Platform, what to check before paying, and how to assess site…
 Australian Online Pokies: Legal and Bitcoin GuideLearn to assess Australian-facing pokies and Bitcoin claims; the Interactive Gambling Act 2001 bars operators from providing real-money online casino games in
Network fees are also separate from the amount being transferred. A wallet may display a fee for processing the transaction, but that fee is not the same as a platform’s own charge or an account balance adjustment. The sender should distinguish the amount leaving the wallet from the amount the recipient is expected to receive. The exact fee and the way it is calculated depend on the transaction and network; a faster-looking payment is not evidence that every related cost has been avoided.
The same distinction applies to withdrawals. If a platform displays a withdrawal as approved or released, that describes its own handling of the request. The onward crypto transfer still has to be created and broadcast, then recorded by the relevant network. Conversely, a transaction visible on the blockchain does not establish that the platform has completed any separate account review. The blockchain records a transfer; it does not certify why it was sent, whether the recipient’s account is eligible to receive it, or whether the underlying service is lawful.
This is why a label such as “instant” needs a precise meaning. It may refer to the movement of a transaction after it has been authorised and accepted by the relevant systems. It cannot reliably describe every step from a user’s initial request to funds being available in a recipient’s account. A service’s internal status, the network’s transaction record and the recipient wallet’s display are separate indicators, and they may not update together.
Crypto also does not make identity checks disappear. The payment rail and an operator’s account controls are different systems. Using Bitcoin, or searching for a platform described as a no-KYC crypto casino, does not establish that the operator will forgo checks or that a withdrawal will proceed without review. Nor does a crypto option make real-money online casino services lawful for people in Australia.
Legal Prohibition
Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia.
For any crypto transaction, the practical sequence is therefore: identify the asset and network, verify the destination, review the amount and fee, authorise the transfer, and distinguish the wallet’s broadcast status from later confirmation. Those checks explain what may change when funds move through cryptocurrency. They do not turn a fast transaction into an instant end-to-end payment, and they do not change the legal status of the service receiving it.
A cryptocurrency payment option describes how funds may be sent to an operator; it does not establish how a withdrawal will be handled. A deposit route and a cash-out route are separate parts of a payment arrangement, and the operator’s rules determine whether they match.
That distinction matters when a payment page displays cryptocurrency alongside other methods. Specialist reviews have reported that some offshore operators accept crypto, while also describing cards, e-wallets and bank transfers as options. A listed method is not, by itself, evidence that every method can be used in both directions. Nor does it establish that an operator will release a withdrawal to the same type of wallet used for a deposit.
In Australia, real-money online casino services are prohibited for operators under the Interactive Gambling Act 2001. A crypto payment option does not change that legal position. The distinction here is about how payment arrangements are described, not an endorsement or recommendation to use an offshore casino.
Operators generally require funds to be returned through the original deposit method where that is possible. This can make the deposit method relevant later, even if you are thinking only about getting funds into an account at the time of payment.
For example, if an operator accepts a crypto deposit, its terms may specify whether a withdrawal can return to a crypto wallet or whether another route is required. If a deposit is made through a different payment method, the operator may apply the same-method rule to that transaction instead. The exact arrangement depends on the operator’s published terms; the presence of a crypto deposit button does not settle it.
“Where possible” is important. A payment route may not support outgoing transfers, or the operator’s own rules may require another method. If the original method cannot receive a return payment, the operator may direct the customer to an alternative process. That possibility should be clear in the withdrawal terms before any deposit is made. Otherwise, you cannot infer the cash-out route from the deposit screen alone.
Read the deposit and withdrawal rules as separate instructions. Look for whether crypto is identified as a deposit method, a withdrawal method, or both. Then check whether the operator requires withdrawals to follow the original deposit route and what it says happens when that route cannot be used.
Also check whether the rules describe the wallet or account that can receive a payment. A method being accepted does not mean that any destination will qualify. In particular, the payment terms should make clear how the operator matches a withdrawal to the deposit that funded it, and whether it requires the same payment details.
If the terms are unclear, a support response may clarify the operator’s stated procedure, but it does not replace the written rules or change the legal status of the service. Avoid assuming that a deposit can be reversed simply because it was sent through a particular method. A withdrawal is a separate request handled under the operator’s process.
Treat that phrase as a claim about one part of the payment flow, not as a complete description of the account. The relevant questions are distinct:
The answers may differ. A service might accept cryptocurrency for incoming payments while setting different conditions for outgoing payments. Conversely, a withdrawal option shown in an account does not establish that every deposit method can be used to fund it.
This is why the phrase “crypto casino” can be too broad to guide a payment decision: it may refer only to an available deposit route. The withdrawal policy determines how funds are meant to come back, and that policy needs to be read independently. No payment label, including “no KYC,” establishes that identity checks will be absent or that withdrawals will follow a particular route.
A bonus can change the amount you must wager before you are allowed to request a withdrawal. The key detail is which balance the wagering requirement covers: the bonus funds alone, or the bonus combined with your deposit. These are different conditions, even when the offer description uses similar language.
With a bonus-funds-only requirement, the stated condition is attached to the promotional balance. With a combined-funds requirement, the deposit is included in the calculation as well. That distinction affects how much wagering must be completed before the balance becomes eligible for withdrawal. A specialist review describes both structures and regards a requirement applying only to bonus funds as preferable, because it does not add the deposit to the wagering calculation.
Do not infer the rule from an offer’s headline or from the word “bonus”. Read the terms that define the wagering base. Look for wording that identifies whether the calculation covers bonus credit alone or the combined deposit and bonus. If that point is unclear, the amount of wagering required cannot be determined reliably from the headline.
A no-deposit promotion and a deposit-linked bonus differ in how funds enter the account, but the name of the promotion does not by itself explain its wagering condition. The terms still need to specify which funds carry the requirement. A promotion described as free, no-deposit or crypto-related should not be treated as exempt from wagering conditions unless its terms clearly establish that.
Separate the questions when reading an offer:
The first two determine what is being counted. The third determines when you can act. If the terms say the requirement applies to a combined balance, do not assume that completing wagering associated with the bonus alone is enough. Conversely, where only bonus funds are covered, do not assume that the deposit has been added to the calculation.
Players must meet all applicable bonus wagering requirements before attempting to withdraw funds. A withdrawal request made before the condition is complete may therefore be premature. Check the relevant terms and the account’s displayed bonus status before submitting a request; the balance shown in an account is not, by itself, proof that it is available for withdrawal.
Pay particular attention to wording that distinguishes withdrawable funds from promotional funds. If the terms do not make the calculation clear, seek clarification before accepting or using the promotion. This avoids relying on an interpretation that may not match the stated rule.
Bonus Wagering
A bonus-funds-only wagering structure is preferable because the deposit is not included in the wagering base calculation.
The “no KYC” label does not answer questions about bonus eligibility or wagering. Nor does a payment method determine whether a bonus condition has been met. Treat those as separate checks: first establish what funds the requirement covers, then confirm that the requirement is complete before requesting a withdrawal.
For any offer, the practical comparison is not simply the size or name of the bonus. It is whether the wagering condition applies to bonus funds alone or to the combined deposit and bonus, and whether the terms state that distinction clearly. A bonus-funds-only structure is preferable on that specific point because the deposit is not included in the wagering base. Without clear wording, you cannot reliably assess the condition before accepting the offer.
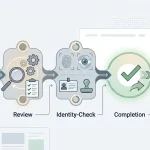
A withdrawal has two separate stages: the operator reviews and approves the request, then the payment is sent through the selected method. An advertised “instant withdrawal” can describe only the second stage. It does not mean that money reaches you instantly after you submit a request.
Before releasing funds, the operator must verify your identity. A first withdrawal may trigger a request for documents or additional information, so the review stage can take longer than later requests. Completing identity checks in advance can reduce this source of delay, but it does not remove other checks or guarantee a particular processing time.
The order of events matters. If a request is waiting for identity checks, the payment stage has not begun. If the operator has approved it, any remaining delay is more likely to involve its processing window or the receiving institution. A specialist review identifies first-time verification, bank processing windows and withdrawals exceeding $2,000 among possible causes of delay. It also describes manual review for withdrawals above that amount; an advertised fast payment method does not bypass that review.
Limits can affect how much is released and when. A per-transaction maximum sets the amount that can be requested in one withdrawal. Separate weekly or monthly cashout caps may also apply, so being below a single-transaction maximum does not necessarily mean the whole balance can be withdrawn at once. Large withdrawals may be released in instalments under the operator’s policy. Check the applicable limits and any stated review procedure before making a request.
Withdrawal Limits
Be aware that per-transaction maximums and separate weekly or monthly cashout caps may apply to your account.
The payment route can add another condition. Where possible, operators generally return funds through the same method used for the deposit. If that route cannot be used, the operator may need to confirm an alternative and check that it is linked to your profile. A change of details can therefore lead to further review rather than a quicker payout.
Treat a stated processing time as applying to a specific stage, not as a promise covering the full interval from request to receipt. The terms should make clear which event starts the clock, what review may occur, and which limits or fees apply. If a request remains pending, check whether it is awaiting approval or has already been released; those statuses point to different causes and different next steps. A payment that has not left the operator cannot be sped up by the receiving bank.
This distinction also applies to claims about a no-KYC instant withdrawal. “No KYC” does not cancel identity checks required before a withdrawal is processed. A fast transfer mechanism cannot replace the operator’s review, and the first cashout may be the point at which that review begins. The relevant measure is therefore not simply the speed named in a promotion, but the time across approval and payment, together with the conditions that determine whether the request can proceed.
For a clear comparison, separate the stated approval process from the payment estimate, then read both alongside the withdrawal limits and account requirements. If the terms do not explain when a request is considered approved or how a review affects timing, the word “instant” alone does not tell you when funds will arrive.
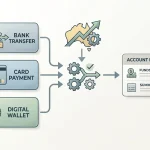
Payment methods differ in two ways: how funds are sent and whether the method supports both deposits and withdrawals. A payment option shown on a platform does not, by itself, establish that the service may lawfully provide online casino games to people in Australia. Real-money online casino services are prohibited under Australian law.
E-wallets hold funds in a separate payment account. A deposit may move from that account to a platform, while a withdrawal, if supported, must be sent back through the platform’s payment process. PayPal and Skrill are examples of e-wallets named in payment information for Australian players, but availability depends on the service and account. A specialist review reported that e-wallet transactions were completed within hours rather than days; treat that as a report about the cases it covered, not a general timing promise. Other payment information describes e-wallet withdrawals as typically processed within a day, but the operator’s approval step and the payment provider’s handling can affect the total wait.
Bank transfers move funds between bank accounts. They can be used in either direction where the service supports them, but the receiving bank’s processing is a separate stage from the operator’s decision to release a withdrawal. A specialist review reported that a traditional transfer could take as long as five business days to complete. That is a reported upper timeframe, not a prediction for every transfer. Bank processing windows, weekends and public holidays can affect when cleared funds appear.
Funds are held in separate accounts. Transactions can be completed within hours or a day, depending on the provider.
Funds move between bank accounts. These may take up to five business days depending on processing windows and holidays.
Connects a bank account to a platform via a provider. Speed depends on the service's acceptance and bank-side support.
Loaded with value before use. Generally available for deposits, but typically not supported for withdrawals.
Instant banking is a payment route that connects a bank account to a platform through a provider. A specialist review reported that some real-money platforms had offered instant banking through providers such as POLi. “Instant” describes the payment mechanism, not necessarily the time from starting a transaction to having a withdrawal available: the service still has to accept and process the request, and the bank-side route must support the transaction. The reported availability should not be read as a guarantee that a particular provider or service is available to Australian residents.
Prepaid cards and vouchers are loaded with value before use, so they can provide a way to fund a deposit without initiating a direct bank transfer at that moment. A specialist review described vouchers such as Neosurf as generally available for deposits but not withdrawals. If a voucher cannot receive funds, it cannot serve as the return route for a payout; another method may be required, subject to the operator’s rules.
When comparing methods, check both directions separately: deposit availability does not prove that withdrawals can use the same route. Also check the payment terms for fees, processing times and withdrawal limits before relying on a displayed option. A method described as fast can shorten the movement of funds, but it does not make a platform’s full transaction process immediate.
Ethereum, Tether and Ripple are names people may encounter when looking into cryptocurrency payments. Their names alone do not establish that a particular service accepts them. A specialist review reports that some casinos offer cryptocurrency, but that does not confirm which assets an operator supports, whether the same asset can be used for deposits and withdrawals, or whether availability applies to people in Australia.
The distinction matters because a payment method is an operator-specific feature, not a property of the coin itself. Before treating any cryptocurrency as available, you would need to see it listed in the operator’s own payment information and check the terms that apply to it. A mention of Ethereum, Tether or Ripple elsewhere is not evidence that it is accepted by a particular service.
A specialist review describes cryptocurrency transactions as capable of being near-instant. That describes a possible transaction characteristic, not a guaranteed end-to-end payment time. It does not establish how quickly an operator will handle a payment, nor does it show that every coin or transaction will move at the same speed. A coin name therefore cannot, by itself, support a promise of an instant payment.
“No KYC” is also not a payment type or a coin feature. It is a label that may suggest fewer identity checks, but it does not change the legal status of the service or prove that checks will not occur. Australian law prohibits operators from providing real-money online casino services to people physically in Australia. A crypto option or an identity-related label does not create an exception.
The practical conclusion is narrow: some casino services have been reported to offer cryptocurrency, and crypto transfers can be near-instant. Neither point confirms that Ethereum, Tether or Ripple is accepted by a particular operator, or that a service is available to Australians.
USDT describes a cryptocurrency payment option; a crash game describes a format of play. One does not establish the availability of the other. A site mentioning USDT does not, by that fact alone, show that it offers crash games, and a crash-game claim does not confirm that USDT can be used to pay.
A specialist review has described cryptocurrency transactions as capable of being near-instant. That refers to the movement of a crypto transaction, not to every stage surrounding it. It does not establish how quickly a service would accept a payment, whether a particular token or network is supported, or whether any game is available. Those details depend on the service and its stated terms, so a general claim about crypto speed cannot verify them.
The same distinction applies to “no deposit” promotions. A promotion’s label does not tell you whether it can be claimed, what conditions attach to it, or whether it is connected to a particular game or payment method. Treat payment claims, game descriptions and promotion terms as separate information rather than assuming one confirms the others.
There is also a legal boundary in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. A description of USDT payments or crash-style play should not be read as an invitation or assurance that such a service is lawfully available to Australian residents.
In practical terms, USDT, crash games and deposit-free offers answer different questions: how funds might move, what format a game might take, and whether a promotion is described as requiring a deposit. None of those labels, on its own, confirms the other two.
A free-spin offer does not, by itself, tell you whether winnings or related bonus funds carry wagering requirements. The promotion’s terms determine which funds are covered. A specialist review describes two possible structures: requirements can apply to bonus funds alone, or to the combined deposit and bonus. The bonus-funds-only structure is preferable because it does not attach the requirement to your deposit as well.
Before accepting an offer, locate the wording that defines the wagering base. Check whether it refers only to bonus funds or includes both the deposit and bonus. Do not assume that “free spins” means there are no conditions, or that the requirement applies only to a bonus. If the terms do not make the distinction clear, you cannot reliably tell what must be completed before a withdrawal can be requested.
The same check matters when a promotion is described as having no deposit requirement. That description alone does not establish whether wagering conditions apply; the actual terms need to say which funds are covered. Keep the distinction precise: the question is not simply whether a requirement exists, but whether it is attached to bonus funds alone or to the combined deposit and bonus.
A “live casino” label describes a claimed format; it does not establish that a service is available to you, which games it includes, or whether identity checks can be avoided. Do not treat the wording as proof of a particular game catalogue or of a no-verification option.
There is also a legal boundary. Under the Interactive Gambling Act 2001, operators cannot provide real-money online casino games to people physically in Australia. That prohibition covers casino-style games such as roulette, blackjack, poker and slots, whether presented with a live dealer or in another format. A website’s description does not change that position.
Claims about live-dealer availability and account requirements therefore need to be read separately. A statement about identity checks does not confirm that live games are offered, and a live-game claim does not establish that withdrawals can be made without identity verification. Casinos must verify a player’s identity before processing withdrawals.
For a reader in Australia, the practical distinction is between what a page advertises and what an operator may lawfully provide. Treat claims that combine “live casino” with “no KYC” as unverified descriptions, not as evidence of a permitted service or a way around the applicable requirements.
Payment options can include credit and debit cards, PayPal and Skrill, bank transfers, PayID and, at some sites, cryptocurrency. Prepaid vouchers such as Neosurf are generally for deposits, not withdrawals; note that operators providing real-money online casino games to people in Australia are prohibited under the Interactive Gambling Act 2001.
PayID withdrawals can arrive almost instantly after the casino releases them, while e-wallet withdrawals are typically processed within 24 hours and bank transfers or card payments can take several days. First-time identity checks, larger withdrawals and bank processing windows can cause delays.
PayID casinos with automatic approval and clearly published withdrawal limits may offer a smoother cash-out process. Reported PayID averages include 47 seconds at Fastpay Casino, 68 seconds at PlayAmo and 3.2 minutes at National Casino, though checks or other delays can make payouts take longer.
Check that the site clearly lists withdrawal limits and any fees, and review its withdrawal and identity-verification terms. Completing verification early can speed up later payouts; also check whether automatic approval applies and whether weekly or monthly cash-out limits are separate from per-transaction limits.