Withdrawal timing depends on separate checks, payment processing and receiving-account crediting, while Australian law restricts real-money online casino services.
A withdrawal is not a single event. It is a chain of separate actions: you submit a request, the operator checks and approves it, the operator sends the funds through a payment route, and the receiving service credits them to an account. The time shown for one stage does not necessarily describe the whole journey. To interpret a payout claim, identify which stage its clock measures and when that clock starts.
This is a description of payment mechanics, not an offer to use a casino service. Australian law prohibits operators from providing real-money online casino games to people in Australia. The Interactive Gambling Act 2001 covers casino-style services such as slots, poker and table games. That legal context matters when reading material about offshore services: a description of how a payment could move does not make the service lawful to provide in Australia.
The process begins when a player submits a withdrawal request through the account interface. The request records details such as the amount and chosen payout route. It then enters the operator’s system. At this point, the funds have not necessarily been sent anywhere: submitting a request is not the same as the operator releasing a payment.
If fast withdrawals matter to you, use this list to check which operators publish payout-speed details and what other basic information is available. Treat the stated speeds as a reference, not a guarantee of when a withdrawal will reach you.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 via POLi and a Curacao license. These details may help you assess its basic requirements and licensing.
DragonSlots Casino
DragonSlots Casino is licensed by the Curacao Gaming Authority and is operated by Jumpman Gaming Ltd.
Wild Tokyo
Wild Tokyo lists crypto payouts at 30–60 minutes and fiat payouts at 1–5 days. Its minimum deposit is A$10, and it has a Curacao license.
MrPacho
MrPacho lists crypto payouts at 30–120 minutes and fiat payouts at 24–72 hours. Its minimum deposit is A$30.
LevelUp Casino
LevelUp Casino lists a Curacao eGaming OGL/2023/174/0082 license held by Dama N.V. Its minimum deposit is A$15.
Playfina Casino
Playfina Casino is licensed by Curacao eGaming, with Hollycorn N.V. listed as the licensee since 2017. Its minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino is licensed by Curacao eGaming, with Roby Games Ltd listed as the licensee.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board OGL/2023/176/0095 license held by Hollycorn N.V.
7Bit Casino
7Bit Casino is listed as operating under a Curacao license and being operated by Dama N.V.
Kingmaker
Kingmaker lists crypto payouts at around 90 minutes and fiat payouts at 1–5 days. Its minimum deposit is A$30.
The operator’s processing phase is the interval between receiving the request and authorising its release. A request may be handled automatically or may wait for staff review, depending on the operator’s procedures and the circumstances of the account or transaction. The important distinction is functional: while a request is pending with the operator, the payment network has not yet begun transferring that withdrawal.
Approval marks a change of responsibility. Before approval, progress depends on the operator’s internal handling. After approval and release, the transfer depends more directly on the payment route and the institutions involved. A page that describes a payout as fast may be measuring only the time to approval, only the transfer after release, or both together. Without a clear start and end point, the word “fast” cannot tell you how long it takes for funds to reach an account.
Once released, the withdrawal travels through the selected payment method. The route may involve a payment provider or a bank before the funds appear in the destination account. The operator can initiate this stage, but it cannot make every external step occur at the same speed. A status such as “sent” may therefore mean that the operator has handed off the payment, not that the receiving account has already been credited.
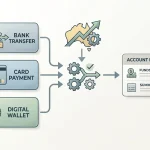
The available routes also differ between services. A specialist review of Australian-facing casino payment options describes debit cards, PayPal and Skrill e-wallets, bank transfers and, at some services, cryptocurrency. That list should not be treated as a guarantee that a particular route is available on every site or for every account. The relevant payment page and terms determine which method can be selected and what happens after release.
A useful way to read any timing statement is to ask what event it measures. Does it begin when you click the withdrawal button, when the operator approves the request, or when a payment provider receives it? Does it end when the operator marks it as paid, when the transfer is dispatched, or when the funds are usable in the receiving account? Those endpoints are different. A short approval interval can coexist with a longer transfer interval, and a rapid transfer cannot compensate for a request that has not yet been approved.
Account status messages can help locate a delay, but their wording may describe only the operator’s side of the process. “Pending” can indicate that the request is still being handled; “approved” or “processing” may indicate that it has cleared an internal step; “paid” may indicate dispatch rather than receipt. The exact meanings depend on the service’s own status definitions, so check those definitions rather than assuming that a label has a universal meaning.
For a clear comparison, separate the timeline into three points: request submitted, funds released by the operator, and funds credited to the destination. The first interval reflects operator processing; the second reflects payment transfer. If a published estimate combines them, it describes an end-to-end experience only if it states both endpoints. If it covers one interval, it should not be read as a promise about the other.
This framework applies whether a page discusses an e-wallet, a bank route or another payment method. The method determines how funds move after release, while the operator’s handling determines when release occurs. Keeping those stages distinct lets you interpret a payout claim without mistaking approval for receipt.
A withdrawal’s timing depends partly on the route used to send the money back. Once an operator has approved a request, an e-wallet, a bank transfer and a card payment do not necessarily move funds at the same pace. A short processing time at the operator’s end therefore does not mean that every method will put money in your account just as quickly.
E-wallets can have a relatively short transfer phase. A specialist review describes e-wallet transactions as completing within hours rather than days, and another timing estimate places e-wallet withdrawals within 24 hours. These are reported timeframes, not a guarantee for a particular payment. They also do not mean that a request is automatically approved as soon as it is submitted. The time before release and the time taken by the payment route are separate parts of the process.
Bank transfers can involve a longer wait after release. A specialist review reports that a traditional bank transfer may take as long as five business days to complete. That figure describes a possible transfer period, not a fixed countdown that applies to every bank or request. The general comparison is that bank transfers may take several days, while an e-wallet can complete in hours. If the operator has already released the funds, further waiting may belong to the transfer stage rather than the approval stage.
Card payments can also take several days, so a familiar card does not necessarily mean a faster payout. The timing estimate for card payments groups them with bank transfers as methods that may take several days. The exact route and the operator’s available payment options matter; the name of a payment method alone is not enough to predict when funds will arrive. In particular, do not assume that the time taken for a card deposit tells you how quickly a withdrawal to a card will be credited.
A useful way to compare methods is to ask what happens after approval. With an e-wallet, funds are sent to the relevant wallet account; with a bank transfer, they move through the banking route to the account receiving them; and with a card payment, the card-linked route is used if withdrawals to that method are supported. The recipient account, payment route and operator’s release of the request are distinct parts of the journey. A delay at one point does not establish that every other point is also delayed.
The deposit method can affect which route is available for withdrawal. Operators generally require funds to be returned to the same method used for the deposit where possible. That means choosing a payment method is not only a question of how quickly a deposit can be made. Before relying on a particular route, check whether it can also receive withdrawals and whether the operator requires the return to the original method. If the chosen method cannot receive a payout, another route may be needed, which can change the practical timing.
Reported completion within hours or up to 24 hours.
Traditional transfers may take as long as five business days.
Similar to bank transfers, these may take several days to complete.
For a speed comparison, separate three questions: whether the request has been approved, which method will receive the funds, and how long that method takes to complete the transfer. An e-wallet may have the shorter reported transfer timeframe, while a bank transfer or card payment may add several days after approval. If a quoted time does not say which stage it covers, it is not enough to predict when the funds will be available to you. Treat any published estimate as a description of a particular process, not as a promise that every withdrawal will follow the same schedule.
These distinctions are especially important when a service is described as offering a fast withdrawal. “Fast” may refer to the operator’s handling of a request, the payment transfer, or both; those are not interchangeable. A quick release cannot make a slower receiving route finish instantly, and a fast payment rail cannot remove time spent before approval. Compare methods by the stage and timeframe being described, rather than by a general speed label.
For people in Australia, this explanation should not be read as an endorsement or invitation to use offshore real-money casino services. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically in Australia. The timing distinctions above explain how payment routes differ; they do not change the legal status of the service or make a payout timeframe certain.
A payment option can work for adding funds without being available for receiving them. That distinction matters more than the speed label attached to a deposit method: if the method cannot accept a payout, the balance must be sent through another supported route, if one is available. A specialist review reports that prepaid cards and vouchers, including Neosurf, are generally presented as deposit options rather than withdrawal methods. Treat that as a reported pattern, not a guarantee about every provider or account.
Before entering payment details, read the payment terms for both directions of a transaction. Look for separate statements about deposits and withdrawals, rather than assuming that a method shown at the cashier supports both. If the terms only describe deposits, ask whether withdrawals to that method are supported and what alternative routes are available. A clear answer should identify the destination method and any conditions attached to using it.
Prepaid cards and vouchers can be useful for making a payment without linking it directly to a bank account, but that does not establish where a later payout can go. The key question is not simply whether a voucher is accepted. It is whether funds can be returned to it, or whether you would need a different payment route to receive them.
The same distinction applies to any payment method displayed on a cashier page. A list of deposit options is not necessarily a list of cashout options. Check the withdrawal section separately and confirm that the method you intend to use is supported for payouts. If a different route is required, make sure its account details belong to you and are compatible with the account rules. Operators may require funds to be returned to the original deposit method where that is possible.
For PayID, use the same PayID details for deposits and withdrawals. Changing the identifier can trigger a security review, so confirm the details before making a deposit rather than trying to correct them at cashout time. More generally, withdrawal funds should go only to accounts linked to your profile.
Payment logos can indicate that a method is available for one transaction type, but they do not explain all the conditions. Check the written terms for supported withdrawal methods, fees, processing times and limits. If the wording is unclear about whether a prepaid option is deposit-only, do not assume it can receive a payout. Seek clarification before committing funds.
A useful check is to trace the complete route on paper: the method used to deposit, the method available for withdrawal, and any account details required for the destination. If there is no supported way to withdraw through the method you planned to use, the apparent convenience at deposit does not solve the cashout problem. A different route may involve separate requirements, so establish those before proceeding.
There is also an important Australian context. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including slots, to people in Australia. This explanation is not a recommendation to use such a service. If you are assessing payment information, distinguish general descriptions of payment methods from permission to provide casino services to Australian customers.
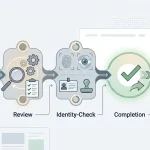
A withdrawal request can be entered before it is ready for payment. The account must first pass the operator’s identity checks. Until that review is complete, the request may remain pending even if you have selected a payment method and confirmed the amount.
A specialist review reports that first withdrawals often prompt a request for identity verification. This is when the operator checks that the person using the account is the account holder. The timing can therefore differ between an initial request and later ones: an account that has not yet cleared the checks has an extra step before payment can be processed.
Verification is not the same as transferring funds. It is an account review that must be completed before the operator can process a withdrawal. That distinction matters when you assess a claim about fast cashouts. A short payment time cannot remove a review that has not yet taken place, so the request may not reach the payment stage as soon as you submit it.
If the site asks for information or documents, follow its instructions and check that each submission is legible and complete. If something is missing or unclear, the review may need further attention. Avoid sending repeated or conflicting details; instead, use the account’s verification process and check its status there. The exact requirements depend on the operator, so read its instructions rather than assuming another site uses the same process.
Completing identity verification before you need to withdraw can significantly speed up future requests. The reason is straightforward: once the account has passed the checks, a later withdrawal may not have to wait for the same initial review again. This does not guarantee that every later request will be processed immediately. An operator may still need to review a transaction, but early verification removes one known source of delay.
Before relying on a site’s stated withdrawal speed, find out whether the figure begins when you submit a request or only after approval. Also check what the operator requires to verify your identity and whether your account is already marked as verified. A displayed speed describes little if the request is still waiting for account checks.
Speed Tip
Completing identity verification before you need to withdraw can significantly speed up future requests by removing the initial review delay.
For Australian readers, this subject sits within an important legal boundary: the Interactive Gambling Act 2001 prohibits operators from providing online casino games, including slots, to people in Australia. This explanation describes how identity checks affect withdrawal timing; it is not an endorsement of using an online casino service.
A payment can move quickly after approval and still leave you without access to the full balance. The amount released is a separate part of the process: an operator’s rules may set a minimum for each request, a maximum for one transaction, or a ceiling on total withdrawals over a stated period. A report by filmink.com.au notes that withdrawal amounts can be restricted by casino policy.
These limits affect timing indirectly. If a balance exceeds the maximum for one request, you may need to submit more than one request. If a cumulative cap applies, splitting the balance into smaller requests will not necessarily make the full amount available sooner: the cap may still restrict how much can be paid during the relevant period. Weekly or monthly limits may sit alongside per-transaction maximums, according to a specialist review. The terms should therefore be read as a set, rather than treating the largest displayed figure as the only constraint.
Before relying on a stated maximum, establish what it applies to. Check whether it is a per-request amount or a total allowance over a period, and whether a minimum also applies. Look for wording that distinguishes the amount requested from the amount actually payable under the account’s terms. Where the rules are unclear, the displayed figure alone cannot tell you how much can be withdrawn or how quickly the balance can be released.
Specialist reviews report that some PayID services set out minimum and maximum withdrawal limits clearly. Clear disclosure makes comparison easier, but it does not mean that the largest limit is automatically the most useful. A lower transaction ceiling can matter little for a small balance, while a cumulative cap may affect access to a larger one. The relevant question is how the rules apply to the amount and schedule of the payment, not simply whether the service advertises a fast transfer.
This is distinct from processing speed. A short approval or payment phase does not remove a limit, and a high limit does not guarantee rapid release. Amount rules determine how much may be paid in each request and across the applicable period; timing rules determine when an eligible payment is processed. Both need to be understood before you can estimate when funds might reach an account.
In Australia, real-money online casino games are prohibited services when provided to people physically in the country under the Interactive Gambling Act 2001. The limit discussion is therefore informational, not a recommendation to use an offshore casino. If you are reviewing published terms, read the minimum, per-transaction maximum and any weekly or monthly cap together. That combination reveals whether a fast payment claim is relevant to the amount you could actually receive.
A withdrawal can be unavailable because bonus conditions remain incomplete, even when the account balance appears ready to cash out. The displayed balance may include funds that are still subject to wagering requirements. Those requirements specify how much eligible play must occur before bonus-related funds become withdrawable. Until they are met, a payment request may be rejected or held under the terms governing the bonus.
Attention Funds subject to wagering requirements are unavailable for withdrawal until all bonus conditions are fully satisfied.
The calculation depends on which funds the requirement covers. It may apply only to the bonus, or to the combined value of the deposit and bonus. A specialist review of bonus terms describes bonus-funds-only wagering as the more favourable structure: it leaves the deposit outside the wagering calculation. The wording matters. Check the stated calculation base, which games or activity count towards it, and whether the terms impose any other conditions on withdrawal.
A no-deposit offer does not remove these checks. It may provide bonus funds without a matching deposit, but the bonus rules can still make the resulting balance conditional. Before treating any displayed amount as cash available for withdrawal, read the rules attached to that specific offer and confirm that its requirements have been completed. Do not assume that a bonus described as free or withdrawable has no conditions.
The same distinction applies when speed is the priority. An advertised instant withdrawal cannot make funds eligible before the relevant bonus conditions are satisfied. Payment speed describes what may happen after a request is eligible for processing; it does not override the offer’s rules. A request made too early can therefore add friction rather than shorten the time to access funds.
Verification is a separate requirement, not an alternative to meeting wagering conditions. A service claiming that you can withdraw without verification should not be treated as a dependable way around identity checks. Casinos must verify a player’s identity before processing withdrawals, and completing wagering does not remove that requirement. Conversely, completing identity checks does not make bonus funds withdrawable if the wagering requirement is still outstanding. These are distinct checks, and both can affect whether a cashout proceeds.
There is also a legal boundary specific to Australia. Under the Interactive Gambling Act 2001, providing real-money online casino games, including slots, to people physically located in Australia is illegal. This explanation is not an endorsement or recommendation to use an online casino or claim a bonus. If you encounter an offer, its wording does not change the legal status of the service.
For any bonus terms you are reviewing, focus on the exact wagering base and the conditions for releasing funds. If the rules say wagering applies to the deposit and bonus together, do not calculate progress as though only the bonus counts. Treat the balance as unavailable for withdrawal until the stated requirement is met and the required identity checks are complete.
Cryptocurrency changes the transfer rail, not the operator’s authority to release a withdrawal. A crypto transaction is sent to a wallet address over its network rather than through a card scheme or bank account. A specialist review has described cryptocurrency transactions as potentially near-instant, but that refers to the transfer itself; it does not establish how quickly a casino will approve or send a payout.
That distinction matters when assessing claims about Bitcoin payouts. A fast network transfer cannot make a request move before an operator has completed its own checks and initiated the transaction. After it is sent, the receiving wallet or service must recognise and credit it. Network confirmation and the operator’s payout procedure are separate steps, so a speed claim about one does not describe the entire journey.
A fast network transfer in cryptocurrency does not bypass the operator's internal checks or the time required for the operator to initiate the payout.
Crypto also differs from the broader set of payment methods Australian players may encounter, which includes cards, PayPal and Skrill e-wallets, and bank transfers. Some specialist reviews report that certain real-money casino services offer cryptocurrency, but availability is not universal. More importantly, payment availability should not be mistaken for legal permission to provide the service in Australia.
The Interactive Gambling Act 2001 prohibits operators from supplying online casino-style games, including slots and table games, to people in Australia. That applies to the service regardless of whether funds are handled in cryptocurrency, by card or through a bank. Crypto does not create an exception to the law or make an otherwise prohibited service lawful.
If you are comparing payout descriptions, separate three things: the operator’s decision to release funds, the network’s handling of the transaction, and the receiving wallet’s crediting process. Ask what event the stated speed measures. “Sent” may mean the operator has initiated a transfer; it does not necessarily mean the funds are already available to spend. Also check that the stated method is actually supported for withdrawals, rather than only for deposits.
The practical difference, then, is the route taken after funds are released. Crypto can involve a direct network transfer and may be described as very fast, while bank-based methods use payment infrastructure tied to financial institutions. Neither route removes the operator’s role, and neither makes the overall request-to-receipt time predictable from the transfer speed alone.
“Instant” can describe the transfer after an operator releases a payment, rather than the full time from submitting a request to receiving funds. That distinction matters: an advertised speed may apply only once the operator has finished its checks and authorised the withdrawal. A fast payment stage cannot remove time spent waiting for approval.
A specialist review reported a case in which a site labelled withdrawals “instant” but took up to 24 hours to release funds because of internal review. Treat that as an example of how a claim can depend on the operator’s workflow, not as a timetable that applies across the market. The wording alone does not tell you whether review is automated, when staff handle requests, or whether a particular request will need extra checks.
The request itself may be paused while the operator confirms account details or examines a payment. A specialist review identified first-time identity checks, requests above $2,000 and bank processing windows among possible causes of delay. These are different kinds of hold: an identity check concerns the account, a larger request may receive additional scrutiny, and a bank window affects the transfer after release. The same “instant” label cannot explain which stage is covered.
To interpret a speed claim, look for its starting and ending points. Does the stated time begin when you submit the withdrawal, when the operator approves it, or when funds are sent? Does it describe a specific payment route, and are review periods excluded? If those details are absent, the claim does not establish when the money will reach your account.
Processing windows also matter. A request made outside the operator’s handling period may wait before review begins, even if the payment route itself can move funds quickly. Likewise, a pending status means the operator has not necessarily released the payment; it is not evidence that the transfer stage has started.
Legal Prohibition
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia.
In Australia, real-money online casino services are prohibited for operators under the Interactive Gambling Act 2001. Where you are assessing a payment-speed statement, read “instant” narrowly: it may refer to the transfer phase after approval, not a guaranteed immediate journey from request to receipt. A meaningful claim should make that boundary clear and explain any review conditions that can delay release.
Cryptocurrency can move quickly once a transaction is broadcast, but that describes the transfer itself—not the full time between requesting a withdrawal and receiving funds. A specialist review has described crypto transactions as potentially near-instant; that is a reported capability, not a dependable timing promise for every payment.
A withdrawal has to reach the point where the operator releases it before the network transfer can begin. Any account checks or internal handling before release remain separate from the crypto network’s processing. This distinction matters when a site describes a payout as fast: a rapid transfer after release does not establish that the request will be approved or sent just as quickly.
After broadcast, the transaction must be recorded by the relevant network and recognised by the receiving wallet or service. Network conditions and the recipient’s requirements can affect when funds are treated as available. A displayed transaction status may therefore change before the recipient can use the funds. The exact process depends on the cryptocurrency and the services involved, so a speed claim for one route should not be assumed to apply to all crypto payments.
Before relying on a crypto withdrawal, check which currency and network are supported, what destination details are required, and how the operator defines completion. Incorrect destination information can make a transfer difficult or impossible to recover. Also confirm whether the amount you can request, any charges and the operator’s processing conditions are set out clearly. A near-instant network transfer does not remove those constraints.
There is an important Australian legal context: providing real-money online casino games to people in Australia is prohibited under the Interactive Gambling Act 2001. Crypto does not change that rule or make a prohibited service lawful. Timing descriptions should not be read as an endorsement or assurance that a real-money casino service is available or lawful in Australia.
PayID is an identifier used to send money between bank accounts through Australia’s New Payments Platform (NPP). The system supports real-time payments, with transfers processed through the Osko network. That infrastructure can move funds quickly, but it does not control when a payment is submitted by a gambling operator.
A withdrawal has two distinct points: the operator releases the payment, then the bank transfer is carried out. A specialist review describes funds as moving instantly once the operator releases them. That timing applies to the transfer phase, not necessarily to the full period from submitting a request to seeing money in your account. The operator’s processing step happens first; PayID cannot make that step faster.
For a PayID request, the described process is to sign in, open the Wallet or Withdrawal area, enter your PayID details, specify the amount and confirm. Use the same PayID details used for deposits, and make sure the destination account is linked to your profile. A mismatch may prompt a security review rather than a straightforward payment.
The status shown after you submit matters. A request that is awaiting approval has not yet reached the bank-transfer stage. Once the operator marks it as released or paid, the real-time payment network can carry out the transfer. If funds have not appeared, check whether the payment is still pending with the operator or has been sent onward; those statuses point to different parts of the process.
PayID is therefore not a promise that every withdrawal will be immediate from request to receipt. It describes the payment route’s ability to transfer funds in real time after release. The operator’s terms should state applicable withdrawal limits, fees and processing times. This separation helps you interpret claims about a fast PayID withdrawal: the payment network may be rapid, while the operator’s decision to release the funds remains a separate step.
Compare the time from request to release separately from the time to receive funds, and check the available payment methods, withdrawal limits and any fees. Completing identity verification early can help avoid delays, but note that Australian law prohibits operators from providing real-money online casino games to people in Australia.
After approval, e-wallet withdrawals are often completed within hours and typically within 24 hours, while bank transfers and card payments can take several days; traditional bank transfers may take up to five business days. PayID transfers can be near-instant once the casino releases the funds, though internal checks can delay release.
They are services whose withdrawal process is relatively straightforward and quick, with clear limits and payment routes that can deliver funds promptly after release. E-wallets and PayID can offer fast transfers, but operator approval and identity checks may still add time.
Options can include debit cards, PayPal and Skrill e-wallets, bank transfers and, at some services, cryptocurrency. Availability varies, and prepaid vouchers such as Neosurf are generally for deposits rather than withdrawals.