Withdrawal timing depends on operator approval and the separate transfer handled by a payment provider or banking network.
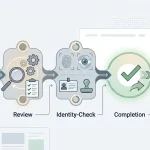
A withdrawal has two distinct stages. First, the operator checks the request and decides whether funds can be released. Then the payment provider or banking network transfers the released funds to the destination account. The time you experience runs across both stages, so a fast transfer mechanism cannot by itself make the entire process immediate.
This distinction matters in Australia because real-money online casino games, including slots and table games, are prohibited services when offered to people in the country. The explanation below describes how withdrawal timing works as a process; it is not an offer of those services.
When a withdrawal request is submitted, the operator must establish that it is valid and that the account and funds can be cleared for payment. Identity verification is part of that process: casinos must verify a player’s identity before processing a withdrawal. If the required checks are incomplete, the request cannot move directly to payment.
When you’re choosing a casino for easy withdrawals, clear payout information matters. Use this list to see which operators have stated withdrawal speeds and which offer only limited details to assess.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 via POLi and a Curacao licence. No withdrawal speed is provided here, so you’ll need to check its payout terms before depositing.
DragonSlots Casino
DragonSlots Casino is listed under the Curacao Gaming Authority, with Jumpman Gaming Ltd named as the operator. No withdrawal speed or minimum deposit is provided here.
Wild Tokyo
Wild Tokyo states crypto payouts of 30–60 minutes and fiat payouts of 1–5 days. Its listed minimum deposit is A$10.
MrPacho
MrPacho lists crypto payout times of 30–120 minutes and fiat payouts of 24–72 hours. The minimum deposit is A$30.
LevelUp Casino
LevelUp Casino lists a Curacao eGaming licence, OGL/2023/174/0082, held by Dama N.V., and a minimum deposit of A$15. No withdrawal speed is provided here.
Playfina Casino
Playfina Casino lists a Curacao eGaming licence held by Hollycorn N.V. since 2017. Its minimum deposit is A$20–30, depending on the offer; no withdrawal speed is provided here.
Roby Casino
Roby Casino is listed under Curacao eGaming, with Roby Games Ltd named as the licensee. No withdrawal speed or minimum deposit is provided here.
GoldenCrown
GoldenCrown lists a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. No withdrawal speed or minimum deposit is provided here.
7Bit Casino
7Bit Casino is listed as operating under a Curacao licence, with Dama N.V. as the operator. No withdrawal speed or minimum deposit is provided here.
Kingmaker
Kingmaker lists crypto payouts at around 90 minutes and fiat payouts in 1–5 days. The minimum deposit is A$30.
A first withdrawal can be the point at which identity documents are requested or reviewed. That adds an operator-side step before any payment provider is involved. The request may remain pending while the operator checks the information, asks for further material, or resolves a mismatch between account details and the withdrawal request. Those checks are separate from the speed of the eventual transfer.
Completing identity verification before a withdrawal is requested can make later withdrawals faster, because the operator may not need to begin the same identity review at that stage. It does not remove every possible check: a new request can still need review, and the operator still has to approve its release.
The account details matter too. Operators generally return funds to the deposit method where that is possible. This allows the withdrawal to follow the account and payment path already associated with the player, rather than introducing a destination that has not been linked to the profile. If the requested destination differs from the method used to deposit, the operator may need to check the request or ask for another route. That can hold up approval even when the destination service itself transfers funds quickly.
A withdrawal request is therefore not the same as an instruction already sent to a bank. Until the operator completes its checks and releases the funds, the payment stage has not started. A status such as “requested” or “pending” describes this operator-side interval, not the time the bank or payment provider needs to deliver the money.
After approval, the released amount is passed into the relevant payment channel. The provider then handles the transfer to the account or wallet designated for receipt. How quickly this stage proceeds depends on the channel and its own processing arrangements. The operator’s approval time and the provider’s transfer time are different measurements, even if a site presents them together as one payout estimate.
This is why “instant” should be read narrowly. It can describe the movement of funds after release, not the whole journey from submitting a request to seeing funds arrive. If the review takes time, a real-time transfer system cannot make that earlier interval disappear. Conversely, approval may be completed promptly while the receiving provider still needs time to complete its part.
A specialist review has noted that payment speed can be affected by several factors, rather than by the payment method alone. That is consistent with the two-stage structure: operator checks, account information and the receiving channel all contribute to the elapsed time. A single headline speed does not identify which stage it measures.
Before relying on a stated processing time, check what event starts the clock. It may begin when you submit the request, when the operator approves it, or when the payment is sent. Those starting points produce different totals. A figure that refers only to transfer after release should not be treated as a promise about the full request-to-receipt period.
It is also useful to distinguish a withdrawal’s status from its destination. A request can be awaiting review even though the selected method is capable of rapid transfers. Once the operator releases it, the payment provider’s process becomes relevant. If the funds have been sent but have not appeared, the remaining interval belongs to the transfer stage rather than the original approval stage.
A withdrawal request is not an instruction already sent to a bank; the payment stage only begins after the operator completes its checks and releases the funds.
The practical way to understand an easy withdrawal is therefore to follow the sequence: request submitted, account and request checked, funds approved and released, then transferred to the linked destination. Each transition depends on a different part of the process. Looking only at the final payment method leaves out the approval step, which can determine when the transfer clock starts at all.
PayID is the identifier used to route a bank-to-bank payment; the transfer infrastructure behind it is Australia’s New Payments Platform (NPP). Payments sent through the Osko network can be processed in real time. That describes the movement of funds between accounts, not how quickly an operator decides to approve a withdrawal.
A withdrawal therefore has separate stages. You submit a request and the operator checks it against its account, identity and payment rules. Only after approval and release can the payment network move the funds. PayID’s real-time capability applies to that final transfer stage. It cannot make an unreviewed request reach your bank, and it does not ensure that every request is approved automatically.
If an operator offers PayID withdrawals, its stated process may ask you to sign in, open the wallet or withdrawal area, enter your PayID details, specify an amount and confirm the request. Use the same PayID details used for deposits. A mismatch can prompt a security review, while a destination account that is not linked to your profile may not be accepted. The exact steps and available options depend on the operator’s terms.
Identity checks also sit before release, rather than within the bank transfer. Casinos must verify a player’s identity through KYC procedures before processing a withdrawal. A first request can therefore involve checks that have not been needed for a deposit. Completing verification in advance can remove that particular source of delay from a later request, but it does not eliminate other reviews or guarantee immediate approval.
The operator’s handling time and the payment time should not be combined under a single claim such as “instant withdrawal.” A specialist review has reported PayID withdrawals taking under five minutes at some highly rated Australian options, but that is a report about particular services, not a dependable timetable for all operators. The same kind of review has described automatic approval below $5,000 AUD at some top-tier services. That claim should not be treated as a general rule: operators’ review procedures differ, and withdrawals above $2,000 require disclosure of any manual review process. Check the applicable terms rather than assuming a request falls outside review.
Once the operator releases an approved payment, PayID can carry the funds through the NPP in real time. The remaining delay may therefore be at the operator stage, not in the bank-to-bank transfer itself. Conversely, a rapid approval does not guarantee that a transfer will appear instantly in every circumstance; PayID processing times can vary. The useful distinction is between the time spent waiting for release and the time spent moving released funds.
PayID Withdrawal Process
Submit Request
Sign in, open the withdrawal area, enter your PayID details, specify an amount, and confirm the request.
Operator Review
The operator checks the request against account, identity, and payment rules, including KYC procedures.
Fund Release
Once approved, the operator releases the funds into the New Payments Platform (NPP).
Bank Receipt
PayID carries the funds through the NPP in real time to the linked bank account.
Before confirming a request, check that your PayID is correct and matches the details associated with your casino account. Read the withdrawal terms for the stated limits, fees and processing arrangements, and make sure you are using an account linked to your profile. These checks do not speed up the payment network; they reduce the chance that incorrect details or an unmet requirement sends the request back for clarification.
There is also an important Australian legal context. Real-money online casino services, including slots and table games, are prohibited for operators serving people physically located in Australia under the Interactive Gambling Act 2001. Describing how a payment system works is not an endorsement of using such a service. PayID itself is a bank payment method; its real-time transfer capability does not change the legal status of the service requesting or receiving a payment.
A withdrawal has a payment leg: after funds are released, the chosen method determines how they move to you. Published timing estimates for e-wallets, bank transfers and cryptocurrency describe that transfer leg, not a guaranteed interval from submitting a request to receiving money. The methods therefore cannot be compared as if their quoted times covered an identical process.
A specialist review reports that e-wallet transactions may be completed within hours rather than days. A separate processing estimate places e-wallet withdrawals within 24 hours. These figures describe reported expectations, not a fixed service level: the provider, the transaction and the route used can affect the result. The useful comparison is that e-wallet transfers are described in hours, while traditional bank transfers are measured in business days.
For bank transfers, a specialist review gives a possible completion period of up to five business days. Another estimate describes bank transfers and card payments as taking several days. The calendar matters: a business-day estimate does not mean that weekends or public holidays count as processing days. The receiving bank may also need to post the incoming payment after it has been sent. As a result, the time shown for a transfer should not be read as a promise about when cleared funds will appear in your account.
Cryptocurrency is different because it does not use the same bank-account transfer route. A specialist review says crypto transactions can be near-instant, but that describes a possible transaction speed rather than a guaranteed withdrawal time. The relevant timing still depends on the service handling the payment and the transaction being recognised by the receiving wallet. “Near-instant” is therefore a description of the payment rail under suitable conditions, not proof that a withdrawal request will be completed at that speed.
When comparing the three, keep the units and scope consistent. E-wallet estimates are expressed in hours, bank-transfer estimates in business days, and crypto descriptions may refer to near-instant transactions. Those labels are not equivalent guarantees. A quoted transfer time starts only when the payment has actually been sent; it does not establish when a request will be released or when funds will become usable.
The payment method also needs to be available for both sending and receiving money. A method that accepts a deposit may not necessarily support a withdrawal, and the destination details must match the requirements of the service handling the transaction. Check the applicable payment terms before relying on an estimated duration. In particular, confirm whether the stated time begins at request submission or at payment release, and whether it refers to business days or elapsed time.
Reported transactions may be completed within hours or within 24 hours.
Possible completion periods can take up to five business days.
Transactions can be near-instant, depending on the service and receiving wallet.
For a practical comparison, treat e-wallets as the option with reported hour-based estimates, traditional transfers as potentially taking several business days, and cryptocurrency as capable of near-instant transaction processing. None of those descriptions establishes the total time from a withdrawal request to receipt. The estimate only becomes meaningful once you know which stage it covers.
“Instant” can describe only one part of a payout: the movement of money after the operator has approved and released it. A payment rail may transfer funds quickly, but it cannot make the preceding review disappear. The time from submitting a request to seeing cleared funds therefore depends on both the operator’s handling and the receiving bank’s processing.
A specialist review reported that some sites advertising instant withdrawals took as long as 24 hours because of internal checks. That is a reported case, not a standard timetable. It shows why the label alone does not tell you when a request will be approved. Before release, an operator may need to confirm account details, check the requested amount against its procedures, or complete identity checks.
A first payout can take longer because the operator must verify who controls the account. Casinos must complete identity checks before processing withdrawals, and a first request may prompt a request for documents or further information. Until the review is complete, the payment provider has nothing to transfer.
You can reduce avoidable back-and-forth by making sure your profile details are accurate and that any requested documents are clear and current. If the operator asks for more information, the review cannot be completed until you supply it. Completing identity verification early can speed up future withdrawals, though it does not remove other checks or guarantee a particular release time.
The amount requested can also affect the approval stage. A specialist review identified withdrawals over $2,000 as a possible source of delay. Treat that as a reported example, not a universal threshold: the operator’s own terms determine what review applies. Where manual review is required for withdrawals exceeding $2,000, that process should be disclosed.
A request that needs additional assessment can remain pending even if the chosen payment method supports rapid transfers. Check the applicable terms for any review conditions before submitting a request; the payment method does not override them.
Approval and receipt are separate events. Once funds are released, the receiving institution and its processing window can still affect when they appear in your account. Filmink has reported that PayID transfers can be processed almost instantly, while bank transfers may take several working days. That comparison concerns the transfer stage; it does not include time spent awaiting operator approval.
When checking a status, distinguish between “pending” and “sent”. Pending generally indicates that the operator has not completed or released the request; sent indicates that the payment has left the operator’s side, although the receiving bank may still need to process it. If the status is unclear, ask which stage the request has reached rather than assuming the payment rail has failed.
For any real-money casino service, legal restrictions in Australia are also relevant: the Interactive Gambling Act 2001 prohibits operators from providing online casino games to people physically located in the country. A fast-payment claim does not change that legal position.
A balance shown on a real-money casino account may not all be immediately eligible for withdrawal. If a promotion has been accepted, its terms may attach a wagering requirement to the bonus funds, or to both the deposit and the bonus. Until the applicable requirement is met, the amount subject to it may not be available to cash out.
The key distinction is what the requirement covers. With bonus-funds-only wagering, the condition applies to the bonus rather than the deposit as well. A specialist review describes this as the preferable structure for players because a smaller portion of the account balance is tied to the promotion. If the terms include the combined deposit and bonus, both parts are within the requirement’s scope. The headline value of a bonus therefore does not tell you how much of your displayed balance is withdrawable.
Before accepting an offer, read the terms that define the wagering condition and identify which funds it covers. Check whether accepting the promotion changes the status of money you have deposited, as well as any bonus credit. If you cannot establish whether the requirement applies to the bonus alone or to the combined amount, do not assume that your full cash balance can be withdrawn. The written terms determine the condition.
Game activity matters because wagering requirements are tied to eligible play under the promotion’s rules. Activity that does not count under those rules will not satisfy the requirement. Do not infer eligibility from the fact that a game appears in the account or that a round has finished; use the promotion terms to determine what activity qualifies. The balance can remain subject to the condition even while its displayed value changes.
This creates a practical difference between a balance total and an available withdrawal amount. The total may include funds that are still governed by promotional conditions. Requesting a cashout before those conditions are met can mean that the request cannot proceed under the offer’s rules, or that accepting the request has consequences specified in those terms. Check the consequences before submitting anything; do not treat a withdrawal button as confirmation that every displayed dollar is clear of conditions.
If you do not want a promotion to affect your funds, examine its conditions before opting in. Once accepted, the offer may define how the deposit and bonus are treated together. Keep a record of the relevant terms and compare them with the account’s stated balance status before making a withdrawal request. This helps distinguish a genuine balance discrepancy from funds that remain subject to the promotion.
Australia’s Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in the country. This explanation is not an invitation to use such services. Where promotional terms are being reviewed, the central point is that wagering conditions can make some or all of a displayed balance unavailable until the stated requirement has been satisfied.
Legal Prohibition
Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia.
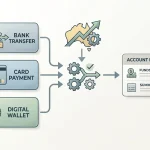
Payment options described in specialist reviews of offshore casino services include debit cards, e-wallets such as PayPal and Skrill, bank transfers and, at some operators, cryptocurrency. These descriptions are not a guarantee that a method is available to you: the options shown can depend on the operator, the account and the payment provider. More importantly, real-money online casinos are prohibited from providing their services to people physically located in Australia under the Interactive Gambling Act 2001. This overview is therefore not an endorsement or recommendation to use such a service.
A card may appear to be a familiar way to move money, but the distinction between card types matters. Australian players should not assume that a credit card can be used for online gambling: operators must not accept credit card payments for these services. Debit cards are listed among methods in specialist reviews, but a listing does not establish that a transaction is permitted, available or suitable in a particular situation.
E-wallets hold funds in a separate account and can be used to send or receive payments where a provider and merchant support that route. PayPal and Skrill are among the e-wallet names included in specialist descriptions of the payment landscape. Bank transfers move funds between accounts, while cryptocurrency transactions use a digital wallet and the relevant blockchain network. Some specialist reviews also describe cryptocurrency as an option at some operators. Availability alone does not settle questions about account access, transaction handling or legal status.
Prepaid vouchers follow a different pattern. A specialist review describes vouchers such as Neosurf as deposit methods rather than withdrawal destinations. That distinction is practical: a voucher can provide a way to add funds without necessarily providing a route to receive them back. Before relying on any payment method, the relevant terms would need to state whether it supports deposits, withdrawals or both, and what account details are required.
The method names are only one part of the picture. A payment option can be presented on a website without being available to someone in Australia, and payment-provider availability does not make the underlying gambling service lawful. Australian residents face no player liability for using an offshore casino, but the service itself remains prohibited for operators to provide in Australia.
In Australia, real-money online slots are prohibited interactive gambling services when provided to people in the country. The Interactive Gambling Act 2001 makes it illegal for operators to provide these services to Australians. This legal context matters when considering claims about withdrawing slot winnings: a fast payment option does not change the status of the service.
Identity checks are a separate part of withdrawal processing. Specialist reviews report that a first withdrawal can prompt a request to verify the account holder’s identity. Operators are required to complete KYC checks before processing withdrawals, so a payment may remain unreleased while verification is pending. The payment method does not replace this check or determine whether the operator has completed it.
Attention: A stated payment speed may only describe the transfer stage after approval, not the total time from request to receipt, as KYC checks must be completed first.
A verification request can involve confirming that the account details belong to the person seeking the funds. If the operator cannot complete its checks, the release may be delayed. This means that a stated payment speed should not be read as the time from requesting a withdrawal to receiving money: it may describe only the transfer stage after approval.
Treat requests for identity documents cautiously. Do not send sensitive information through an unverified link or to an address that cannot be connected to the service’s official account process. If a request is unclear, pause and seek independent advice rather than sharing more information. A request for documents does not establish that the service is lawful or that a withdrawal will be approved.
Before relying on any claim about a cashout, distinguish identity review from payment processing and read the operator’s terms for its stated verification and withdrawal conditions. Those details can explain why a request is pending, but they do not remove the legal restriction on providing real-money online casino games to people in Australia.
A balance shown after live-casino play is not automatically ready to reach your bank account. A withdrawal has two distinct stages: the operator must review and release the request, then the payment method carries the released funds. PayID can make the second stage very fast, but it cannot bypass the first.
This distinction matters when you assess claims about an easy withdrawal from a live-casino balance. “Instant” can describe the transfer after approval; it does not mean that the entire process begins and ends as soon as you submit a request. Until the operator releases the funds, they have not entered the PayID transfer stage.
PayID uses Australia’s New Payments Platform for bank-to-bank transfers. A specialist review has described PayID transfers as near-instant, and reports that funds move once the operator releases them. Treat that as a description of the payment phase, not a promise about when your request will be approved or received. The operator’s handling of the request remains a separate step.
Before requesting a withdrawal, check that your PayID details match the details linked to your casino profile and, where applicable, the details used for your deposit. A mismatch can prompt additional security checks. You should also complete any required identity verification and make sure the balance is eligible for withdrawal under the account’s terms.
The practical sequence is straightforward: submit the request using the PayID identifier associated with your profile, wait for the operator to approve and release it, then allow the transfer to reach the linked bank account. If the request is still pending, changing or re-entering payment details does not make the transfer begin; the operator has not yet released the funds.
When comparing live-casino withdrawal claims, look for wording that separates approval from payment. A stated PayID transfer speed applies only after release, while the full wait also depends on the operator completing its checks. This lets you distinguish a fast payment rail from a fast end-to-end process without assuming that the balance’s origin changes how PayID works.
Before requesting a withdrawal, identify exactly which funds a bonus wagering condition covers. The requirement may apply only to the bonus, or it may apply to the combined deposit and bonus. Those rules can produce very different amounts of play that must be completed before the balance becomes withdrawable.
Bonus-funds-only wagering applies the condition only to the bonus. Combined wagering applies the requirement to both the deposit and the bonus, meaning a larger portion of the balance is tied to the promotion.
A specialist review describes both approaches and favours wagering on bonus funds alone. The distinction is practical: if the deposit is included in the calculation, more of your balance is subject to the condition. Do not assume that a bonus applies only to the extra funds because it is labelled a deposit bonus. The offer’s terms determine the calculation.
Look for the wording that defines the wagering base, then check how it treats your deposit and any bonus credited to your account. If that wording is unclear, ask the operator to explain it before accepting the offer or playing with the funds. Keep the answer with the offer terms so you can refer to the same interpretation later.
A balance displayed in your account is not necessarily a withdrawable balance. Funds subject to an uncompleted wagering requirement may remain unavailable for cashout, even if you can see them alongside your other funds. Check the progress and completion conditions before submitting a withdrawal request; players must satisfy applicable bonus wagering requirements first.
Also check whether accepting the offer changes the status of your deposit as well as the bonus. Where the requirement covers the combined amount, withdrawing before completion may affect the funds governed by that condition. The important point is not simply how large the bonus appears, but what amount the terms require you to wager and which part of your balance is restricted until you do.
If you want fewer conditions attached to a cashout, compare the scope of the requirement before opting in. Bonus-funds-only wagering is preferable to a condition that includes both the deposit and bonus, but the written terms control. Do not base a withdrawal decision on a banner or short offer summary when the full rules define the eligible funds and completion requirement.
A cashout limit controls how much can leave an account, not how quickly the payment rail can move it. Before submitting a request, check the terms for the minimum and maximum permitted per transaction. A specialist review reports that some PayID services publish these limits clearly; the figures still need to be checked against the operator’s current terms, because they can differ between services.
Also look for a separate cap across a stated period. A weekly or monthly maximum can restrict the total you may withdraw even when each individual request is below the per-transaction ceiling. If the terms contain both kinds of limits, calculate how they interact: several smaller requests may still count towards the same periodic cap. Check whether the cap applies to requested or completed withdrawals, and whether the terms describe any process for handling a balance above it.
Fees affect the amount that reaches you. A report by Filmink notes that a fee may apply when PayID is used for a withdrawal. Check whether the terms identify who charges it, how it is calculated and whether it is deducted from the withdrawal or charged separately. Do not assume that a displayed balance and the amount received will be identical if a fee is permitted.
Read the cashout conditions together rather than treating each line in isolation. Confirm the minimum, per-request maximum, any periodic cap, possible fees and the stated processing conditions. Where wording is unclear, ask the operator to explain it in writing before making a transaction; retain the response and the version of the terms you relied on. A payment method’s transfer speed cannot override a limit or fee set by the operator.
For readers in Australia, these checks do not make an offshore online casino lawful: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically located in Australia. The terms can describe a service’s conditions, but they do not change that legal position.
Check that it clearly publishes withdrawal limits and explains its approval process, payout timing and fees. Completing identity checks early and using the same payment method for deposits and withdrawals where possible can help avoid delays.
Available options can include credit or debit cards, PayPal and Skrill, bank transfers and, at some sites, cryptocurrency. PayID can enable real-time bank transfers after the operator releases the funds; prepaid vouchers such as Neosurf are generally for deposits, not withdrawals.
They are sites where the cash-out process is straightforward, with clear rules and a prompt review before funds are sent. The transfer may be fast, but the operator’s checks and approval still affect how soon you receive the money. Real-money online casino services are prohibited in Australia.
It depends on both the operator’s review and the payment channel. E-wallets often take hours and are typically processed within 24 hours, while bank transfers can take up to five business days; PayID transfers can be real time once the operator releases the funds.