Visa may be more widely accepted than American Express, but that comparison does not confirm which casinos take Visa or whether withdrawals are supported.
A specialist review has described Visa as potentially more widely accepted than American Express at Australian online casinos. That is a limited comparison, not a guarantee that a particular operator accepts Visa or that the same payment options remain available over time. It also does not establish that Visa is accepted across the Australian market.
The distinction matters because “accepted” can sound more definite than the evidence supports. A broad comparison between two card brands does not identify which operators take either card, whether a card can be used for every type of transaction, or whether an attempted payment will be approved. It indicates only a possible relative difference in acceptance: Visa may be available in more cases than Amex.
This is not the same as saying that Visa is universally accepted, or that Amex is never accepted. The comparison leaves room for variation between services and for changes in what a provider supports. It cannot be used to infer a particular operator’s current payment terms. Nor does the word “Visa” alone tell you whether the card is credit or debit, or what conditions an issuer may apply to a transaction.
If you’re looking for an online casino that accepts Visa in Australia, check the available payment methods before depositing, as the details can vary. This list gives you a few verified operator details to help guide your research.
Lucky Dreams
Lucky Dreams is listed with a minimum deposit of A$20 via POLi. You’ll need to check separately whether Visa is available.
DragonSlots Casino
DragonSlots Casino is licensed by the Curacao Gaming Authority and operated by Jumpman Gaming Ltd. You’ll need to check its current payment options to confirm Visa availability.
Wild Tokyo
Wild Tokyo lists a minimum deposit of A$10, with payouts stated as 30–60 minutes for crypto and 1–5 days for fiat. Check directly whether Visa is among its available deposit methods.
MrPacho
MrPacho lists a minimum deposit of A$30 and payout times of 30–120 minutes for crypto and 24–72 hours for fiat. You’ll need to confirm whether it accepts Visa.
LevelUp Casino
LevelUp Casino is listed with a Curacao eGaming licence, OGL/2023/174/0082, held by Dama N.V., and a minimum deposit of A$15. Check its payment page to see whether Visa is available to you.
Playfina Casino
Playfina Casino is listed as licensed by Curacao eGaming, with Hollycorn N.V. named as the operator since 2017. Its minimum deposit is A$20–30 depending on the offer; confirm Visa availability before choosing an offer.
Roby Casino
Roby Casino is listed as licensed by Curacao eGaming, with Roby Games Ltd named as the operator. The available information does not specify its deposit methods, so check directly whether you can use Visa.
GoldenCrown
GoldenCrown is listed with a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V. Check the casino’s current payment options to confirm whether it accepts Visa.
7Bit Casino
7Bit Casino is listed as a Curacao-licensed casino operated by Dama N.V. Its Visa availability is not specified here, so you’ll need to verify the payment methods directly.
Kingmaker
Kingmaker lists a minimum deposit of A$30, with payouts stated as around 90 minutes for crypto and 1–5 days for fiat. Check directly whether Visa is available for deposits.
It is also useful to separate card-brand acceptance from approval of an individual payment. Acceptance describes whether a payment method is offered in a given setting. Approval concerns a specific transaction. Even where a method is listed, that fact by itself does not establish that every card, account, or payment will be accepted. The available comparison does not explain the reasons for any declined transaction, so it cannot support a more specific claim about payment outcomes.
For the same reason, a general statement about Visa should not be treated as a site list or recommendation. It does not establish which Australian-facing services accept the card, and it provides no basis for ranking them. A provider’s payment options may differ from another’s; a market-level comparison cannot resolve that difference for you. Any claim about a named service would need to be assessed separately against its own current terms, rather than inferred from the card brand’s relative position.
The wording “may be more broadly accepted” is deliberate. It preserves the comparison without turning it into a market-wide rule. “More broadly” refers to the relative scope of acceptance described in the specialist review; it does not quantify that scope, and it does not mean that Visa is available at every operator. “May” reflects that the statement is not a universal finding. Removing either qualification would make the claim stronger than its basis allows.
 Dragon Link Online Pokies in Australia: What to KnowLearn what a Dragon Link search can establish, how Bitcoin payments differ from game details, and why the name alone cannot confirm…
 Casinos That Accept CashtoCode in Australia: What to CheckLearn how ACMA enforcement and Australia's online casino rules affect CashtoCode claims, and why a payment mention does not verify service access…
This distinction is particularly important when a search for an Australian online casino that accepts Visa produces broad or absolute language. A result using phrases such as “Visa casino” may describe a payment option, but the phrase alone does not demonstrate current availability for Australian residents. It also does not establish that the service is lawful to provide in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to people in Australia; a payment method does not change that restriction.
Accordingly, the defensible takeaway is narrow: a specialist review has indicated that Visa may have broader acceptance than Amex in this context. It does not show that a particular Australian online casino accepts Visa, that acceptance is consistent across providers, or that a Visa payment will be approved. These are separate claims and should not be collapsed into one.
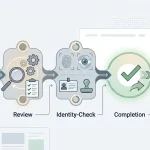
A card deposit is not necessarily the first step in using an online casino account. Before financial transactions, an online casino may require you to complete a Know Your Customer (KYC) assessment. This identity-check process can affect when you are able to use payment features, including a card deposit.
KYC means that the operator asks you to establish who you are. The check happens at account level, rather than being a property of the Visa card itself. Entering card details does not replace identity checks, and having a card does not by itself confirm that an account is ready for financial transactions. If the operator requests KYC before transactions, you may need to complete that assessment before proceeding to the cashier.
An identity-check process where an operator asks you to establish who you are, which may be required before you are able to use payment features.
The sequence can therefore have two distinct parts: account verification and payment submission. Treating them as one action can cause confusion. A card form concerns the payment; an identity assessment concerns the account holder. Completing one does not necessarily complete the other.
When an identity check is required, follow the operator’s instructions through its account process. The purpose is to assess customer identity before financial activity. The check is not a card authorisation and does not itself move funds. In turn, submitting a card payment does not establish that identity verification has been completed.
This distinction matters if a deposit option appears in the cashier while account checks are still pending. Seeing a payment method listed is not the same as having every account requirement cleared. The order of steps can depend on the operator’s process, so avoid assuming that a visible card option means you can submit a transaction immediately.
It also helps to keep the information you provide consistent. If the account details and identity information do not align, the operator may need to resolve that before financial transactions can proceed. Do not try to use payment entry as a substitute for responding to an identity request.
 Casinos That Accept POLi in Australia: What to CheckLearn how to verify whether a casino cashier lists POLi for Australian customers, and why deposit support alone does not confirm withdrawals…
 Bitcoin Casinos That Accept BTC in AustraliaLearn how Bitcoin deposits move from network detection to casino credit, and what to check about payments, withdrawals, bonuses and game rules.
Once the account process allows you to reach payment submission, the cashier is where you would select a payment method and enter the details requested for that transaction. Review the information shown on screen before you submit. The payment form and any account-verification prompts serve different purposes: the former sends a payment request, while the latter addresses customer identity.
A submitted transaction is not the same as a completed transaction. The payment request may be subject to checks by the operator and the card issuer. If the payment does not proceed, the cause could relate to account status, payment details, or a decision outside the cashier. Do not keep repeating the same submission without first checking the displayed status and any instructions provided.
Keep the account and payment records available so you can compare the transaction details if you need to resolve a problem. Use the operator’s stated support route for account or cashier issues, and contact your card issuer if the issue concerns its handling of a card transaction. Avoid sharing full card details in ordinary support messages.
The important point is that a card deposit can sit behind an identity check. If KYC is requested before financial transactions, the payment step may not be available until you complete the required assessment. If the check is already complete, the transaction can still depend on the separate payment submission and authorisation process.
This is why a displayed balance, a saved card, or an open cashier should not be treated as proof that a new deposit has been accepted. Look for a clear transaction status rather than inferring completion from the form closing or the account screen changing. If the status is unclear, check the account’s transaction record before trying again; duplicate submissions can make it harder to identify which payment request is being discussed.
Do not assume that every operator follows an identical sequence. The practical steps are controlled by the operator’s account and payment systems, while KYC is the identity assessment that may be required before financial activity. Reading the prompts in order helps you distinguish an account check from a card-payment issue and respond to the right one.
For a Visa payment in particular, the general process remains straightforward to understand: account identity checks may come first, then the cashier handles the payment submission. The precise screens and prompts are operator-specific. Follow the instructions presented in the account rather than treating a card deposit as a single action that bypasses verification.
A site-level comparison needs more than a general statement about Visa. To say that a particular website accepts the card, you would need current evidence tied to that operator and to the specific service being discussed. Without that, naming a “best” Visa casino or presenting a list of sites would turn a broad payment comparison into an unsupported claim about individual businesses.
The distinction matters because “accepts Visa” can mean different things. It may refer to a card displayed among payment options, a method available to some customers, or a transaction that is actually permitted for a particular account. Those descriptions are not interchangeable. A logo or an old review cannot, by itself, establish what a customer can do now. Payment options can also be subject to conditions set by the operator, the card issuer and the payment processor.
A specialist review has described Visa as potentially available across more Australian online casinos than Amex. That is a relative comparison, not confirmation about any named site. It does not establish that every operator accepts Visa, that the method is available to every customer, or that a particular website’s payment information is current. The comparison should not be stretched into a recommendation or a ranked list.
The word “best” introduces another problem. A ranking would need consistent criteria and evidence for each candidate. Payment acceptance alone would not show that one site is safer, more suitable or better than another. Nor would it establish service quality, terms, or legal status. A list that supplies names without comparable, current support may look precise while giving you no dependable basis for judging the entries.
The same caution applies to descriptions such as “Visa casino site” or “Visa pokies site”. These phrases can suggest that Visa is a defining feature of a business, when a payment method is only one detail that may appear in an operator’s payment information. They also blur the difference between a claim about a payment option and an endorsement of the underlying service. A card logo does not tell you whether the operator is authorised to offer its services to people in Australia.
A card logo or an old review cannot, by itself, establish current payment availability or whether an operator is authorised to offer services in Australia.
A meaningful site-specific assessment would require checking the operator’s own current payment terms and confirming that they apply to Australian customers. It would also require distinguishing between what the operator says is available and what is actually permitted in a given case. If the information is outdated, ambiguous or limited to a general logo, the claim should not be treated as verified. A comparison should leave such an entry out rather than fill the gap with assumptions.
This is why a search for Visa-accepting sites cannot be answered responsibly with invented names or an unsubstantiated “top” list. A broad observation about relative acceptance is not a substitute for evidence about each operator.
That limit also applies to requests for a site described as offering instant Visa withdrawals. The word “instant” makes a specific claim about an outcome and timing, while the presence of Visa in general payment information would not prove either. Without operator-specific evidence, such a label would risk promising more than the payment information establishes.
For you, the practical distinction is between a general market-level comparison and a verified statement about one provider. The first can describe a relative pattern cautiously. The second needs current, operator-specific support. Keeping those claims separate prevents a broad comparison from being mistaken for a recommendation, or a payment logo from being treated as proof of a particular service’s availability.
A withdrawal method cannot be inferred from the card used to make a deposit. That distinction matters if you are comparing card payment methods: information about one card network is not a timing estimate or availability rule for another.
A specialist review reports that some casinos may not allow winnings to be paid to an Amex card, or may apply a withdrawal fee. It also describes Amex withdrawals as taking up to five days to clear. These points are not universal terms for every operator, and they cannot be transferred to Visa. A stated processing period for Amex does not predict Visa processing, while an Amex withdrawal restriction does not show whether Visa withdrawals are supported.
The same review says an Amex withdrawal may require an earlier deposit using that card. This is a method-specific condition: it concerns the relationship between an Amex deposit and a later Amex payout. It does not establish that a Visa withdrawal requires a prior Visa deposit, nor that depositing with Visa makes Visa the available payout route. Withdrawal rules are separate from deposit acceptance.
Fees also need to be read as payment-specific terms. A specialist review notes that an operator may charge a fee for an Amex withdrawal, and that a casino may impose a surcharge on Amex transfers. Those statements do not show that Visa withdrawals carry a fee, are fee-free, or follow the same fee structure. The Amex information also describes limits as varying between casinos, so it cannot supply a Visa limit.
Attention A payment method's availability for deposits does not demonstrate that it can receive withdrawals, nor does it guarantee processing times.
For a Visa withdrawal, the relevant details would need to identify Visa as a payout method and state any conditions that apply to it. “Instant” is especially easy to misread: a payment method’s availability for deposits does not demonstrate that it can receive withdrawals, and a withdrawal’s processing time cannot be derived from how quickly a deposit is handled.
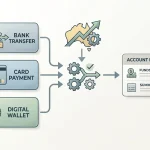
If you are checking a payment option, separate three questions: whether Visa can be used to deposit, whether it can be used to receive a withdrawal, and what fees or timing apply to that withdrawal. An answer to the first question does not answer the other two.
The Amex withdrawal information is useful only as an example of why card-specific terms matter; it is not evidence of Visa withdrawal availability or timing.
Visa acceptance and legal permission are separate questions. A payment card’s availability does not make an online casino lawful to operate for customers in Australia. Under the Interactive Gambling Act 2001, operators are prohibited from providing online casino games to people in Australia. That restriction covers casino-style games offered for real money; it applies to the operator’s conduct, not to whether a particular card can be selected at a cashier.
The Australian Communications and Media Authority (ACMA) administers enforcement of the Act. Offshore sites may be accessible to Australian users, but that access does not mean the operator is permitted to provide the service in Australia. The law is directed at operators, and offshore services are subject to active enforcement measures, including blocking. As a result, a site’s availability at a given time should not be treated as evidence that it is lawful or protected.
The distinction between operator liability and a player’s position matters. The Act does not explicitly make an Australian player’s use of an offshore casino a criminal offence. That does not amount to government approval, a guarantee of access, or protection if a dispute arises. It also does not change the prohibition on operators offering the service to people in Australia.
There is a separate practical issue: Australian consumer law does not protect players who use offshore casinos. If a payment, account balance or attempted withdrawal becomes the subject of a dispute, you should not assume that the consumer protections available for domestic goods and services will apply. An offshore operator’s terms or a foreign licence do not, by themselves, give you the protections of Australian consumer law.
This legal context also means that a search for a casino that accepts Visa cannot be answered as though it were simply a comparison of card options. Card acceptance is a payment feature; the Interactive Gambling Act concerns the provision of the casino service itself. One does not establish the other. A Visa logo, a successful card payment, or a site that loads in a browser does not show that an operator may lawfully offer online casino games to Australian residents.
Legal Prohibition
Under the Interactive Gambling Act 2001, operators are prohibited from providing real-money online casino games to people in Australia.
For a cautious decision, keep those issues distinct: payment functionality concerns how a transaction is presented, while the Act sets a restriction on operators and ACMA enforces it. A player’s lack of explicit criminal liability under the Act should not be confused with a lawful, locally regulated casino market or with access to Australian consumer remedies.
Australia’s everyday payment environment includes several ways to pay at the point of sale. Contactless credit and debit card payments are accepted almost everywhere in the country. Mobile wallets, including Google Pay and Apple Pay, are also accepted almost everywhere. This describes broad acceptance across Australia; it does not establish that every merchant takes every card or wallet.
A card and a mobile wallet are distinct ways to make a payment, even when a wallet is linked to a card. A consumer may use a physical card for one purchase, a phone wallet for another, or a bank-linked service such as PayPal. Australians are comfortable switching among these options. That flexibility is a feature of the wider payment culture, not proof that a particular online service supports each method.
For you, the practical point is that familiarity with one payment method should not be treated as evidence about another. A contactless card working at shops does not confirm that the same card can be used for an online transaction. Nor does widespread use of Google Pay or Apple Pay establish that a particular website accepts either wallet. Acceptance depends on the service and payment arrangement involved; general retail availability cannot answer a site-specific question.
The distinction matters when the subject is casino payments. Broad use of cards and wallets in Australia does not show that online casino games can lawfully be offered to Australian residents, or that any specific operator accepts Visa, another card, or a wallet. Under Australia’s online gambling framework, operators are prohibited from providing real-money online casino games to people in Australia. Familiar payment technology does not change that restriction.
Bank-linked services such as PayPal sit alongside cards and mobile wallets in the choices Australians are comfortable using. Their presence in the broader payment environment is useful context, but it should not be read as confirmation of casino availability or acceptance. Each payment method is a separate option, and general consumer habits do not establish the terms or legality of a particular service.
The reliable distinction is between everyday payment acceptance and online casino access. Australia has widespread contactless card and mobile-wallet acceptance, and consumers are comfortable moving between those methods and bank-linked services. Those facts describe ordinary payment behaviour. They do not identify a casino payment option or imply that online casino transactions are available to Australian residents.
A specialist casino review reported that Visa may be accepted more broadly at Australian online casinos than American Express. That is a relative comparison, not a claim that Visa is accepted everywhere or that every casino offering card payments supports it. The review also reflects a point in time; payment arrangements can change, so the comparison should not be treated as a permanent market-wide rule.
“More broadly accepted” describes the difference between two payment methods across a range of operators. It does not identify which operators accept Visa, establish that a particular casino accepts it, or confirm that a Visa card will work for a specific customer. Those are separate questions. A general comparison cannot substitute for an operator’s current payment information, and it does not establish the terms attached to a card option.
The comparison is also limited to acceptance. It says nothing about whether a Visa payment would be available for a particular purpose, what conditions might apply, or whether Visa could be used to receive funds. Those details cannot be inferred from a statement about relative acceptance. Treating acceptance as proof of every other card feature would collapse distinct payment questions into one.
For the same reason, a broader acceptance claim should not be read as a guarantee about an individual transaction. It offers no assurance about whether a card issuer would approve a payment or whether a specific operator would make Visa available. Nor does it establish a complete list of Australian casinos using Visa.
The cautious conclusion is narrow: the cited specialist review presents Visa as potentially more widely accepted than American Express in the Australian online casino context. It does not support naming a particular Visa-accepting casino or making an unconditional claim about availability. If you encounter a claim that a casino accepts Visa, assess it as a claim about that operator, not as a consequence of the broader comparison.
Visa being accepted as a payment option does not, by itself, establish that funds can be returned to the same card. Deposits and withdrawals are separate functions, and a statement about one should not be treated as proof of the other.
That distinction matters when you assess a claim about a “Visa withdrawal” option. The wording might refer to a card accepted for deposits, a method for paying out eligible balances, or both. Without clear terms covering withdrawals, you cannot infer that a Visa deposit can later be reversed or that winnings can be sent to the card.
Timing is also not something that can be inferred from the card brand. Avoid treating a general claim that a site accepts Visa as a promise about when money will arrive—or whether a card payout is available at all.
If you encounter terms for an online casino with withdrawal on Visa, read the withdrawal conditions separately from the deposit instructions. Look for an explicit statement that Visa is an available payout method, and for any conditions attached to that method. If the terms discuss Visa only as a way to add funds, they do not answer the withdrawal question.
To verify a Visa withdrawal, check for an explicit statement that Visa is an available payout method and review any attached conditions separately from deposit instructions.
In Australia, this payment distinction does not change the legal position: the Interactive Gambling Act 2001 prohibits operators from providing online casino games to people in the country. ACMA enforces the Act, and Australian consumer law does not protect players using offshore casinos. A payment method’s availability should not be taken as evidence that an online casino is lawful or that a withdrawal is assured.
A specialist review has reported that Visa may be accepted more broadly than American Express at Australian online casinos. That is a limited comparison, not a guarantee that Visa will work with a particular operator or account. Acceptance can change, and a general comparison cannot confirm the payment options currently available to you.
The distinction matters because “more broadly accepted” does not mean universally accepted. It also does not establish that a casino accepts Visa for every type of transaction. A payment option can depend on the operator’s arrangements and the restrictions applied by the card issuer. The comparison alone does not identify which factor applies in a particular case.
It also does not establish Visa-specific payment instructions, fees, transaction limits, processing times or withdrawal arrangements. Those details should not be inferred from information about American Express: one card’s terms do not prove another card’s terms. Nor does the comparison confirm that a Visa payment will be approved. Issuer decisions and operator settings can affect whether a transaction proceeds.
For these reasons, the narrow claim is that a specialist review has described Visa as potentially more widely accepted than American Express. It is not evidence that any named casino accepts Visa, that Visa is available to Australian players at a particular site, or that using it is an option you can rely on.
There is also an important market boundary: Australian law prohibits operators from providing real-money online casino games to people in Australia. A statement about relative card acceptance should therefore be read as a description of a reported comparison, not as an invitation or instruction to make a casino payment. Visa’s comparative reach, on its own, says nothing about whether a transaction is lawful, supported or suitable in your circumstances.
A Visa payment method does not, by itself, establish that a casino offers a bonus for using that card. A promotion may have its own eligibility rules, but those rules cannot be inferred from the payment method or from a general claim that Visa is accepted. Treating “Visa bonus” as a standard feature would therefore imply a link that has not been demonstrated.
For you, the practical distinction is between a payment option and a promotion. The first concerns how an account is funded; the second concerns the terms attached to an offer. Unless an operator’s published terms expressly connect an offer to Visa, do not assume that paying with the card qualifies you for a bonus, changes an offer’s value, or affects its conditions.
Be cautious with wording such as “exclusive Visa casino bonus.” A headline alone does not explain who is eligible, what action is required, or whether the offer is available to Australian users. Those details need to appear in the actual terms, and the terms must be read as written rather than inferred from advertising language. A Visa logo beside a promotion is not enough to establish its conditions.
This distinction also prevents a common misunderstanding: payment acceptance and bonus eligibility are separate matters. Even if a payment route is presented, that says nothing on its own about promotional treatment. Do not make a financial decision on the expectation of an added bonus unless the operator clearly states the offer and its applicable terms. In Australia, online casino promotions also sit within strict legal restrictions; promotional language should not be taken as evidence that an online casino service is lawful for Australian residents.
Check the casino’s cashier for American Express as a deposit option. If it is listed, you can select it, enter your card details and the deposit amount in AUD, and submit the payment.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune, and PlayAmo are among the operators listed as accepting Amex deposits for Australian players.
Amex deposits typically have no fee, but a casino may add a 1.5% surcharge, and a 3% currency conversion fee may apply. Withdrawals may also incur a fee.
Check whether American Express is offered in the casino’s cashier for deposits. Even if it is listed, your payment may be declined if Amex blocks transactions to that website.
Each casino sets its own Amex deposit and withdrawal limits, so check the limits shown by that operator in its cashier or payment terms. Amex transaction limits are usually higher than those for Mastercard and Visa.
Amex deposits typically have no fee, but a casino may charge a 1.5% surcharge, and a 3% currency conversion fee may apply. Withdrawal fees may also apply.
Some casinos allow Amex withdrawals, but not all do, and you generally need to have deposited with Amex first. Withdrawals can take up to five days to clear, and a fee may apply.