POLi availability depends on the named operator, customer location and current cashier details, not general references to bank payments.
A claim that an online pokies site accepts POLi is a claim about a particular operator’s payment arrangements, not a general feature of Australian banking or digital payments. It needs to be confirmed for the named service and the relevant customer location. A reference to POLi in a general payment guide, an old review or a search result does not by itself establish that you can select it when using that site.
The clearest confirmation would be current information from the operator that explicitly identifies POLi as an available payment method for Australian customers. Even then, the wording matters. A page may describe a method that is no longer offered, may apply to a different country, or may refer to a service other than the casino cashier. A broad statement such as “bank payments accepted” is not equivalent to naming POLi: it does not tell you which payment service is supported.
A second useful indicator is whether POLi appears in the cashier for the relevant account and location. That is more specific than a general page because it reflects the methods presented to that user at that point. It still needs to be interpreted carefully: a payment option can be displayed without proving that a transaction will be authorised or completed. Availability may depend on account status, location, or changes to the operator’s arrangements. Those are separate questions from whether the operator advertises POLi as a method.
If you’re looking for casinos that accept POLi in Australia in 2026, check the payment details before you deposit, as the information available for each operator varies. This list highlights the specific details provided for each casino.
Lucky Dreams
Lucky Dreams lists a minimum deposit of A$20 when using POLi, making it the clearest POLi-specific option in this list.
DragonSlots Casino
DragonSlots Casino is licensed by the Curacao Gaming Authority and is operated by Jumpman Gaming Ltd.
Wild Tokyo
Wild Tokyo lists a minimum deposit of A$10. Its stated payout times are 30–60 minutes for crypto and 1–5 days for fiat.
MrPacho
MrPacho lists a minimum deposit of A$30. Its stated payout times are 30–120 minutes for crypto and 24–72 hours for fiat.
LevelUp Casino
LevelUp Casino lists a minimum deposit of A$15. Its Curacao eGaming licence is identified as OGL/2023/174/0082 and is held by Dama N.V.
Playfina Casino
Playfina Casino is licensed by Curacao eGaming through Hollycorn N.V., which has held the licence since 2017. Its minimum deposit is A$20–30, depending on the offer.
Roby Casino
Roby Casino is listed as licensed by Curacao eGaming, with Roby Games Ltd named as the licensee.
GoldenCrown
GoldenCrown is listed under a Curacao Gaming Control Board licence, OGL/2023/176/0095, held by Hollycorn N.V.
7Bit Casino
7Bit Casino is listed as a Curacao casino operated by Dama N.V.
Kingmaker
Kingmaker lists a minimum deposit of A$30. Its stated payout times are about 90 minutes for crypto and 1–5 days for fiat.
The distinction is important when reading claims about an Australian online casino that accepts POLi. “Accepts” should mean that the operator makes the method available to the customer for the stated purpose, rather than that POLi is mentioned somewhere on the site. A payment provider’s name in a footer, a list of general banking services, or a third-party article does not show that the option is available in the casino’s cashier. Nor does it establish that every customer sees the same options.
When a claim names a particular operator, check that the name and the payment statement refer to the same service. A casino group may operate more than one brand or serve customers in multiple jurisdictions. A POLi reference connected to one brand or region cannot automatically be applied to another. The relevant question is whether the specific service makes the method available to an Australian customer, not whether the operator has used POLi elsewhere.
It is also worth separating a current acceptance claim from a description of how POLi works. An explanation of a payment service does not prove that a casino supports it. Conversely, the presence of a method in an operator’s information does not establish every detail of a payment transaction. Availability is a narrower point: whether the method is presented as an option for that operator’s customers. Deposit amounts, transaction timing and fees require separate confirmation and should not be inferred from the mere presence of a method name.
 Tether USDT Casinos in Australia: What to VerifyLearn what a Tether casino should disclose about USDT, networks and payment steps, and why a payment label alone does not prove…
 Casino Sites That Accept BPAY in AustraliaLearn why familiar Australian payment habits do not confirm BPAY acceptance, and why a site's cashier is the evidence of its listed…
Search snippets and copied payment lists are weak evidence on their own. They can preserve wording after a cashier or policy has changed, and they may omit restrictions that appear on the operator’s own pages. A statement that an operator “supports POLi” is therefore incomplete unless it is clear which brand, customer location and transaction purpose it covers. If those details are absent, the wording should be treated as a broad claim rather than proof of present availability.
The same care applies to phrases such as “POLi pokies” or “POLi casino.” They can describe a payment preference, but they do not identify a separate kind of game or show that a particular game accepts payment directly. Payment methods belong to the operator’s cashier; game access is a different matter. A site-wide method claim should not be turned into a claim that individual games take POLi.
No operator names or rankings should be inferred from the phrase “best Australian online pokies POLi.” A ranking would require comparable, current evidence about the same feature across the services being compared. Without that, “best” does not clarify whether the comparison concerns payment availability, the range of games, or some other attribute. A precise acceptance statement is more useful than a superlative that has no defined basis.
Legal Warning
The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and Australian consumer law does not protect players using offshore casinos.
There is a further limitation for Australian readers. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and the Australian Communications and Media Authority oversees enforcement of that law. The Act does not make players criminally liable merely for using offshore sites, but Australian consumer law does not protect players who use offshore casinos. A claim that a payment method is available should not be read as evidence that the casino is lawful to offer in Australia, locally regulated, or backed by Australian consumer protections.
A deposit amount, the time a payment takes to appear and any charge attached to it are separate terms. A cashier may display an amount field without making clear whether that figure is subject to a minimum, a maximum or additional conditions. For POLi, do not treat a number shown in a search result, an old review or another operator’s cashier as a term that applies to a particular site. The relevant information is the current payment wording shown for that service, together with any applicable bank or payment-provider terms.
Before relying on a stated minimum, identify what it applies to. It could be a minimum for a particular payment method, a general account-funding minimum or a condition that changes according to currency or account status. Those are not interchangeable. A figure displayed beside POLi should be read in the context of its label and any nearby conditions.
 Casinos That Accept PayID in Australia: Payment ChecksLearn why Amex acceptance does not prove PayID support, how to assess casino payment claims, and why deposit and withdrawal options may…
 Casino Sites That Accept Osko in AustraliaLearn why general payment references do not confirm Osko availability at a casino, what to verify before depositing, and how ACMA’s role…
The same care applies to maximums. A cashier may distinguish between the amount accepted in one transaction and an account-level or daily cap. If a payment is rejected because an amount falls outside a permitted range, the cashier should explain the relevant restriction; do not infer that a limit from another payment method also applies to POLi. If the displayed terms do not make the range clear, the amount cannot safely be assumed.
A figure in Australian dollars is useful only if the transaction is actually being presented in that currency. Check the currency shown before authorising any payment. If the displayed currency differs from your account currency, the amount ultimately debited may depend on conversion terms. Do not assume that a number beside the deposit field represents the complete cost.
“Submitted,” “authorised” and “credited” describe different points in a payment. A confirmation that a request was sent does not by itself establish that the account balance has been updated. A cashier may show a pending status while a transaction is being reconciled, or an attempt may fail before funds are credited. The status wording matters more than a broad claim that deposits are fast.
For any payment method, look for the stated processing expectation and the event it measures: the time to submit a request, receive a payment response or display funds in an account. If timing depends on the bank, provider, maintenance or additional checks, those conditions should be visible as conditions rather than hidden behind a general estimate. Keep any confirmation reference and compare the payment record with the account activity if the displayed status and balance differ.
Do not interpret a delay as proof that a payment has been accepted, or as proof that it has failed. Repeating a payment before the first attempt has a clear status could create a second transaction. Use the stated support route to clarify an unresolved payment rather than making another attempt on the basis of an assumption.
A fee can be charged by the service receiving a payment, by a payment provider or by the bank involved. A cashier’s statement about its own charges may not describe every possible charge connected with a transaction. Check whether the amount shown is the amount requested, the amount to be credited or the total expected to leave the linked account. These values may differ if a fee or currency conversion applies.
Look for fee wording beside the payment option and in the relevant account or payment terms. If no charge is displayed, do not treat that alone as confirmation that every party involved charges nothing. Equally, do not assume that a fee associated with another payment method applies to POLi. The terms need to identify the method and the transaction they cover.
Read the amount range, currency, processing-status wording and fee conditions together. A clear minimum without a clear currency, or a processing estimate without an explanation of when the clock starts, is incomplete information. Save the terms you relied on and the payment confirmation, so you can compare them if the transaction status changes.
 Casinos That Accept Visa in Australia: Payment GuideSee what the available evidence says about Visa acceptance, card deposits, withdrawals and bonuses, and why broad comparisons cannot confirm an operator's…
 Casinos That Accept CashtoCode in Australia: What to CheckLearn how ACMA enforcement and Australia's online casino rules affect CashtoCode claims, and why a payment mention does not verify service access…
These checks describe how to interpret deposit terms; they do not establish that a particular cashier offers POLi or that a payment will be accepted. In Australia, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically in the country. Do not treat a payment option or a completed transaction as evidence that an online casino service is lawful or protected.
A claim that a casino accepts POLi needs to be checked against evidence tied to the specific operator, the Australian audience and the point in time when the claim is made. A payment logo, a search result or a broad statement about payment options does not establish all three. Treat each as a lead to verify, not as proof that you can use the method.
The strongest useful evidence is a current statement in the operator’s own cashier or payment information that explicitly identifies POLi as available to Australian customers. Check that the statement refers to the casino you are assessing, rather than a separate brand, a parent company or a different regional version of a site. Similar names and shared branding do not prove that payment options are shared.
Strongest evidence of POLi availability is a current statement in the operator's own cashier that explicitly identifies the method for Australian customers.
A page describing payment methods should make clear which customers it covers. If it does not specify whether the information applies to Australians, it may describe another country’s cashier. Likewise, a general logo or list of payment brands may be decorative, outdated or relevant only to some users. A method appearing on a page is not enough unless the context connects it to the operator’s current service for the intended audience.
Read the wording closely. “Supports POLi” might be used loosely in promotional material, while a more precise statement would identify POLi as an available cashier option. Do not infer availability from a reference to bank payments, online banking or digital payments: those phrases can describe other methods.
Also distinguish a claim about acceptance from a claim about the quality of a service. Words such as “best,” “instant” or “easy” do not establish that POLi is offered. They add evaluative or performance claims that need separate evidence. A page can repeat an acceptance claim many times without supplying stronger support.
If a page says that a payment method is available but gives no indication of where or when the statement applies, its practical meaning is uncertain. The question is not whether the wording sounds confident; it is whether the operator’s own information supports the precise claim being made.
 Casinos That Accept Litecoin in Australia: Payment GuideLearn how Litecoin differs from cards, mobile wallets and PayPal, and how acceptance, limits, currency costs and withdrawals affect casino payments.
 Australian Casino Sites That Accept Skrill: What’s KnownLearn what can and cannot be established about Skrill deposits, withdrawals and casino claims, including Australia's Interactive Gambling Act and ACMA's role.
An operator’s current cashier information is more directly relevant to its own payment options than a third-party comparison or review. Third-party pages can help identify what to check, but they may retain old details, combine information from different markets or summarise another page imprecisely. A list of casinos said to accept POLi is not reliable merely because it is presented as a ranking.
Look for a clear basis for the claim. Does the page identify the operator and relevant audience? Does it distinguish confirmed information from an assumption? Does it explain when it was checked? If the publisher does not show how it reached the conclusion, you cannot tell whether it reflects current operator information or a copied description.
Payment information can change, and different pages may not be updated at the same time. If an operator’s cashier conflicts with an older review, the discrepancy is a reason to withhold a conclusion, not to select whichever statement is more convenient. Check whether both pages refer to the same brand and audience, and whether either one clearly indicates that its information is current.
Do not treat the absence of POLi from a page as proof that it is unavailable unless the page is clearly a complete, current list of methods for the relevant audience. But do not turn uncertainty into a positive claim either. “Not confirmed” and “accepted” are different conclusions.
Keep the claim narrow. Evidence that a payment option is displayed does not, by itself, establish every condition attached to it or whether it can be used in every account situation. Those are separate questions and should not be folded into a general acceptance label.
Before relying on a claim, make sure it is specific, current, attributable to the operator and relevant to Australian customers. If one of those points is unclear, treat the claim as unverified rather than assuming the missing detail. Avoid using third-party rankings as a substitute for operator evidence, and do not infer support from similar payment names or broad references to banking.
This standard helps prevent an unsupported label from being mistaken for a confirmed feature. It does not establish that any particular casino accepts POLi, nor does a payment claim establish that an offshore gambling service is lawful or protected for Australian consumers.
A POLi option in a cashier, or a claim that POLi can be used to deposit, does not establish that you can withdraw through POLi. Deposits and withdrawals are separate transaction types. An operator may handle them through different methods, under different conditions, or not offer a matching withdrawal route at all. Treat any claim of an “instant POLi withdrawal” as unconfirmed until the relevant withdrawal terms explain what the phrase means.
Before relying on a POLi withdrawal claim, check the operator’s current terms and the cashier’s withdrawal options for Australian accounts. Look for an explicit statement that POLi is available for withdrawals, rather than wording that only describes deposits. If the method is absent from the withdrawal list, ask the operator to clarify in writing whether another route applies. Do not assume that an available deposit option will appear again when you request funds.
The wording should also make clear who can use the route and under what conditions. Check whether the option is limited to particular account types, currencies or transaction circumstances, and whether the operator requires you to use a different method. These are questions for the operator’s published terms; they are not details that can be inferred from POLi being mentioned elsewhere on a site.
Read the fee and timing provisions separately. A withdrawal page should explain whether a charge may apply and how the operator defines processing time—for instance, whether its estimate begins when a request is submitted or after it has been reviewed. A phrase such as “instant withdrawal” is not enough to establish when funds will reach you. Without a stated, applicable timeframe, you cannot predict when the money will be accessible.
Check whether limits or other restrictions apply to withdrawals, and whether the displayed terms are specific to POLi rather than general statements about payments. If the terms do not identify the method, amount conditions, fees and timing clearly, ask for clarification before treating the claim as reliable. Keep a copy of the terms or response you relied on, since cashier options and operator policies can change.
A separate withdrawal route is not necessarily a failed POLi transaction: it may simply be the operator’s stated way of paying out. But you should confirm that route, its conditions and any associated costs before making a financial decision. Do not mistake a deposit receipt or a successful payment for confirmation that a withdrawal can be made by the same channel.
These checks concern what a payment claim says; they do not establish that an offshore casino is lawful to provide services in Australia. Australian consumer law does not protect players using offshore casinos.
Attention! A POLi option in a cashier for deposits does not guarantee that you can use the same method for withdrawals.
Payment availability and legal status are separate questions. A claim that an offshore website accepts POLi, or another payment method, does not establish that the website may lawfully offer real-money casino games to people in Australia. The relevant rule concerns the service being offered, not the route used to move money.
Under the Interactive Gambling Act 2001, operators are prohibited from offering online casino games to people located in Australia. The restriction covers casino-style services such as pokies and table games. It therefore applies to an operator’s offer of the service even if the operator is based overseas or describes itself as licensed in another jurisdiction. An offshore licence does not itself make the service lawful to offer to Australian residents under Australian law.
The Act is directed at providers. It does not explicitly make an Australian player’s use of an offshore casino a criminal offence. That distinction matters: the prohibition on operators should not be rewritten as a claim that players are criminally liable simply for accessing such a site. It also does not mean that using an offshore service is protected or risk-free. Australian consumer law does not protect players who use offshore casinos, so a player may not have the consumer-law protections available in a domestic transaction if a dispute arises.
The Australian Communications and Media Authority, commonly known as ACMA, administers enforcement of the Interactive Gambling Act. Its role is relevant when assessing claims about offshore casino services: the issue is not settled by a site’s payment page, marketing language, or foreign licence. Those details cannot override Australian restrictions on providing online casino games to people in the country.
This context also limits what a payment claim can prove. A website saying that it takes POLi is making a statement about its payment arrangements; it is not evidence that the operator can lawfully provide casino games to Australian residents. Nor does a payment option create Australian consumer-law protection. Treat these as distinct matters: payment functionality concerns how a site says it handles a transaction, while the Act concerns whether the underlying online casino service may be offered here.
When you encounter a claim about an offshore casino, read it without treating the word “available” as a statement about legality or consumer protection. A site may be technically reachable or may describe itself as accepting Australian customers, but neither point changes the legal position of the service. The key distinction is between the operator’s prohibited offer and the absence of an explicit offence for the player merely using an offshore site. For a player, the practical consequence is that Australian consumer law does not provide a safety net for using that service.
A payment method and a casino game describe different parts of an online service. A cashier handles account-level transactions; a game is a separate product made available through the operator. A claim about one does not, by itself, prove anything about the other.
A cashier handles account-level transactions, while a game is a separate product. A payment option in the cashier indicates how to fund an account, not that a specific game has its own payment channel.
That distinction matters when you encounter references to casino games using POLi or to POLi-supported pokies. Even if a payment option appears in a cashier, that would indicate only that the operator presents it as a way to fund an account. It would not show that POLi is built into a particular game, that a game has its own payment channel, or that the game is available to you.
The reverse inference is also unreliable. A page naming a game alongside POLi does not establish that the payment method is accepted. The wording may simply place a game and a payment option in the same discussion. To substantiate a payment claim, the relevant evidence would need to connect the method to the operator’s actual transaction process, rather than merely mention both terms.
For example, a description of a table game or a pokies title can tell you what that game is. It cannot confirm which payment options the operator supports. Likewise, a cashier’s payment information does not establish a game catalogue, access conditions, or whether a particular title is offered to Australian residents. Those are separate claims and require separate evidence.
This also explains why the phrase “POLi casino games” can be misleading. It may sound as though a set of games accepts POLi individually, but the wording alone does not establish that arrangement. In ordinary account-based services, a customer does not pay the game provider directly for each play through a cashier method; however, that general distinction is not proof of how any particular operator has configured its service.
Keep the claims narrow. A statement about a payment option should be read as a statement about account transactions only when the operator’s own information clearly says so. A statement about game availability should be checked independently and should not be treated as evidence that POLi is supported. Neither claim can be safely derived from the other.
For Australian readers, this separation does not change the legal status of real-money online casino games. A payment reference does not make a prohibited service lawful or establish that it is available for use in Australia. Treat payment descriptions and game descriptions as different evidence, and do not infer one from the other.
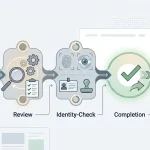
A payment option shown in a cashier and a completed account check are separate parts of an online transaction. Seeing POLi mentioned in a payment claim does not establish that a particular casino supports it, and completing identity checks does not establish that support either. Each claim concerns a different system: the cashier handles payment methods, while account verification checks information about the customer.
Online casinos typically require customers to complete a Know Your Customer (KYC) assessment before they can make financial transactions. The operator may ask for identity or account information and review it before processing activity. The exact documents and checks depend on the operator’s procedures, so do not assume that an account is ready for transactions merely because registration is complete.
For a claim that an Australian-facing casino uses POLi, keep these questions distinct:
An affirmative answer to one does not settle the others. A reference to POLi in a review, advertisement, or account discussion is not proof that the cashier offers it to you. Likewise, an account that has passed verification may still have no such payment option. Do not treat a successful identity check as confirmation that POLi is supported, or a payment-method claim as confirmation that transactions will be available on an unverified account.
This distinction matters when assessing claims about an Australian casino that accepts POLi: the relevant evidence would need to identify the operator’s actual cashier option, while account checks explain a separate condition that can affect financial transactions. The details can change, so a general statement about an operator or payment method may not describe what is available to an individual account.
There is also a legal boundary to keep in view. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players who use offshore casinos. These points do not establish whether a payment method appears in a cashier; they explain why payment claims should not be mistaken for legal approval or consumer protection.
A cashier that lists a payment method for deposits does not, by itself, show that the same method is available for withdrawals. Deposits and payouts are separate transaction types, and an operator may set different conditions for each. So a claim about a “casino with POLi withdrawal” needs evidence that specifically covers withdrawals—not just a deposit logo, a payment-method list, or instructions for adding funds.
Before relying on a statement about a POLi payout, look for the operator’s current written terms describing the withdrawal route. Check whether POLi is named as an available payout method, whether eligibility depends on how the account was funded, and whether other payout options apply. The terms should also explain any applicable fees, limits, processing stages and identity checks. Do not assume that a payment method appearing in one part of the cashier is available in another.
A distinction matters here: a method can be supported for deposits while withdrawals are handled through a different route. Conversely, a general claim that a site “supports POLi” may not specify which transaction types that support covers. If the wording is unclear, it does not establish that an online casino withdrawal through POLi is possible. The uncertainty cannot be resolved by treating deposit support as proof of payout support.
Payment rules can also change. A statement copied from an old review may no longer describe the current cashier or terms. A clear, current operator statement is more useful than an undated summary, but it still does not remove the need to read the withdrawal conditions that apply to the account.
These distinctions do not confirm that any Australian-facing casino offers POLi withdrawals. More broadly, the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia. Australian consumer law does not protect players who use offshore casinos. A payment-method claim should not be mistaken for assurance about the legality of an operator, the availability of a payout route or the protection available if a dispute arises.
In Australia, contactless credit and debit cards are accepted almost everywhere, and mobile wallets such as Google Pay and Apple Pay are similarly widespread. Consumers are also comfortable moving between cards, mobile wallets and services linked to bank accounts, including PayPal. That familiarity shows that people can use several kinds of digital payment in everyday settings; it does not establish which methods an online service supports.
The distinction matters when you see a claim that a site lets customers pay through a particular method. Familiarity with bank-linked payments is not evidence that POLi appears in a site’s cashier, just as broad acceptance of contactless cards does not mean every online service takes card payments. Each method depends on the service’s own payment arrangements and the options it presents to customers.
Payment habits also do not show that a payment option is available for a particular activity. A wallet accepted by many Australian retailers, for instance, cannot be assumed to work for every online transaction. The same reasoning applies when a POLi payment is described as a way to fund online gambling: general comfort with bank-linked services does not confirm that a particular gambling operator accepts it. Nor does it establish that any particular game has a separate payment route.
For a reader comparing payment claims, keep the evidence at the same level as the claim. National familiarity with cards, wallets and bank-linked services describes consumer behaviour broadly. A claim about POLi at a specific site needs evidence about that site, rather than an inference drawn from what Australians commonly use elsewhere.
So, Australians’ willingness to switch between digital payment types provides context for understanding why different methods may be familiar. It cannot answer which casino accepts POLi, or confirm that you can use POLi for online pokies. Those are separate claims and require direct, current information about the relevant service.
A payment method and a promotion are separate parts of an online cashier. Seeing POLi listed as a deposit option would not, by itself, mean that a bonus applies to a payment made with it. Promotion eligibility depends on the offer’s own conditions, which may specify who can take part, which payment methods qualify, and what steps are required.
Before relying on a claim about a POLi-linked casino bonus, read the operator’s terms as well as the offer summary. Check whether the promotion is available to your account, whether POLi deposits are included or excluded, and whether the offer requires you to opt in. A general statement that a casino accepts POLi does not answer any of those questions.
Terms can also affect whether a promotion is useful to you. Look for rules on eligible deposits, expiry, withdrawal restrictions, and any playthrough requirement. Do not assume that a bonus is automatic, that every deposit method qualifies, or that an advertised headline describes the full conditions. If the wording is unclear, ask the operator to confirm the relevant terms before depositing.
In Australia, promotion claims also sit within a restrictive legal environment. The Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people in Australia, and advertising such services to Australian audiences is prohibited. Australian consumer law does not protect players using offshore casinos. A bonus offer should not be treated as reassurance that an offshore service is lawful, locally regulated, or protected for Australian users.
Jackpot City Casino, Spin Palace, Ruby Fortune, Ignition Casino, Joe Fortune and PlayAmo are among the operators identified as accepting Amex deposits for Australian players. Check the cashier for your account to confirm that Amex is currently available.
Open the casino cashier and check whether American Express is listed as a deposit option. Availability can differ between casinos.
Yes, casinos set their own Amex deposit and withdrawal limits, and these can vary. Check the limits shown by the individual casino.
Amex deposits typically have no fee, but a casino may add a 1.5% surcharge, and Amex cards incur a 3% currency conversion fee. Check the casino’s terms and your card’s currency.
Amex may block payments to a particular website, and Australian banks may also block gambling-related transactions on Amex cards. Check with your card issuer and the casino whether the payment is permitted.
Some casinos do not allow withdrawals to Amex, and you generally need to have deposited with Amex first. Where available, a withdrawal can take up to five days to clear and may incur a fee.